


The markets are in an optimistic mood ahead of the key Federal Reserve meeting later tonight. Bond yields are dropping, the oil price is moderating and Brent crude is back below $107 per barrel, equity indices are higher, with US indices also expected to open higher later today.
UK Gilt yields are leading the recovery and are the top performers in the major sovereign bond space today. Gilt yields are recovering from their recent surge, as rate hike bets for tomorrow’s BOE meeting get scaled back. The 2-year yield is down 10bps and the 10-year is down 7bps so far on Wednesday.
More inflation pressure to come
Inflation was not as bad as expected, although it still rose to 3.1% last month. Food price inflation fell to lowest level since 2021, although that is set to rise in the future. Energy prices were the main driver of inflation last month, and that is also expected to get worse due to the surge in retail fuel prices to 2022 highs in the past week. While the Gilt market may be breathing a sigh of relief that inflation was not higher today, we all know there is more to come, and headline price pressures are rising.
UK’s inflation issues are not all caused by geopolitics
Core prices are under a bit more control, but it is worth noting that private rents increased by 3.8% last month, the highest annual rate so far this year, and comes on the back of the Renters Right Act which came into law earlier this year. While it is fair to say that inflation in the UK is caused by geopolitics, this is only part of the problem, and our government’s policies have added to the inflationary pressures in recent years.
Burnham pushes back on suggestions he’s a socialist
Gilt yields were given a helping hand from prime minister Andy Burnham who pushed back on suggestions from one of his former advisors that he is leading a traditional socialist ‘tax and spend’ government. He said that the Budget on 28th October would be challenging, but that fiscal decisions would be prudent in the way he runs the economy. This is a far cry from when he said he would not pay attention to the bond market, this statement suggests its the first thing he looks at with his tea and toast in the morning.
Time is running out to cut UK government spending
With the tax take at a multi decade post-war high, surely this suggests that Burnham might, finally, be looking at the potential for spending cuts in this Budget? Burnham still has to appease his backbenchers, but after the rise in Gilt yields in the last two weeks, time is running out to bring down the UK’s welfare bill.
Benign market backdrop ahead of Fed
Moving to the Fed, this is a benign market backdrop for tonight’s interest rate decision, although it comes after an extremely volatile period for bonds and commodities. There is a 92.7% chance of a rate hike from the Fed tonight. Although the Fed no longer provides official forward guidance, the market has made up its mind that the Fed will hike anyway. The key question is what comes next?
Why Kevin Warsh should watch mortgage rates
There will be one figure that Kevin Warsh should keep in mind: US mortgage rates have climbed to their highest level in more than a year, and the 30-year rate is now at 6.97%. This is tamping down demand for loans, and refinancing is also falling at an 8% annual rate.
While the Fed’s decision won’t directly impact mortgage rates, if Warsh and co do signal that this is not a one-off hike and more could come, then the mortgage rate could surpass 7%, which would be deeply uncomfortable for homebuyers, refinancers, and the housing industry.
Warsh to blame for rush to price rate hikes in US
Kevin Warsh has backed himself into a corner on rates, in our view. He has said on multiple occasions this summer that the Fed’s chief mandate right now is to get inflation down to the 2% target rate. However, it is hard for the Fed to put downward pressure on energy prices, which are surging due to geopolitical events outside of his control. While it is reasonable for the Fed to take a wait-and-see approach before hiking rates, the Fed has been talking tough on inflation, and if they don’t act on it then their credibility could take a hit.
No economic reason to signal rate hiking cycle
Last week’s CPI reading for August was seen as the final straw for markets, with a rush to fully price in a hike later today. However, if Warsh had not been as fixated on inflation in recent months, that may not have been the case. Overall, we do not see a strong economic reason to hike today, and certainly not to signal further hikes are ahead.
However, Warsh has no choice but to do this, otherwise his judgement will be called into question, and this could add even more volatility into the Treasury market, which is calm ahead of this meeting.
Fed Watch List
Warsh is only one member of the Fed, there are 11 other members who also vote on interest rates. This is why the actual rate decision and Warsh’s expected brief press conference are not the only things to look out for tonight. Also worth watching include:
- The Dot Plot - while Warsh may not provide a dot, others will. We have got used to looking at a downward sloping curve in recent years, if this picks up, the market will rush to price in a rate-hiking cycle. There has already been a lot of upside in mortgage rates, yields and in interest rate expectations, so whether or not we get further upside could depend on the pace of any future tightening as signalled by the Dot Plot.
- Trump may go ballistic if the Fed does hike rates tonight, but he can see that mortgage rates are surging even before the Fed concludes their meeting. If he wants lower rates, then he should endeavour to end the war with Iran.
We think that equities can handle one 25bp rate hike fairly easily, but where stocks might come unstuck is if the Fed is clear that this is the start of a rate hiking cycle. Stocks could struggle including tech and consumer-linked names, in that scenario.
The dollar is also in focus tonight. The dollar index has been a top performer in the days leading up to this meeting, and although the FX market is quiet on Wednesday, the dollar is still leading the major FX pack.
USD/JPY is one to watch as it climbs back above 155.00 post the recent burst of strength in the yen. Signs that the Fed is not embarking on a rate hiking cycle could push this pair down towards 150, while a more hawkish outcome could see a return towards 160.
Chart 1: USD/JPY
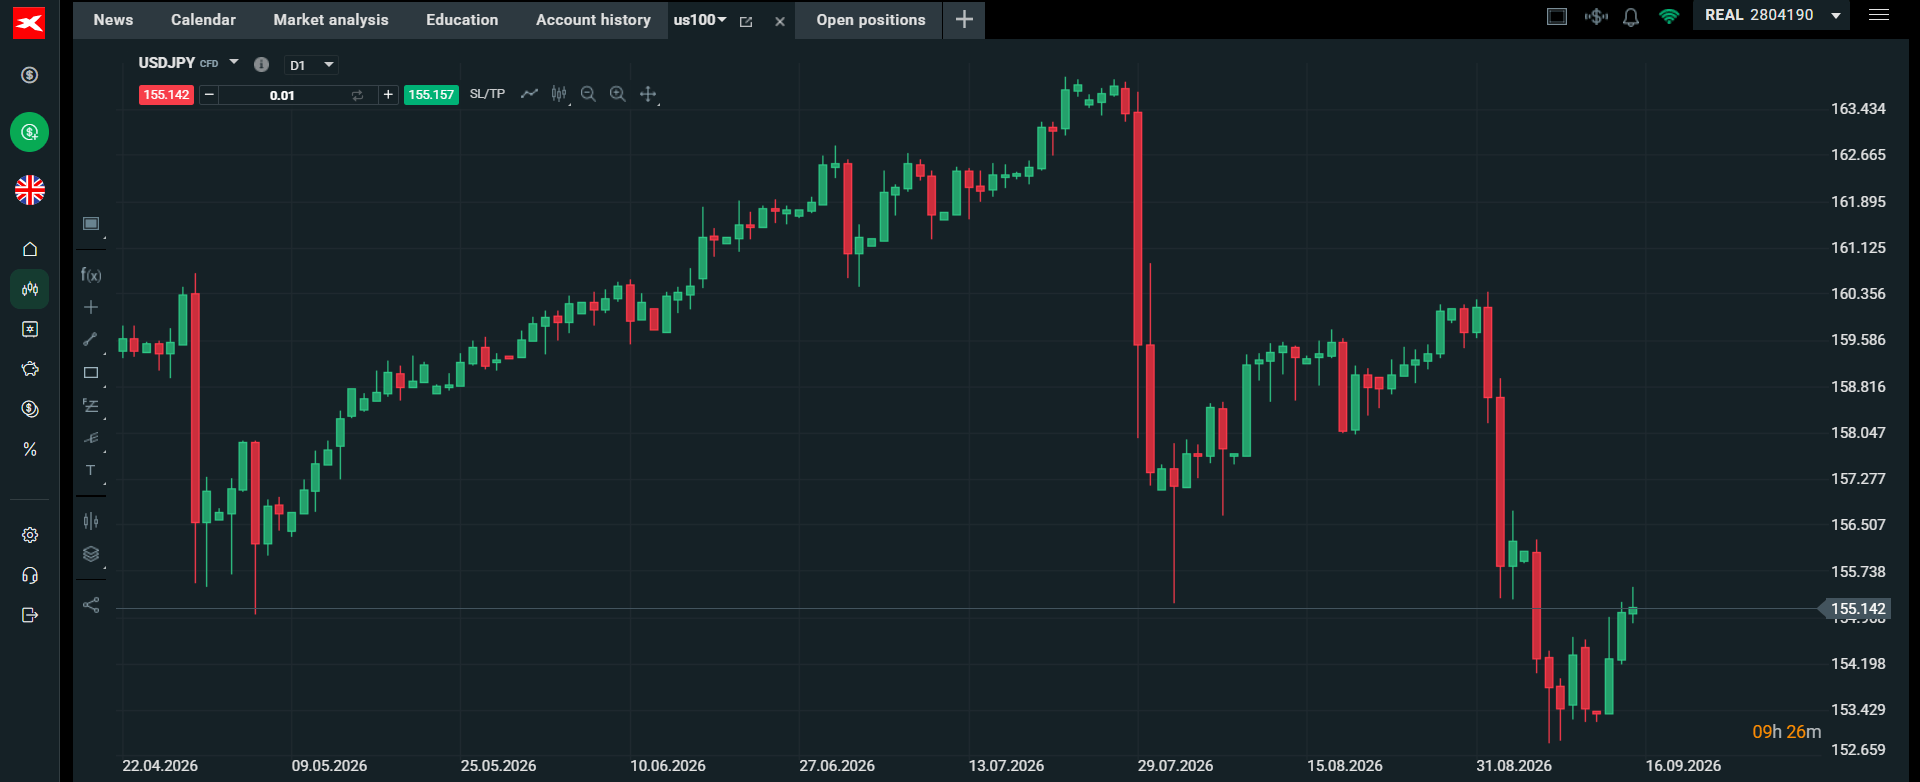
Source: XTB


Gold and Silver Rise Ahead of Fed Decision



Chart of the Day: What’s next for the US stock market? (16.09.2026)


Market Wrap: The Market Slows Its Declines Ahead of the Fed

UK CPI data supports ‘hawkish pause’ from BOE
This content has been created by XTB S.A. This service is provided by XTB S.A., with its registered office in Warsaw, at Prosta 67, 00-838 Warsaw, Poland, entered in the register of entrepreneurs of the National Court Register (Krajowy Rejestr Sądowy) conducted by District Court for the Capital City of Warsaw, XII Commercial Division of the National Court Register under KRS number 0000217580, REGON number 015803782 and Tax Identification Number (NIP) 527-24-43-955, with the fully paid up share capital in the amount of PLN 5.869.181,75. XTB S.A. conducts brokerage activities on the basis of the license granted by Polish Securities and Exchange Commission on 8th November 2005 No. DDM-M-4021-57-1/2005 and is supervised by Polish Supervision Authority.