


Stocks have been remarkably resilient this year. They have navigated geopolitical turmoil, an energy price spike and surging global bond yields which is rapidly pushing up the cost of borrowing. US blue chip stocks are now in their 4th year of a bull market, however, they now face their toughest test of Q4 so far, the latest earnings updates.
High expectations
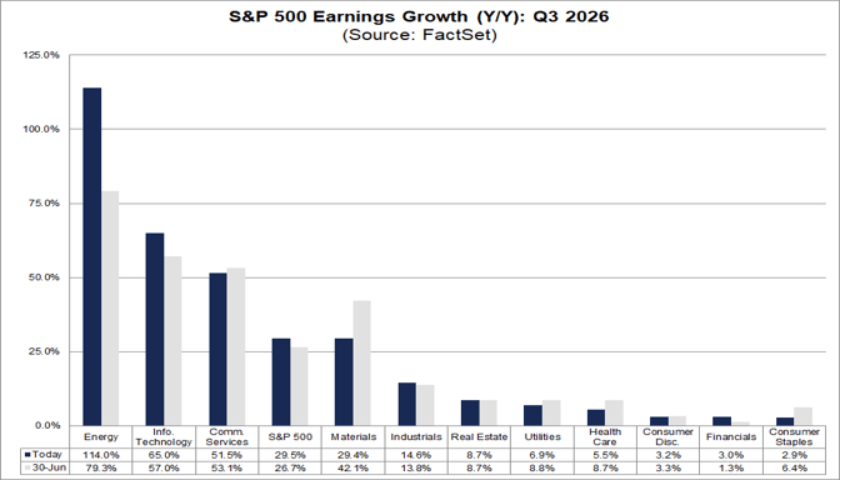
Headline expectations are for earnings growth of 35% for the S&P 500, according to FactSet, and 19% - 20% for the Eurostoxx 600 index. Both of these earnings figures rely heavily on AI and energy. For example, the energy sector on the S&P 500 is expected to rise by 115%, in Europe it is expected to grow by 98%. Earnings growth for AI linked US-listed companies is expected to surpass 65%.
Will earnings continue to exceed expectations?
If S&P 500 earnings growth does surpass 35% for Q3, this would mark the 8th straight quarter of double digit growth and the third consecutive quarter of earnings growth above 25%. In Europe, earnings momentum is also strong. Earnings expanded by more than 24% in Q2, a post-pandemic high, and expectations are for decent growth to continue. Is it any wonder that stock markets are rallying, when earnings are this strong.
Why is the earnings outlook so strong?
As we head into this earnings season, the bar is higher for the US than for Europe, and it is hard to see how the rally in stocks can continue if earnings do not shine. But in the lead up to some major earnings releases, the outlook is strong for several reasons:
- Analysts have been revising up their Q3 estimates since the end of June, which is typically a bullish sign ahead of earnings season.
- Companies themselves are upbeat about their Q3 earnings prospects. 72 companies listed on the S&P 500 out of 113 that issued guidance in Q2, expected positive earnings growth for last quarter.
- Over the past 5 years, actual earnings reported by S&P 500 companies has exceeded estimates by more than 7.5%, on average, according to FactSet.
- No sector on the S&P 500 is expected to report negative earnings for last quarter, this is phenomenal considering interest rate-sensitive sectors of the market appear to be holding up, for now.
Will Q3 earnings focus minds on haves and the have nots?
The earnings story has propelled the US blue chip indices to record highs. However, there have been complaints about narrow breadth, and only a quarter of companies on the S&P 500 registered gains last month, even as the index closed in on a record high.
If you strip out the tech giants, then earnings growth for the S&P 500 is roughly 20%, which is still a decent rate of growth considering the backdrop.
The market impact
The short term risk for stocks is not earnings, we believe they will be strong, instead the risk is from the backdrop including fears about rising interest rates and stubborn inflation. These are the factors that could halt the bull trend in equities.
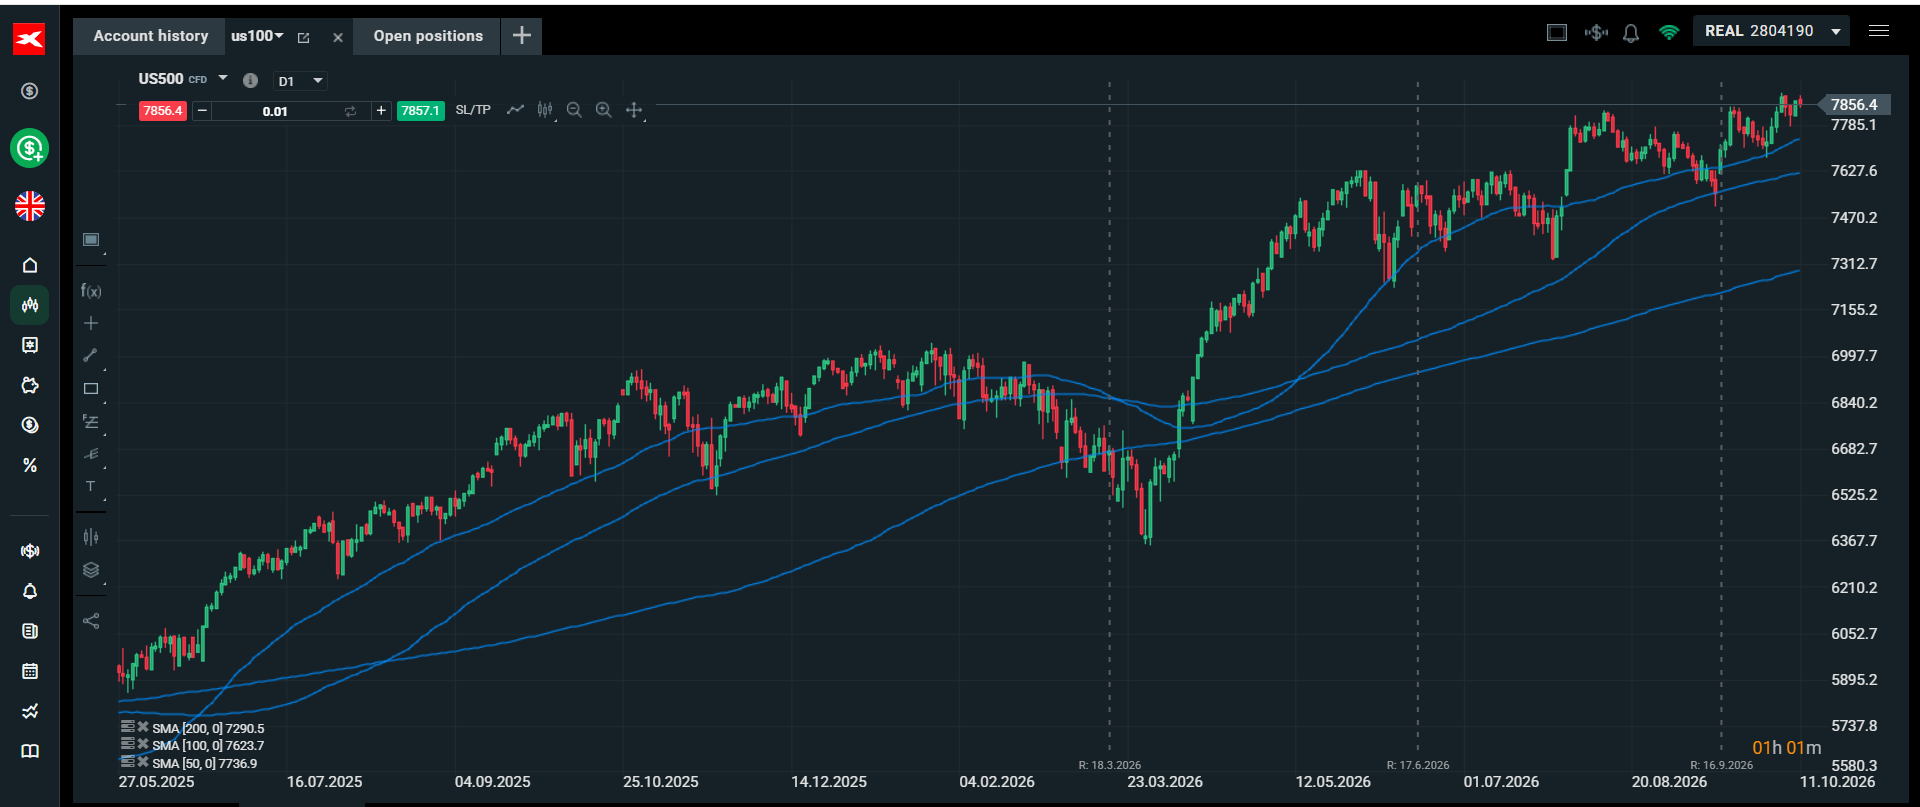
The road to 8,000 for the S&P 500 will run through another quarter of strong earnings growth, however, forecasts for Q4 need to be equally spectacular. It is a big ask, but, for now, analysts expect corporate earnings to deliver.
In Europe, strong earnings growth is nearly all derived from the energy sector. Energy sector earnings growth is expected to be more than 98%, if you strip out this sector, then the growth rate for Q3 earnings is a more moderate 9-10%.
Earnings are expected to be dragged lower by interest-rate sensitive companies. The surge in bond yields and rising interest rates are expected to be a major drag on Europe’s real estate sector, and analysts expect a 17% decline in YoY earnings growth for last quarter.
The FX effect
European stocks have underperformed their US counterparts in recent months, partly due to their lack of AI exposure. The world’s savings are flowing into the AI trade and this is also boosting the USD. In the past 3-months the euro is lower by more than 3% vs. the USD and the pound is down by 2%. We expect European companies with big export businesses to report a drag on earnings from an FX effect and a strong dollar. This could also cloud the outlook for Q4 earnings in Europe, and it is worth watching in the coming weeks.
What to look out for:
- Maintaining and growing margin is going to be important this earnings season. In an environment where the AI build out is sapping cash, companies, especially the hyperscalers in the US, need to ensure they maintain profit margins in order to impress investors as we move through to the end of the year. Earnings for the S&P 500 are expected to grow twice as fast as revenues, so if margin is weak, it will show up in the Q3 reports.
- Capex guidance and AI spend will be imperative this earnings season. The major hyperscalers are expected to spend up to $800bn this year on capex, the majority of which will be spent on AI infrastructure. If companies raise guidance, this could add to fears about the cost of the AI buildout and how sustainable it is.
- Oil and gas firms are all but certain to report stunning earnings growth in Q3 on both sides of the Atlantic because of the war in Iran. However, investors will be watching what they have to say about future revenue growth and whether profits will slump if and when the war comes to an end and energy prices return to some ‘normality’.
- Q4 guidance will be the key to the stock market reaction this earnings season. Analysts are already expecting a strong Q4 earnings season, with S&P 500 earnings growth estimates already topping 27%. Raised or lowered corporate guidance will be important for stocks in the coming weeks.
- Banks, which will start reporting earnings this week, will be an important read on the consumer and their results will also give an important update on the health of Main Street and the broader US economy.
- Investors will also be looking for breadth outside of AI. Are earnings outside of the tech space holding up well, or are cracks starting to appear? In the US, earnings ex-tech are expected to come in around 20%, while in Europe, stripping out the energy sector sees earnings growth for Q3 plunge by 50% to 9%- 10%. A weaker set of earnings for cyclical sectors, or sectors that are interest-rate sensitive, could add to stock market jitters.
Key dates:
JP Morgan: 13th October
ASML: 14th October
TSMC: 15th October
Shell: 29th October
Meta: 28th October
Alphabet: 27th October
Apple: 2nd November
Nvidia: 25th November
Amazon: 29th October
Tesla: 21st October
Chart 1: S&P 500
Source: XTB
Chart 2: Earnings expectations by S&P 500 sector
Source: FactSet


🚩 US100 loses 0.7%


🖥️Chart of the Day - US100: Is the KOSPI crash a foretaste of Nasdaq's troubles?



Economic Calendar - Start of Wall Street Earnings Season, Hawkish RBA, and Middle East Tensions (13.10.2026)



Morning Wrap: Tech Crash in Asia and Hawkish Central Banks in the Shadow of an Oil Shock (13.10.2026)
This content has been created by XTB S.A. This service is provided by XTB S.A., with its registered office in Warsaw, at Prosta 67, 00-838 Warsaw, Poland, entered in the register of entrepreneurs of the National Court Register (Krajowy Rejestr Sądowy) conducted by District Court for the Capital City of Warsaw, XII Commercial Division of the National Court Register under KRS number 0000217580, REGON number 015803782 and Tax Identification Number (NIP) 527-24-43-955, with the fully paid up share capital in the amount of PLN 5.869.181,75. XTB S.A. conducts brokerage activities on the basis of the license granted by Polish Securities and Exchange Commission on 8th November 2005 No. DDM-M-4021-57-1/2005 and is supervised by Polish Supervision Authority.