


Today's macroeconomic calendar is very light, while the scheduled quarterly earnings releases in the US are focused mainly on smaller companies, which may shift investors’ attention primarily toward Europe. In Europe, several large and market-relevant companies have already reported results today, including Siemens Energy, E.ON, RWE, ABN AMRO, Vestas Wind Systems and Swiss Life. Additional points of interest during the session include speeches from ECB officials and the OPEC Monthly Report.
Economic calendar
-
7:00 AM GMT – Germany: Final HICP YoY: 2.8% (forecast: 2.8%, previous: 2.8%)
-
7:00 AM GMT – Germany: Final CPI YoY: 2.8% (forecast: 2.8%, previous: 2.8%)
-
7:00 AM GMT – Germany: Final HICP MoM: -0.1% (forecast: -0.1%, previous: -0.1%)
-
7:00 AM GMT – Germany: Final CPI MoM: -0.2% (forecast: -0.2%, previous: -0.2%)
-
9:00 AM GMT – Italy: Industrial Production MoM: forecast 0.7%, previous -1.3%
-
10:30 AM GMT – Germany: 30-year Bund yield: previous 3.8%
-
12:00 PM GMT – US: MBA Mortgage Applications: previous -1.2%
-
12:00 PM GMT – US: MBA 30-year Mortgage Rate: previous 7.30%
-
1:00 PM GMT – OPEC: Monthly Report
-
9:45 PM GMT – New Zealand: External migration and visitor arrivals; in September, the figure increased by 8% YoY
US corporate earnings
-
Before the US market open: Rumble, Riskified, Sigma Lithium, Innoviz Technologies, ICL Group, CGI, EuroDry, Boyd Group Services, Aebi Schmidt, Oddity Tech, Valens Semiconductor, uCloudlink, Radcom, Polypid, Nayax, MiNK Therapeutics
-
After the US market close: Osisko Gold Royalties, Franco-Nevada, Aevex, Okeanis Eco Tankers, EZCORP, Corteva, Integra Resources, Pelagos Insurance Capital, Teekay, Star Equity Holdings
-
European corporate earnings: Siemens Energy, E.ON, RWE, ABN AMRO, Vestas Wind Systems, Poste Italiane, Swiss Life, Brenntag, voestalpine, Snam, Technoprobe, De’Longhi, Avio
Central bank speeches
-
7:50 AM GMT – Eurozone: ECB’s Cipollone speaks
-
8:10 AM GMT – Eurozone: ECB’s Kazaks speaks
-
8:20 AM GMT – Eurozone: ECB’s Nagel speaks
-
8:45 AM GMT – Eurozone: ECB President Christine Lagarde speaks
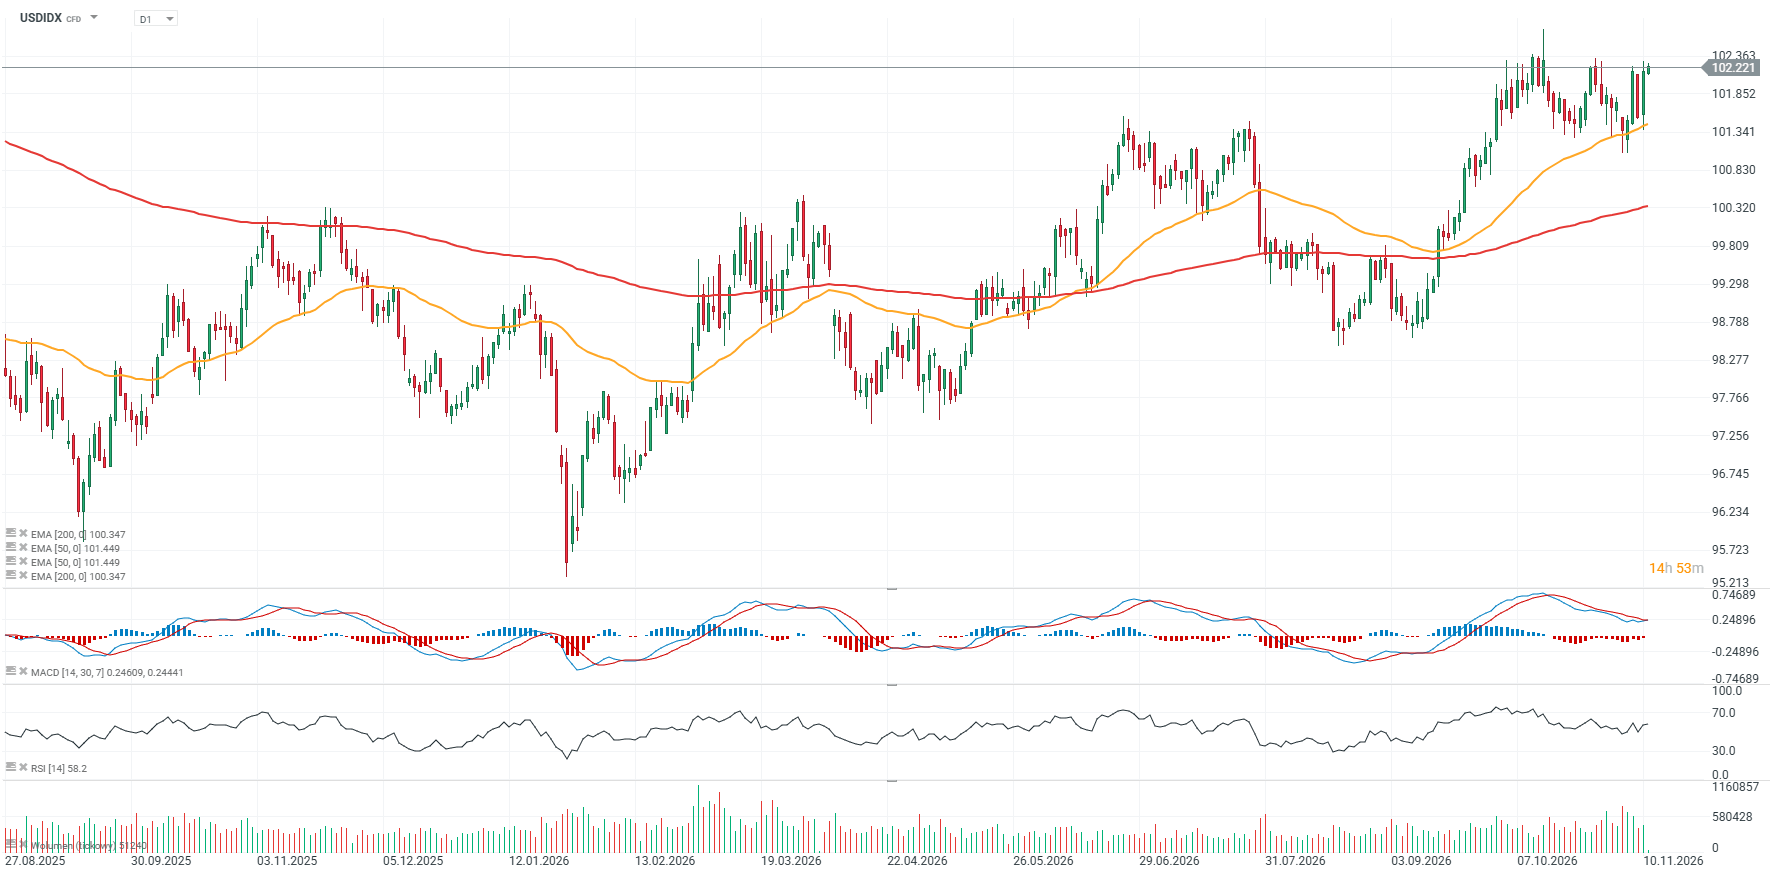
USDIDX chart (D1 interval)
The US Dollar Index futures contract is trading higher today, extending yesterday’s gains supported by a hotter-than-expected CPI reading and hawkish comments from Fed’s Waller, who signalled a potential need for a 50 bp rate hike in the US and indicated that, over time, some of the policy easing already delivered by the Fed could be reversed. Key resistance levels are located near 102.3 and 102.5, based on previous price reactions, while an important support zone can be found around 101.3, also reinforced by price-action methodology.
 Source: xStation5


Morning wrap: Equity indices extend rebound 🔼 CoreWeave outlook supports Nasdaq? (11.11.2026)



Daily summary: CPI reading hits markets, hawkish Fed and Wall Street selloff
US OPEN: Higher CPI Inflation Cools Sentiment, Anthropic Targets $1.4 Trillion Valuation

Hot CPI boosts Fed hike chances
This content has been created by XTB S.A. This service is provided by XTB S.A., with its registered office in Warsaw, at Prosta 67, 00-838 Warsaw, Poland, entered in the register of entrepreneurs of the National Court Register (Krajowy Rejestr Sądowy) conducted by District Court for the Capital City of Warsaw, XII Commercial Division of the National Court Register under KRS number 0000217580, REGON number 015803782 and Tax Identification Number (NIP) 527-24-43-955, with the fully paid up share capital in the amount of PLN 5.869.181,75. XTB S.A. conducts brokerage activities on the basis of the license granted by Polish Securities and Exchange Commission on 8th November 2005 No. DDM-M-4021-57-1/2005 and is supervised by Polish Supervision Authority.