

- Geopolitical tensions in the Middle East and central bank actions drive early week volatility in commodity and currency markets.
- The People's Bank of China strengthens the yuan to 6.6682 per USD and injects 398 billion CNY of liquidity.
- Major central banks including the Fed, ECB, and BoJ prepare interest rate decisions alongside heavy corporate earnings releases.
- Crude oil and EUR/USD face heightened price swings amid supply risks, economic data, and shifting US Treasury yields.
The start of the week brings elevated volatility to the commodity and currency markets due to geopolitical events. The focus is on the Middle East following reports of Yemeni Houthi attacks on oil facilities and an airport in Saudi Arabia, along with coalition retaliatory strikes, coinciding with diplomatic meetings in Tehran.
In China, the 5th Plenum of the Communist Party has begun, and the People's Bank of China decided to significantly strengthen the yuan and inject 398 billion CNY of liquidity. Today's macroeconomic calendar is moderately busy: the most important point of the European session will be the release of German business sentiment according to the Ifo institute, while in the US investors will focus on financial reports from mega-cap companies. However, it is worth emphasizing that the entire week is extremely interesting. We have decisions from the Fed, ECB, and BoJ, and in addition, we will also see earnings releases from many major American companies such as Alphabet, Microsoft, or Amazon!
Key releases from the Asian session
- China: The People's Bank of China set the yuan reference rate at its strongest level since February 2023, and the onshore yuan strengthened to 6.6682 per dollar. The central bank also injected 398 billion CNY into the market via reverse repo operations.
- Saudi Arabia: Published government data showed a 11.5% y/y drop in goods exports in August, including a 9.1% y/y decline in non-oil exports, reflecting pressure on the kingdom's trade revenues.
- South Korea: The Bank of Korea placed 91-day monetary stabilization bonds at a yield of 3.210%.
Macroeconomic calendar (CET)
- 10:00 Germany - Ifo Business Climate Index. Consensus: 90.0. Previous reading: 89.9.
- 12:00 United Kingdom - CBI Realized Sales. Consensus: -47. Previous reading: -55.
Corporate earnings results
- Verizon Communications Inc. (VZ) — before market open, EPS forecast: $1.27. Key barometer of American consumer spending and telecom market stability.
- Cemex S.A.B. de C.V. (CX) — before market open, EPS forecast: $0.25. Global building materials producer, important for assessing the pace of infrastructure investment in the Americas.
- Welltower Inc. (WELL) — after market close, EPS forecast: $1.64. Leading REIT with exposure to healthcare and senior housing infrastructure, reflecting the health of commercial real estate.
- Cadence Design Systems, Inc. (CDNS) — after market close, EPS forecast: $1.61. Important indicator of demand in the semiconductor and design software sector driven by the AI trend.
- Nucor Corporation (NUE) — after market close, EPS forecast: $5.71. Largest steel producer in the US, serving as a direct gauge of heavy industry and construction activity.
- Public Storage (PSA) — after market close, EPS forecast: $4.27. Self-storage industry leader, reflecting mobility and budget flexibility of US households.
- Other mid- and small-cap companies (including The Hartford, Celestica, Cincinnati Financial, Brown & Brown, Principal Financial, POSCO, Amkor, Rambus) will publish their results mostly after the close of the Wall Street session.
Markets to watch
- Crude Oil (Brent / WTI) — Military tensions surrounding oil facilities in Saudi Arabia and drone attacks could trigger a demand impulse and a supply risk premium.
- EUR/USD — The major currency pair will react to the German Ifo index reading; lack of improvement in manufacturing and service sentiment could solidify pressure on the euro.
- Chinese Yuan (USD/CNH) — Strengthening of the exchange rate by the People's Bank of China and ongoing discussions at the 5th Plenum of the CPC create conditions for heightened volatility in Asian currencies.
EURUSD Technical Analysis
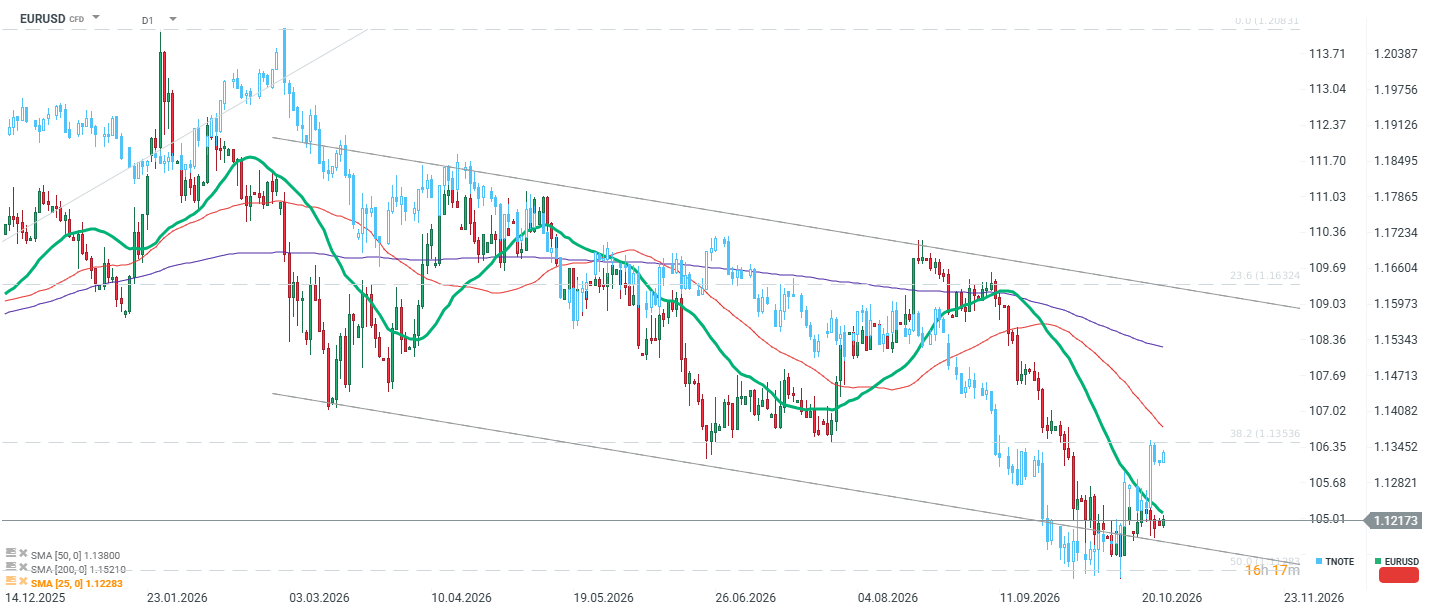
EURUSD is stabilizing above 1.12, but is currently capped by the 25-session moving average, which has remained untouched since the start of the current downward impulse lasting 1.5 months now. It is worth noting a clear rebound in TNOTE, but it is not linked to lower expectations of rate hikes, but rather a demand for safety, which further supports the dollar. Nevertheless, if yields were to fall more sharply from current levels, there is a chance for EURUSD to hold permanently above the critical 1.12 level. However, if yields return to growth, as was the case at the end of February (due to rising oil prices), EURUSD could dive even below 1.11.



Elections in Brazil: Lula returns to power, markets react with panic. Brazilian ETF loses nearly 15% in Tokyo. What about USDBRL, soybeans, sugar, BRAComp, and ETFs?


🟢Morning Wrap: Lack of escalation lowers oil prices. Unexpected Lula victory hurts Brazilian stock market

Daily Summary: Oil at five-month highs, indices under pressure (23.10.2026)

BREAKING: France slows down, Germany holds on. Euro falls below 1.12
This content has been created by XTB S.A. This service is provided by XTB S.A., with its registered office in Warsaw, at Prosta 67, 00-838 Warsaw, Poland, entered in the register of entrepreneurs of the National Court Register (Krajowy Rejestr Sądowy) conducted by District Court for the Capital City of Warsaw, XII Commercial Division of the National Court Register under KRS number 0000217580, REGON number 015803782 and Tax Identification Number (NIP) 527-24-43-955, with the fully paid up share capital in the amount of PLN 5.869.181,75. XTB S.A. conducts brokerage activities on the basis of the license granted by Polish Securities and Exchange Commission on 8th November 2005 No. DDM-M-4021-57-1/2005 and is supervised by Polish Supervision Authority.