


Monday’s trading session has got off to a negative start. The combination of rising oil prices and fresh concerns over regulation of the artificial intelligence sector is clearly weighing on global stock markets. Major US futures contracts are opening the week with sharp falls: the technology-heavy US100 is down 1.31 per cent, whilst the broad-based US500 is down 0.57 per cent. This pessimism is also spreading to Europe, where the German DE40 is down 0.29 per cent and the EU50 is down 0.37 per cent. On a daily basis, investors’ attention is focused on the actions of the People’s Bank of China (PBoC) and this afternoon’s inflation data from Canada. The Chinese central bank has announced it will step up support for the real economy, including measures to stabilise the property market and develop an offshore market for the yuan. In the Middle East, there has been a decline in the daily number of cargo ships passing through the Strait of Hormuz, which, given ongoing geopolitical tensions, may fuel volatility in the oil market. In the foreign exchange market, we saw the US dollar strengthen against the yen (the USD/JPY pair rose by 0.3% to 154.02). Overnight, data was released from New Zealand (a slight improvement in the services sector) and Japan (a disappointing industrial production reading). The key events on today’s calendar will be this afternoon’s CPI inflation figures from Canada and this evening’s speech by ECB President Christine Lagarde.
Macroeconomic calendar
- 08:30 Switzerland – Producer and importer price index m/m. Consensus: 0.0%. Previous reading: -0.1%.
- 14:30 Canada – Median CPI y/y. Consensus: 2.0%. Previous reading: 2.0%.
- 14:30 Canada – Industrial sales m/m. Consensus: -0.2%. Previous reading: 0.1%.
- 15:30 UK – Conference Board Leading Indicators Index m/m. Previous reading: -0.4%.
- 17:15 Eurozone – Speech by ECB President Christine Lagarde.
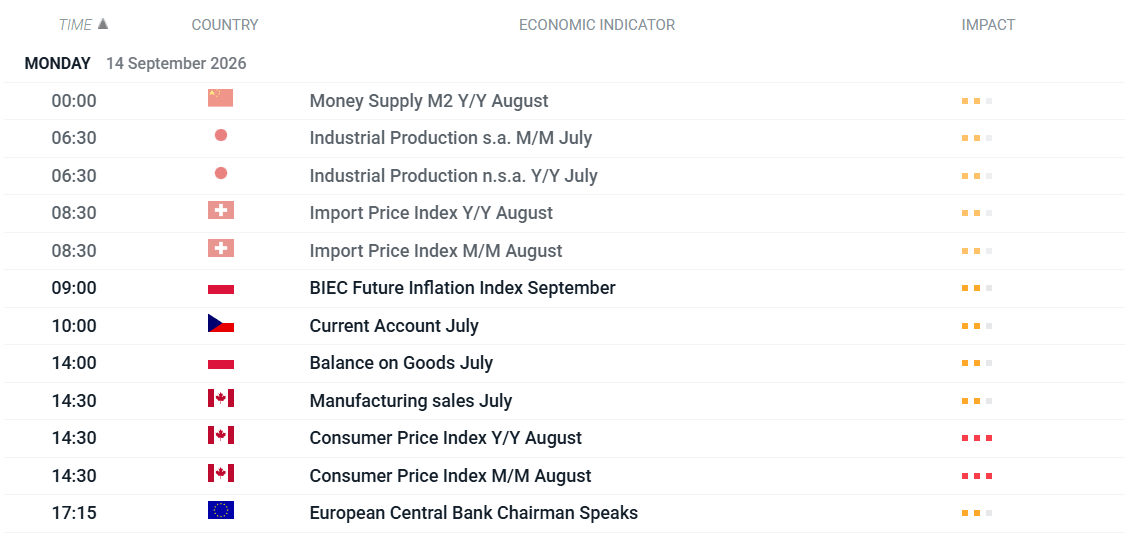
Source: xStation
Markets to watch
- CAD (Canadian dollar) – The release of a comprehensive set of consumer price index (CPI) data at 14:30 will be crucial for expectations regarding the Bank of Canada’s interest rates, which will lead to increased volatility in CAD-related currency pairs.
- Crude oil (WTI/Brent) – A reduction in shipping capacity through the Strait of Hormuz, coupled with dovish stimulus signals from the People’s Bank of China, may support oil prices in the face of supply risks and a potential rebound in demand.
- EUR/USD – Investors will be analysing ECB President Christine Lagarde’s evening speech (17:15) for clues regarding the pace of interest rate cuts in the eurozone, which will directly affect the volatility of the main currency pair.


The Week Ahead


Morning Wrap: A gloomy start to the week amid rising oil prices and turmoil surrounding OpenAI 🚨


🔴Daily summary: Wall Street ignores hawkish inflation, oil falls sharply despite geopolitical tensions

⚠️Three Markets to Watch Next Week (11.09.2026)
This content has been created by XTB S.A. This service is provided by XTB S.A., with its registered office in Warsaw, at Prosta 67, 00-838 Warsaw, Poland, entered in the register of entrepreneurs of the National Court Register (Krajowy Rejestr Sądowy) conducted by District Court for the Capital City of Warsaw, XII Commercial Division of the National Court Register under KRS number 0000217580, REGON number 015803782 and Tax Identification Number (NIP) 527-24-43-955, with the fully paid up share capital in the amount of PLN 5.869.181,75. XTB S.A. conducts brokerage activities on the basis of the license granted by Polish Securities and Exchange Commission on 8th November 2005 No. DDM-M-4021-57-1/2005 and is supervised by Polish Supervision Authority.