

- Alphabet expects 2026 capital expenditures to exceed 200 billion USD, driving negative free cash flow.
- Microsoft projects fiscal year 2027 capital expenditures to surpass 190 billion USD while Azure cloud growth is estimated near 45 percent.
- Hyperscalers face rising market scrutiny over whether massive artificial intelligence infrastructure spending translates into sustainable cash generation.
Alphabet (GOOGL). Q3 2026 Results
Alphabet faces a test in which key will be comparing rising expenditure on AI infrastructure with the dynamics of the traditional advertising business and the cloud segment. Alphabet seemed until recently one of the most important winners in terms of profitability related to AI investments, but massive CAPEX causes investors to ask more and more questions.
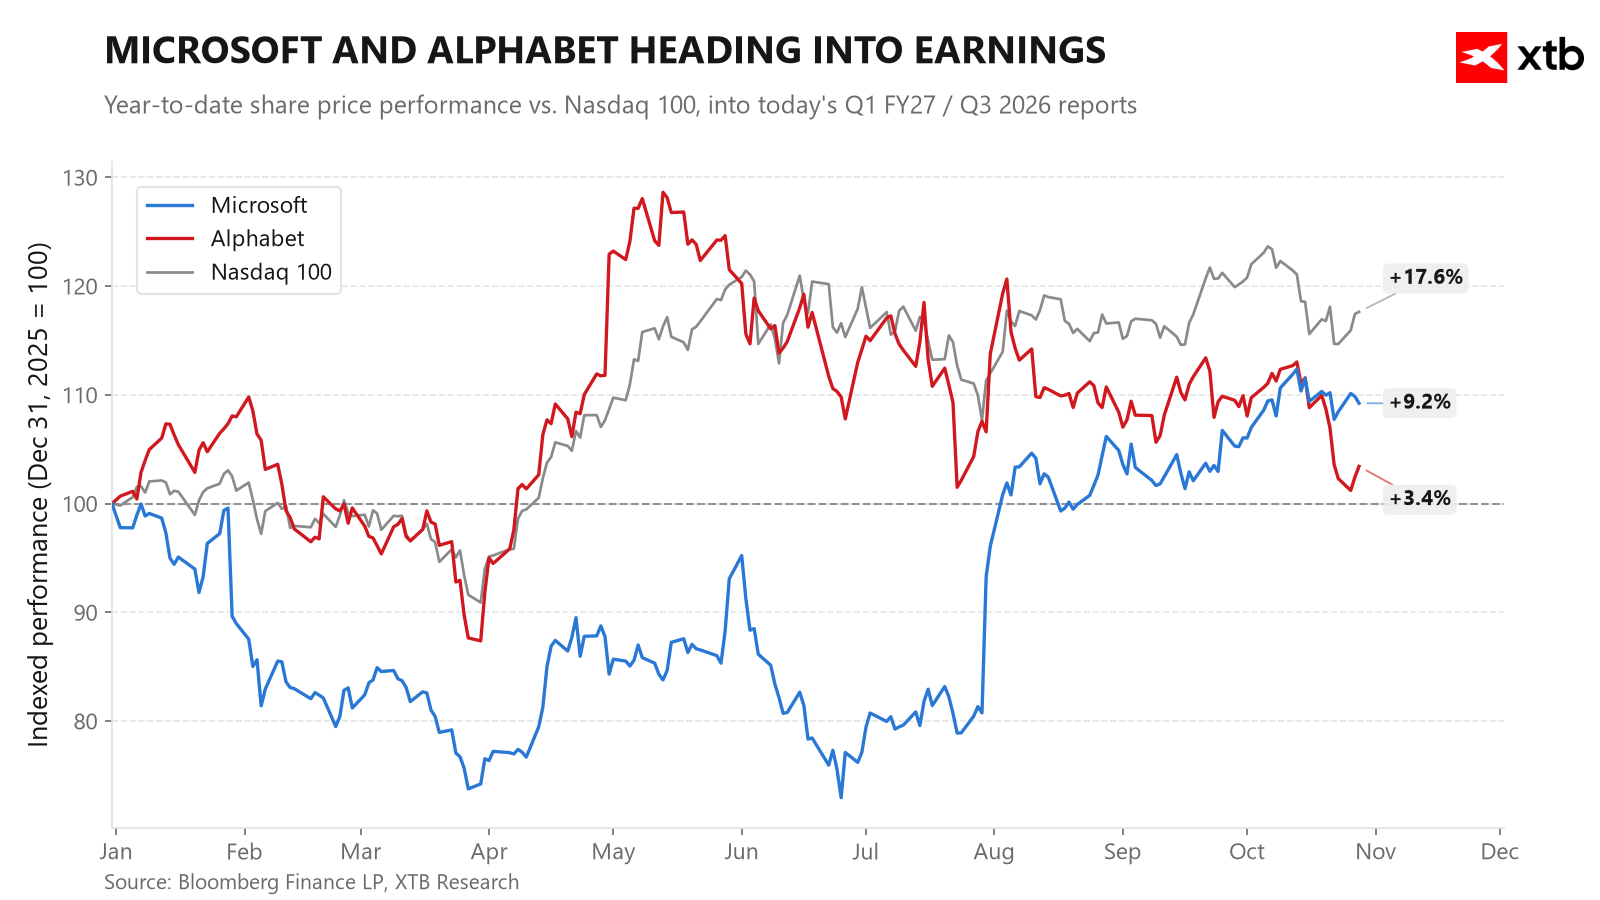
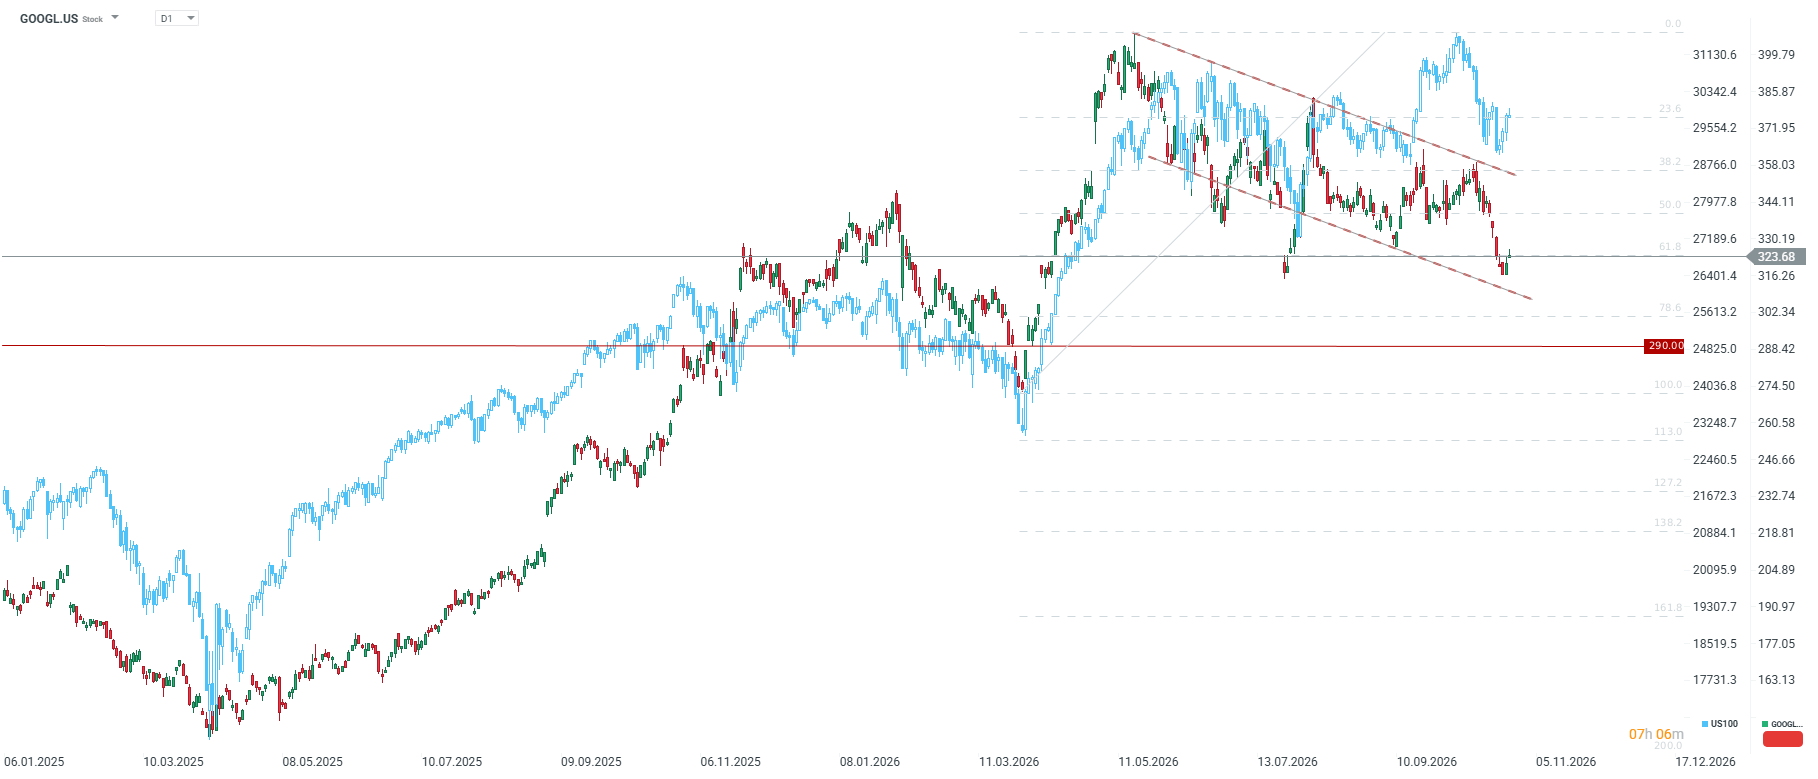 Alphabet has been in a clear downtrend since May's all-time highs and is currently testing the vicinity of key support associated with the last upward impulse. Alphabet performed slightly worse recently even than the broader Nasdaq 100 index. A significant beat of the consensus could help the company, but investors will still largely focus on CapEx.
Market expectations and key metrics:
- Earnings per share and revenue: Expected earnings per share is $2.99–3.03 on revenue of $127.9 billion (+25% YoY).
- Google Cloud: Revenue estimated at around $29 billion, representing an 89–91% YoY increase.
- Search engine and ads: Projected growth slowdown to 15–17% (compared to 19% in Q1 and 17% in Q2) due to concerns about the impact of AI features (AI Overviews) on click-generating traffic.
- Capital expenditures (CapEx): Expenses in 2026 are expected to exceed $200 billion (more than double YoY increase), leading to negative free cash flow this year and next.
- Valuation and forecasts: Options price post-earnings stock move at 5.8%. Analysts' average target price is $429 (64 buy recommendations, 7 neutral, 0 sell).
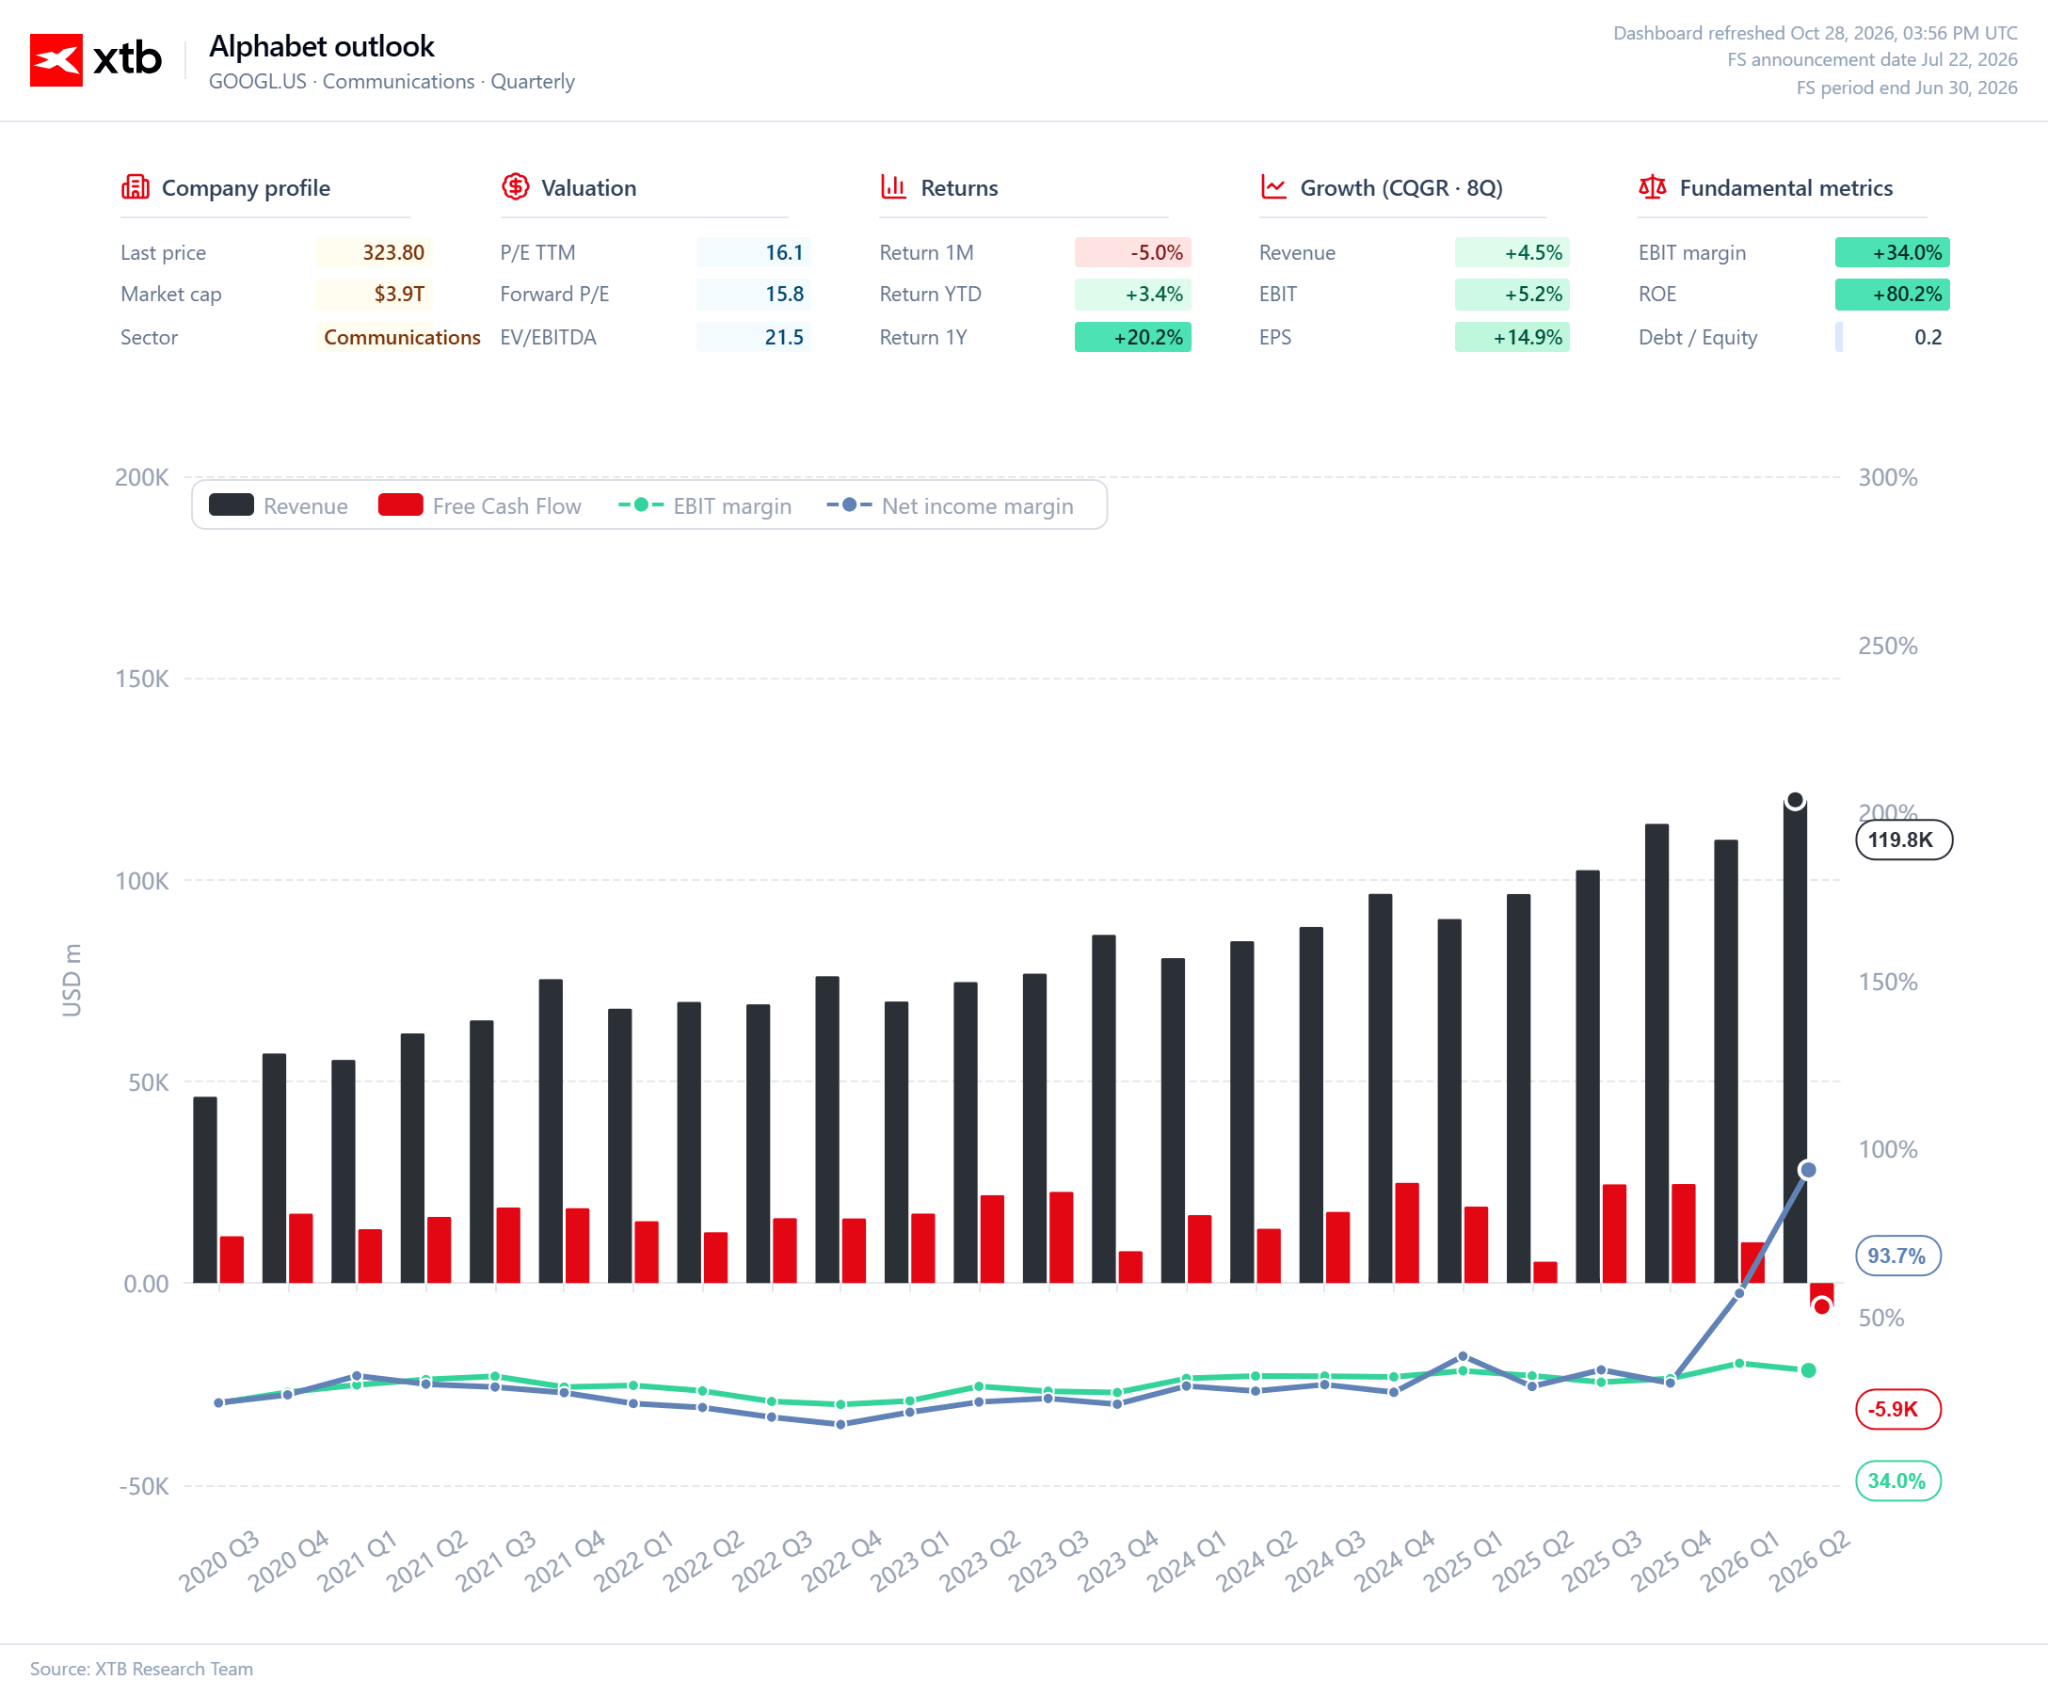 Already in the previous quarter, the company showed a negative free cash flow (FCF).
Commentary:
The main source of uncertainty around Alphabet remains a clear disconnect between rising AI spending and pressure on free cash flows, which pushed the stock price close to a bear market boundary (down around 20% since May). Despite this, dynamic cloud growth and potential new revenue streams, such as OpenAI's interest in purchasing Google computing chips, show that the company holds strong assets in the tech race, maintaining analysts' optimism.
Microsoft (MSFT). Q1 Fiscal Year 2027 Results
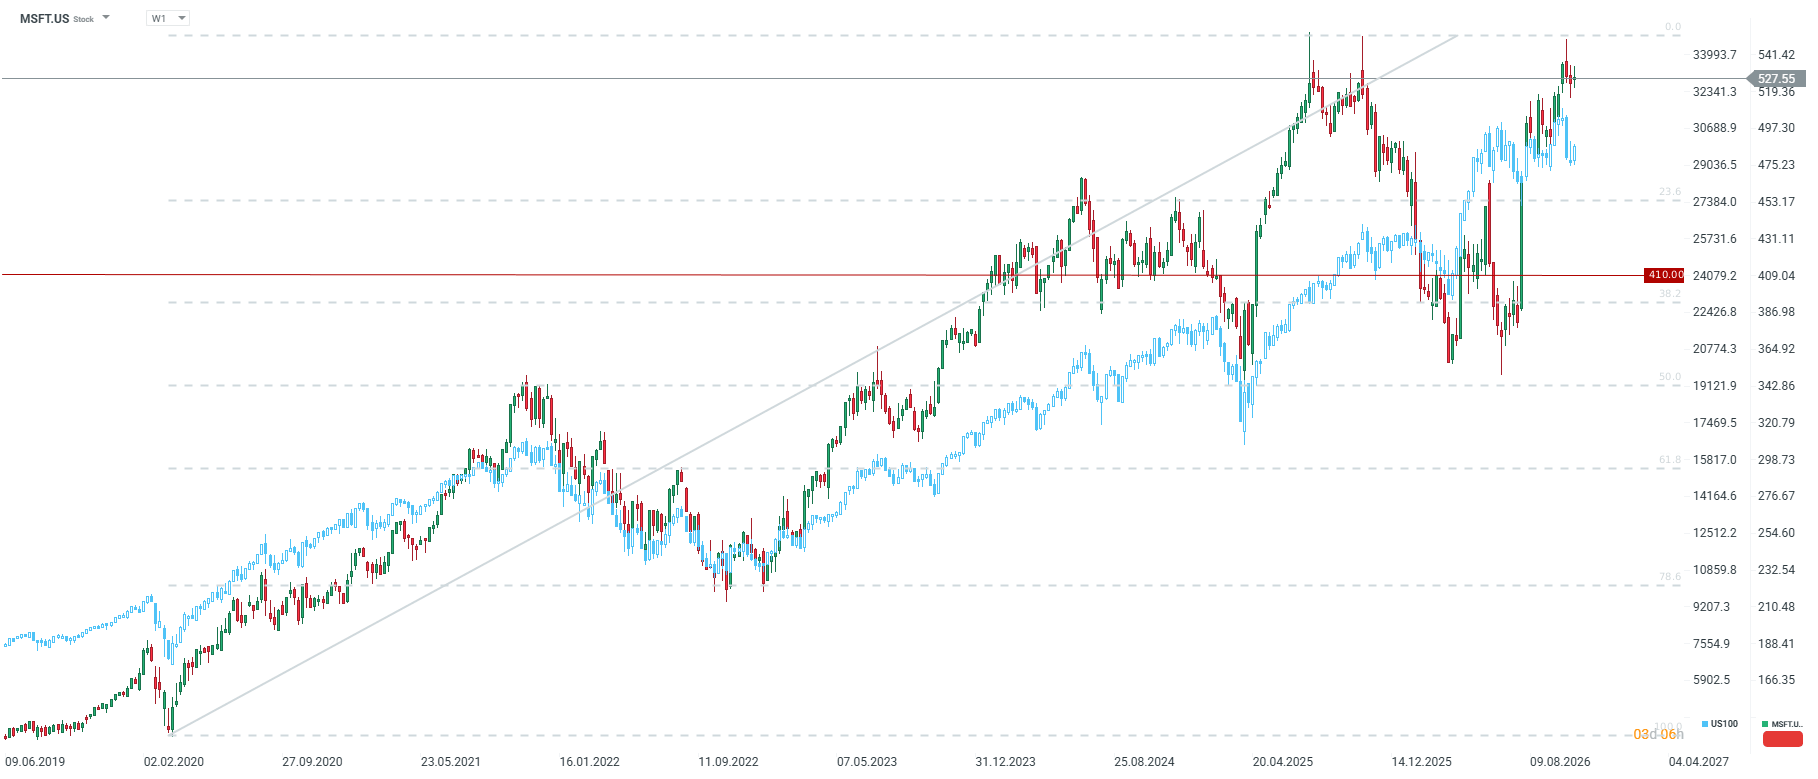
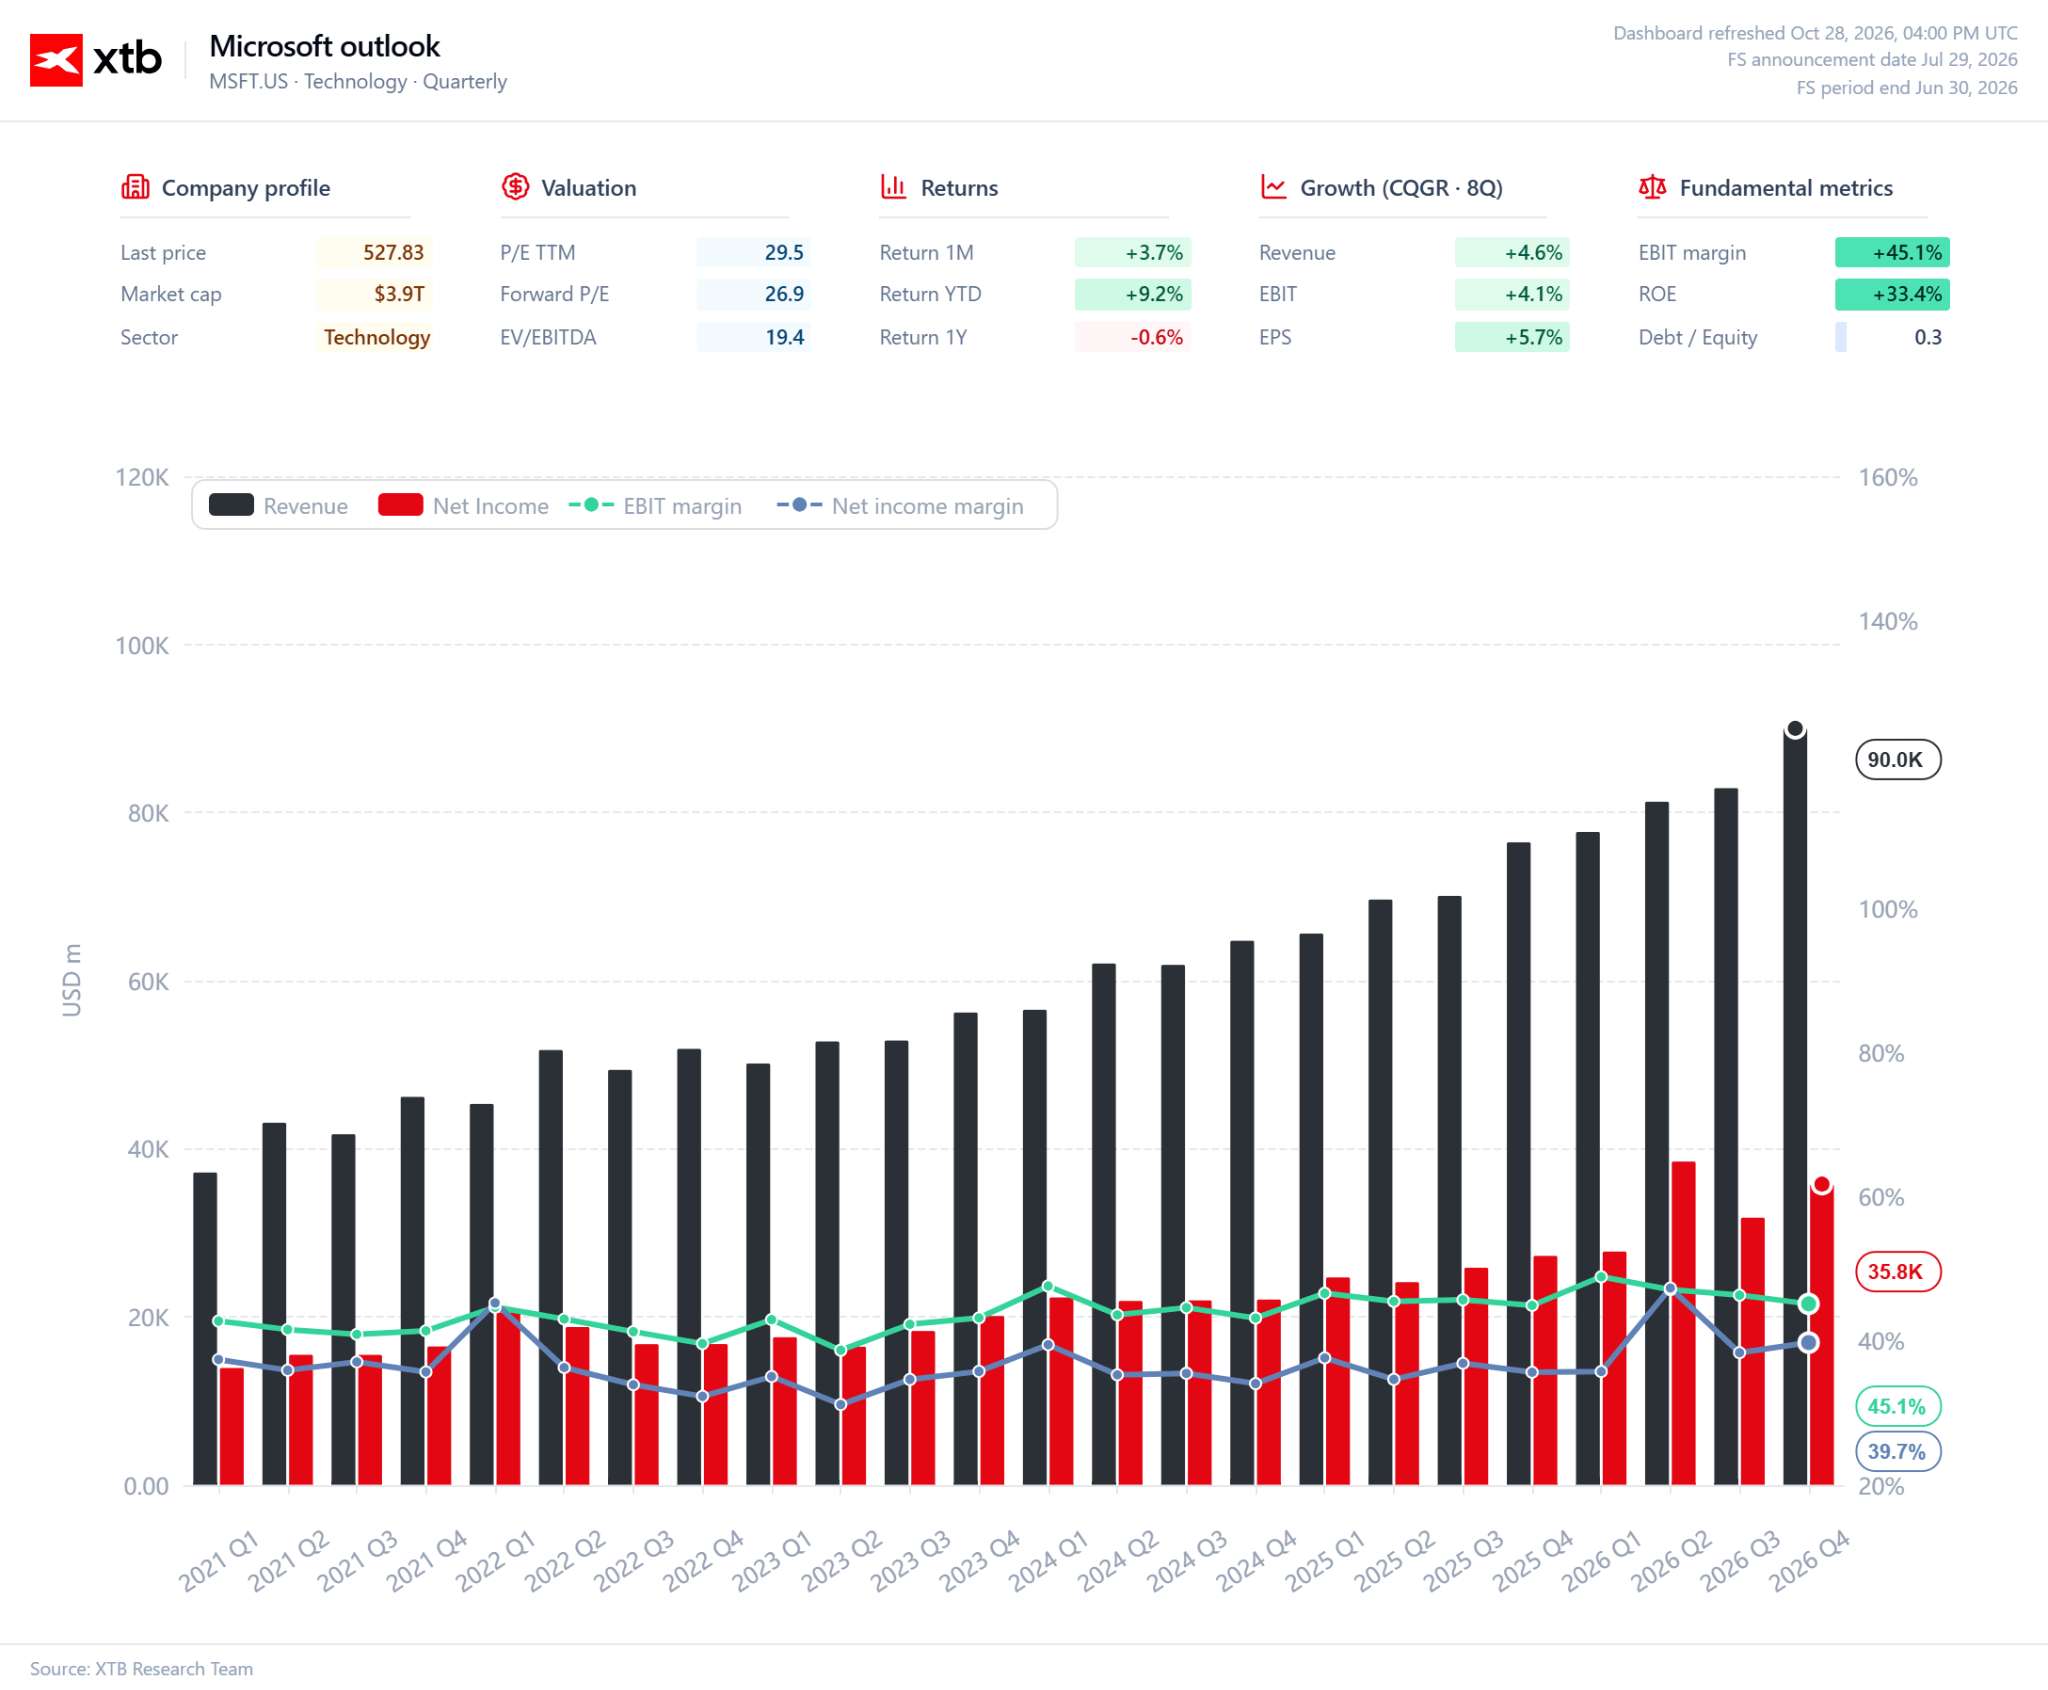
Microsoft approaches its financial report as a primary indicator of corporate AI demand, striving to combine massive investments with strong cost discipline. The company is doing very well in terms of price position, but at the same time near-record highs threaten a potential sell-off if the market is dissatisfied with AI adoption. The company also presents very similar CAPEX outlays as Alphabet.
Market expectations and key metrics:
- Earnings per share and revenue: Consensus predicts EPS at $4.72–4.73 on revenue of $90.6–90.7 billion (+17% YoY).
- Azure Cloud: The company's official forecast assumes a 44–45% growth, but unofficial expectations reach 47–47.7% YoY.
- Expenditures and cash flows: CapEx for fiscal year 2027 is expected to exceed $190 billion (+65% YoY), while FCF is projected to fall below $32 billion (compared to $67 billion a year earlier).
- Cost discipline: A voluntary departure program for 60,000 employees is expected to bring around $1.2 billion in annual savings.
- Valuation and forecasts: Post-earnings stock move is estimated below 5%. Average price target stands at $604 (68 buy recommendations, 4 neutral, 0 sell).
Commentary:
The bar for Microsoft is set very high, and the market expects forecasts to be beaten in the Azure cloud segment. Combining record investments with planned operational savings builds investor confidence, keeping the stock price near historic highs and positioning the company as a leader in commercializing AI-based solutions.
Common Denominator
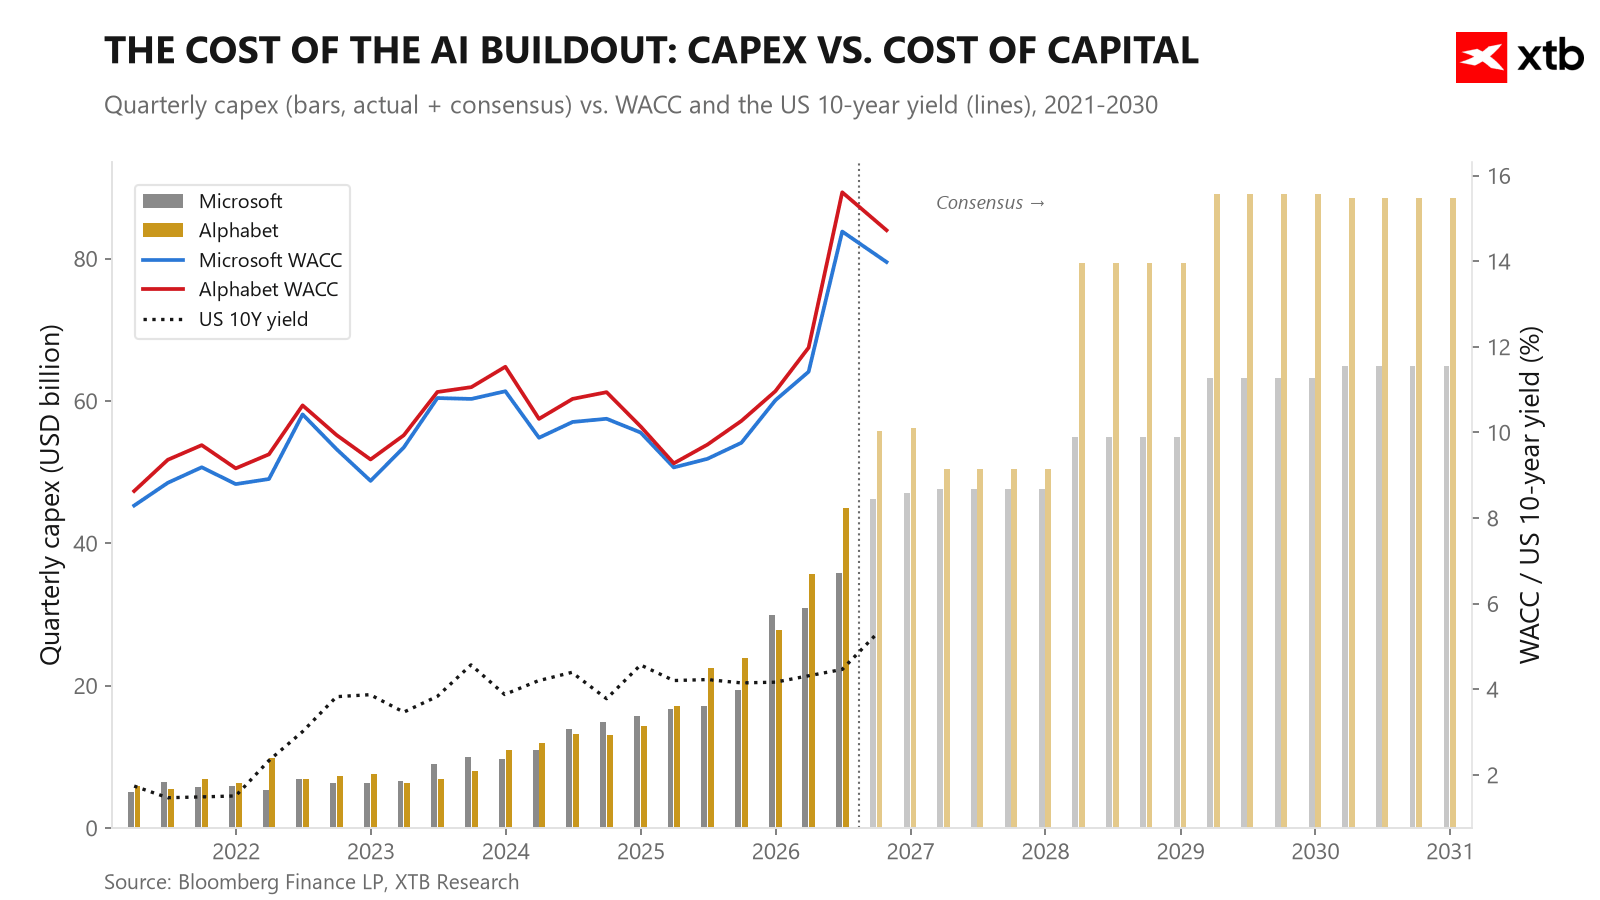
Both reports boil down to one question: whether hyperscalers' massive spending on AI infrastructure, totaling over $390 billion in 2026–2027, is starting to translate into sustainable cash generation.
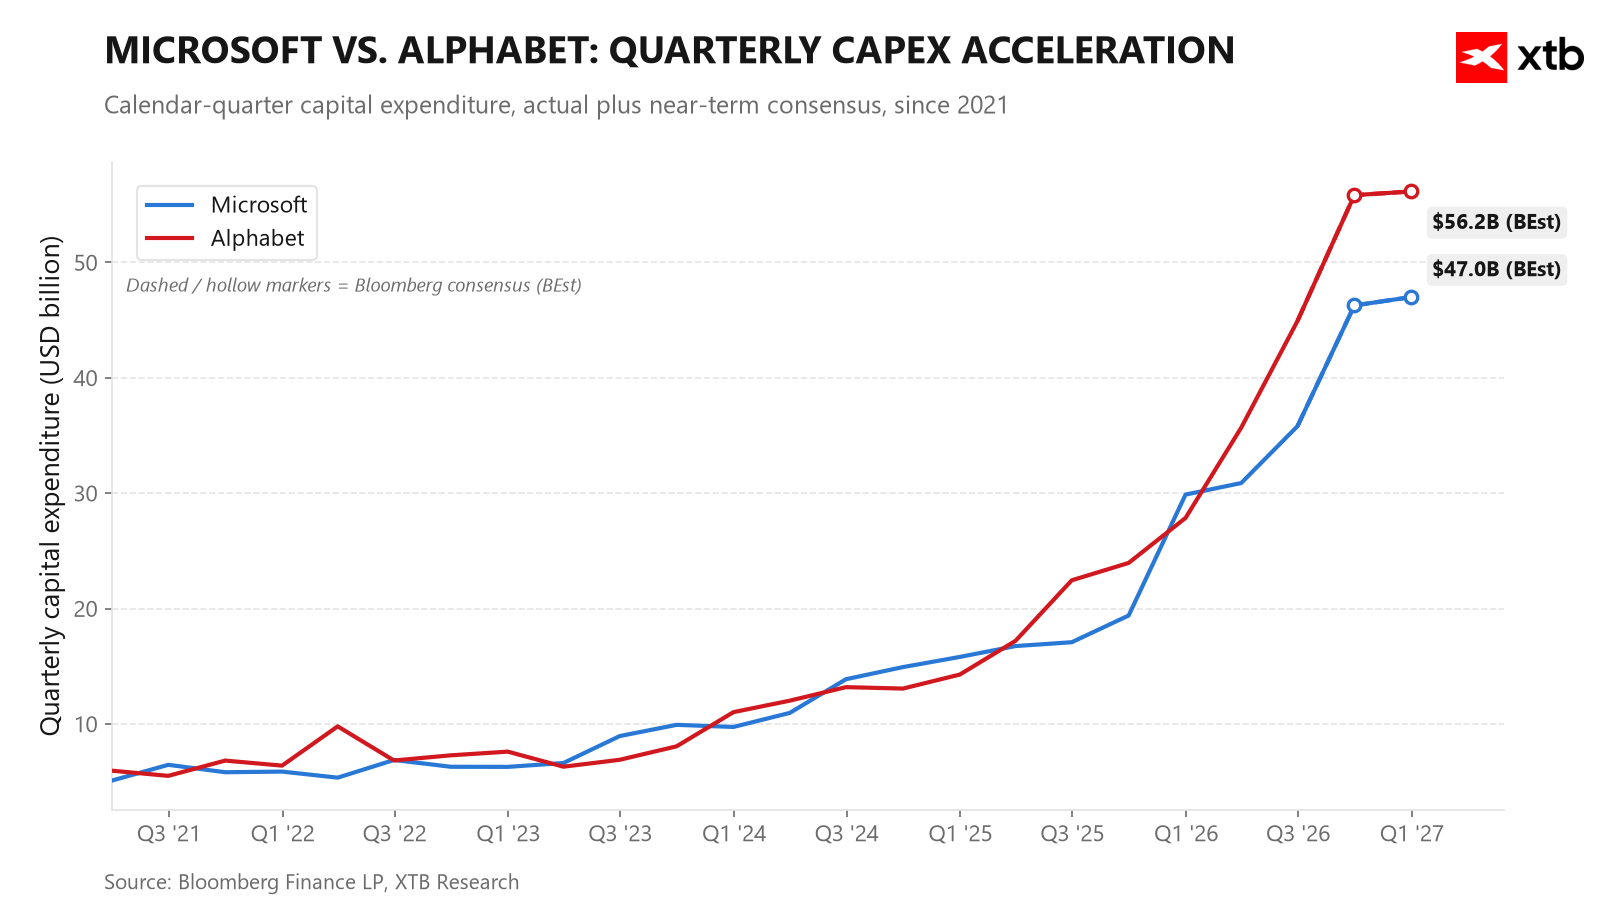
The market has already rewarded Microsoft's discipline (stock up 36 percent since July results) and penalized Alphabet for shifting to negative cash flows (minus 5 percent over the same period), even though Alphabet records faster growth in the cloud. A weak Azure print or disappointing Google search results could reignite concerns that AI spending is not yielding sufficient returns, much like what happened with Meta Platforms, whose stock dropped 7 percent the day after reporting earnings last week.
There is also increasing talk that high US bond yields are partly a result of hyperscalers seeking capital more broadly in the debt market. As can be seen, the current year is just a foretaste of how massive spending is set to be presented in subsequent years.



Market Wrap: Renewed confidence in AI drives stock market recovery (27.10.2026)



📈Daily Summary: Falling Oil Prices and Anthropic Prospectus Drive Markets


US OPEN: Anthropic filing and Iran talks support the market
Anthropic files prospectus ahead of IPO with "ANT" ticker on Nasdaq. The launch date and price remain a mystery
This content has been created by XTB S.A. This service is provided by XTB S.A., with its registered office in Warsaw, at Prosta 67, 00-838 Warsaw, Poland, entered in the register of entrepreneurs of the National Court Register (Krajowy Rejestr Sądowy) conducted by District Court for the Capital City of Warsaw, XII Commercial Division of the National Court Register under KRS number 0000217580, REGON number 015803782 and Tax Identification Number (NIP) 527-24-43-955, with the fully paid up share capital in the amount of PLN 5.869.181,75. XTB S.A. conducts brokerage activities on the basis of the license granted by Polish Securities and Exchange Commission on 8th November 2005 No. DDM-M-4021-57-1/2005 and is supervised by Polish Supervision Authority.