


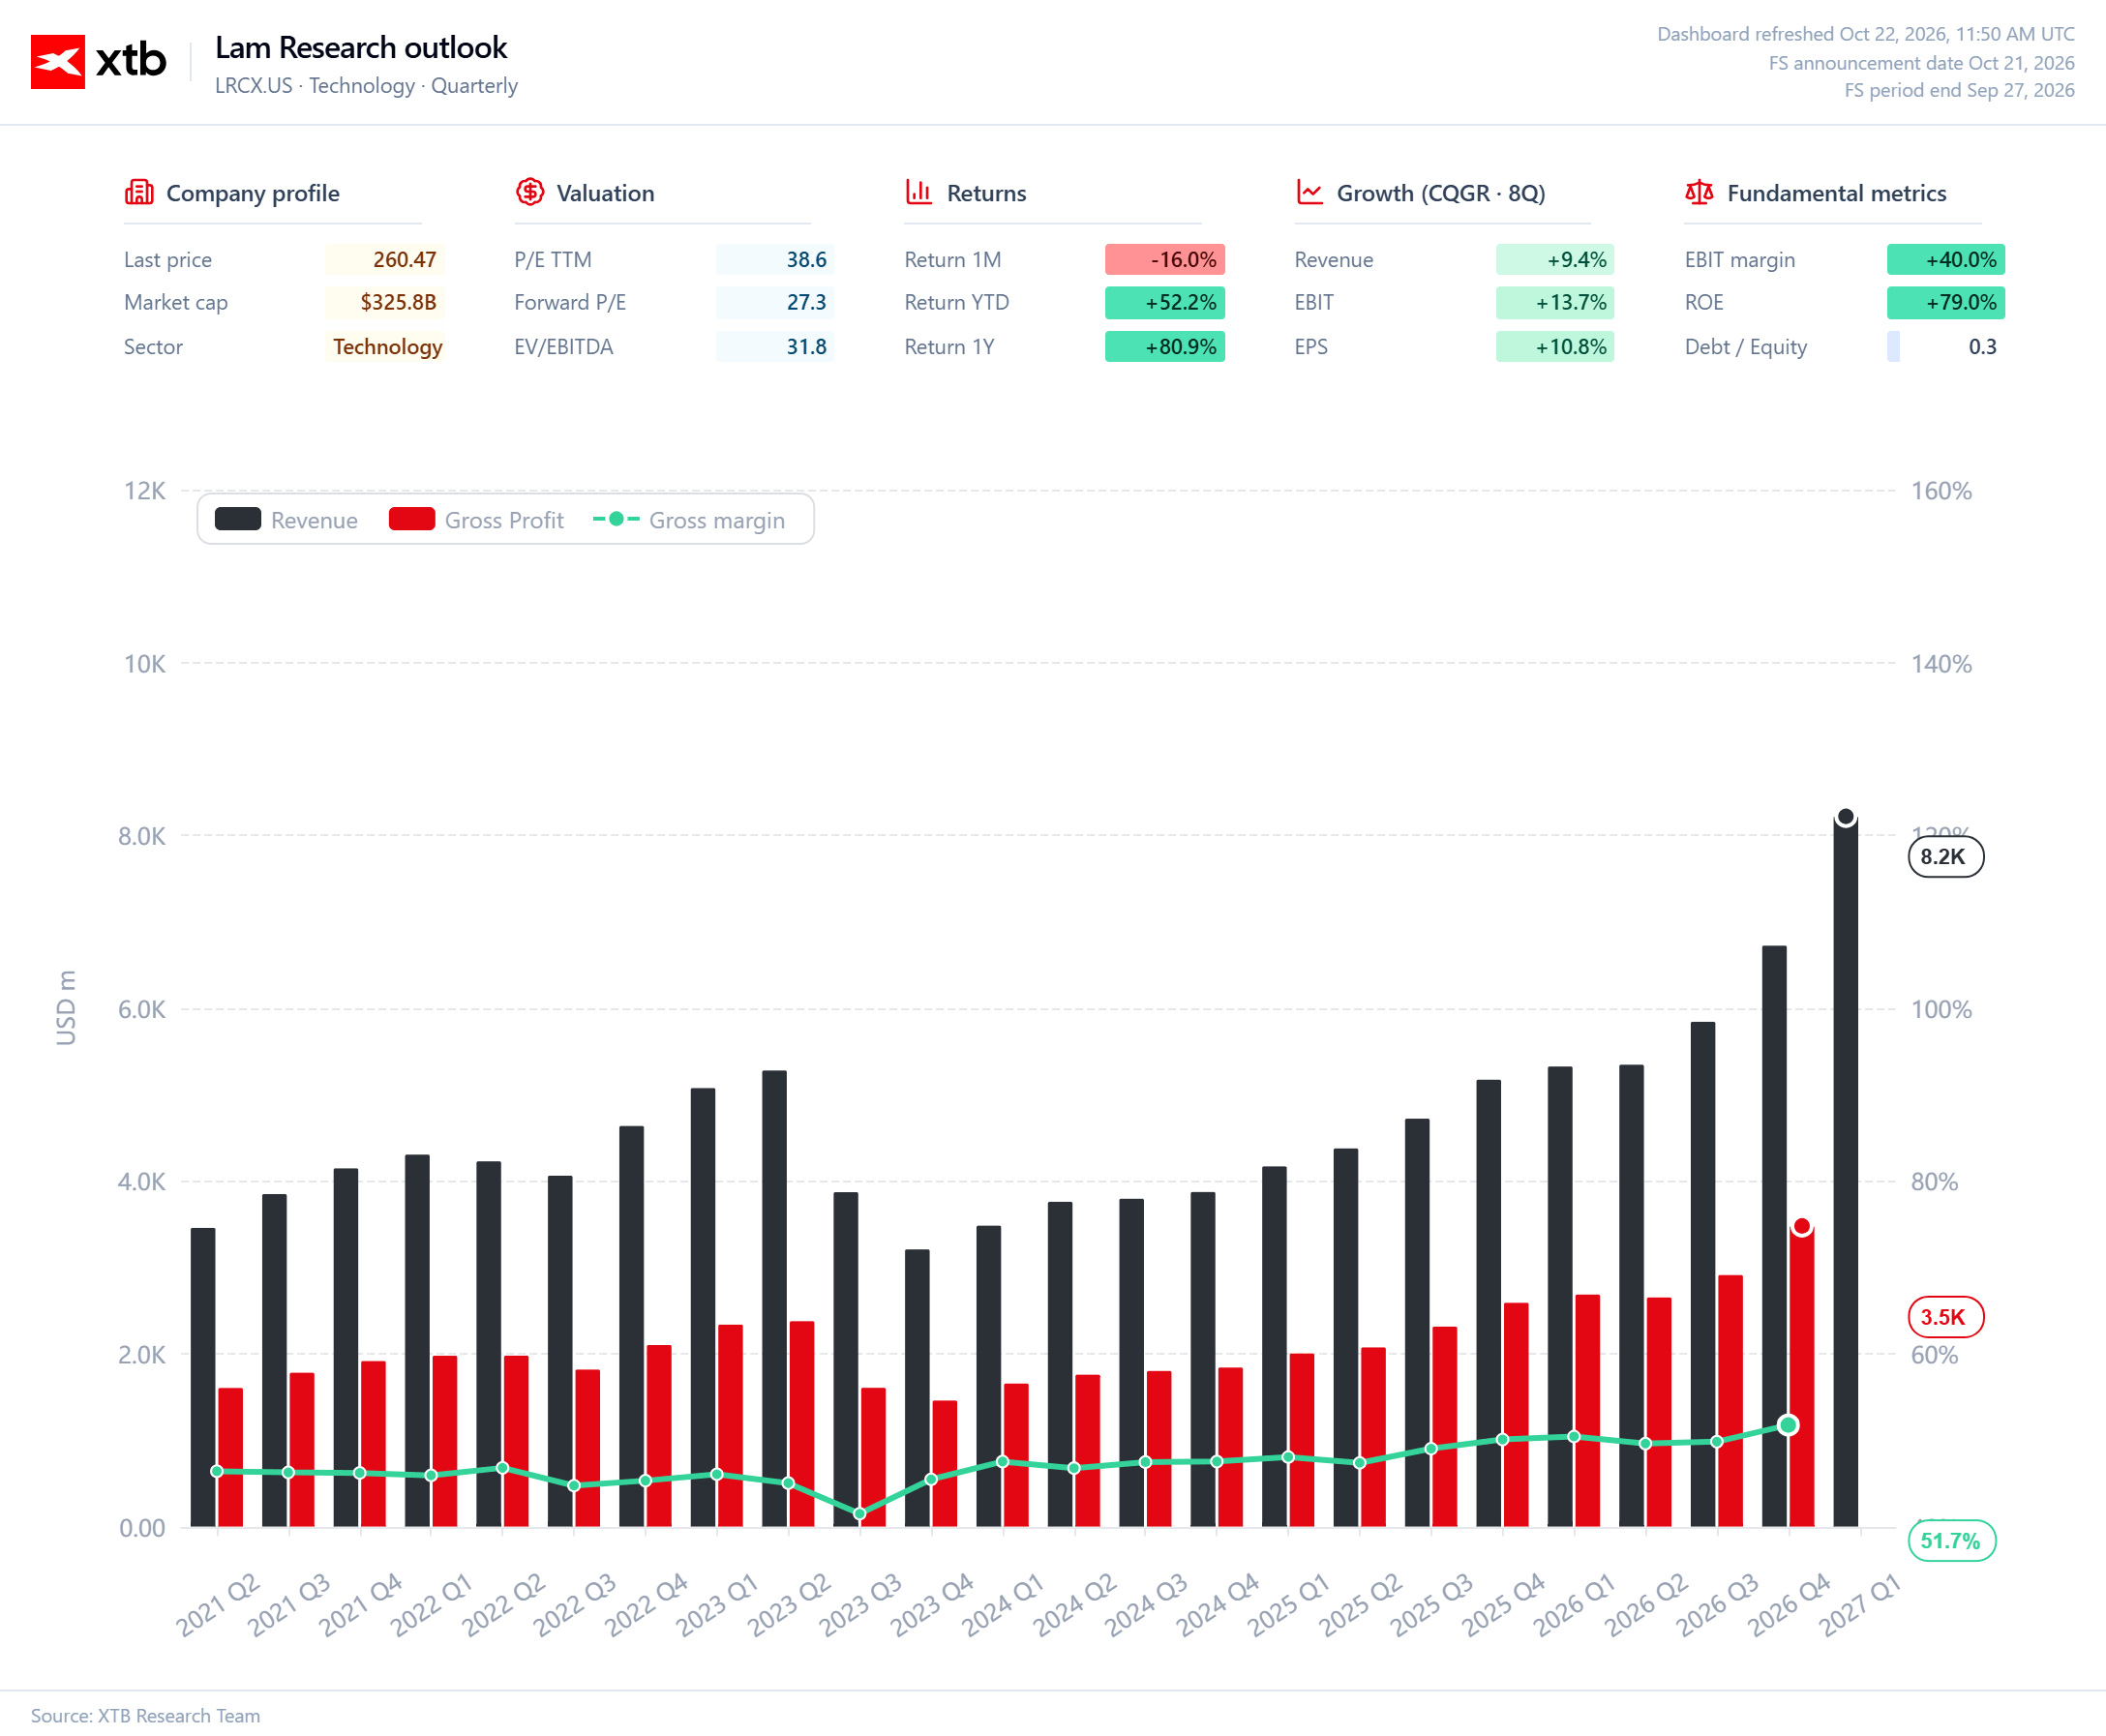
Lam Research delivered solid results, but investors were looking for more. Revenue and earnings per share came in above consensus, margins improved, and the company’s guidance for the next quarter also exceeded expectations. The problem was the relatively small size of these beats. After a strong rally in the stock, the market wanted clearer evidence that the semiconductor industry’s investment boom would translate into even stronger results for the company.
Key figures:
-
Revenue: $8.22 billion, up 54% year over year, versus consensus of approximately $8.14 billion.
-
Adjusted EPS: $2.20 versus expectations of $2.18.
-
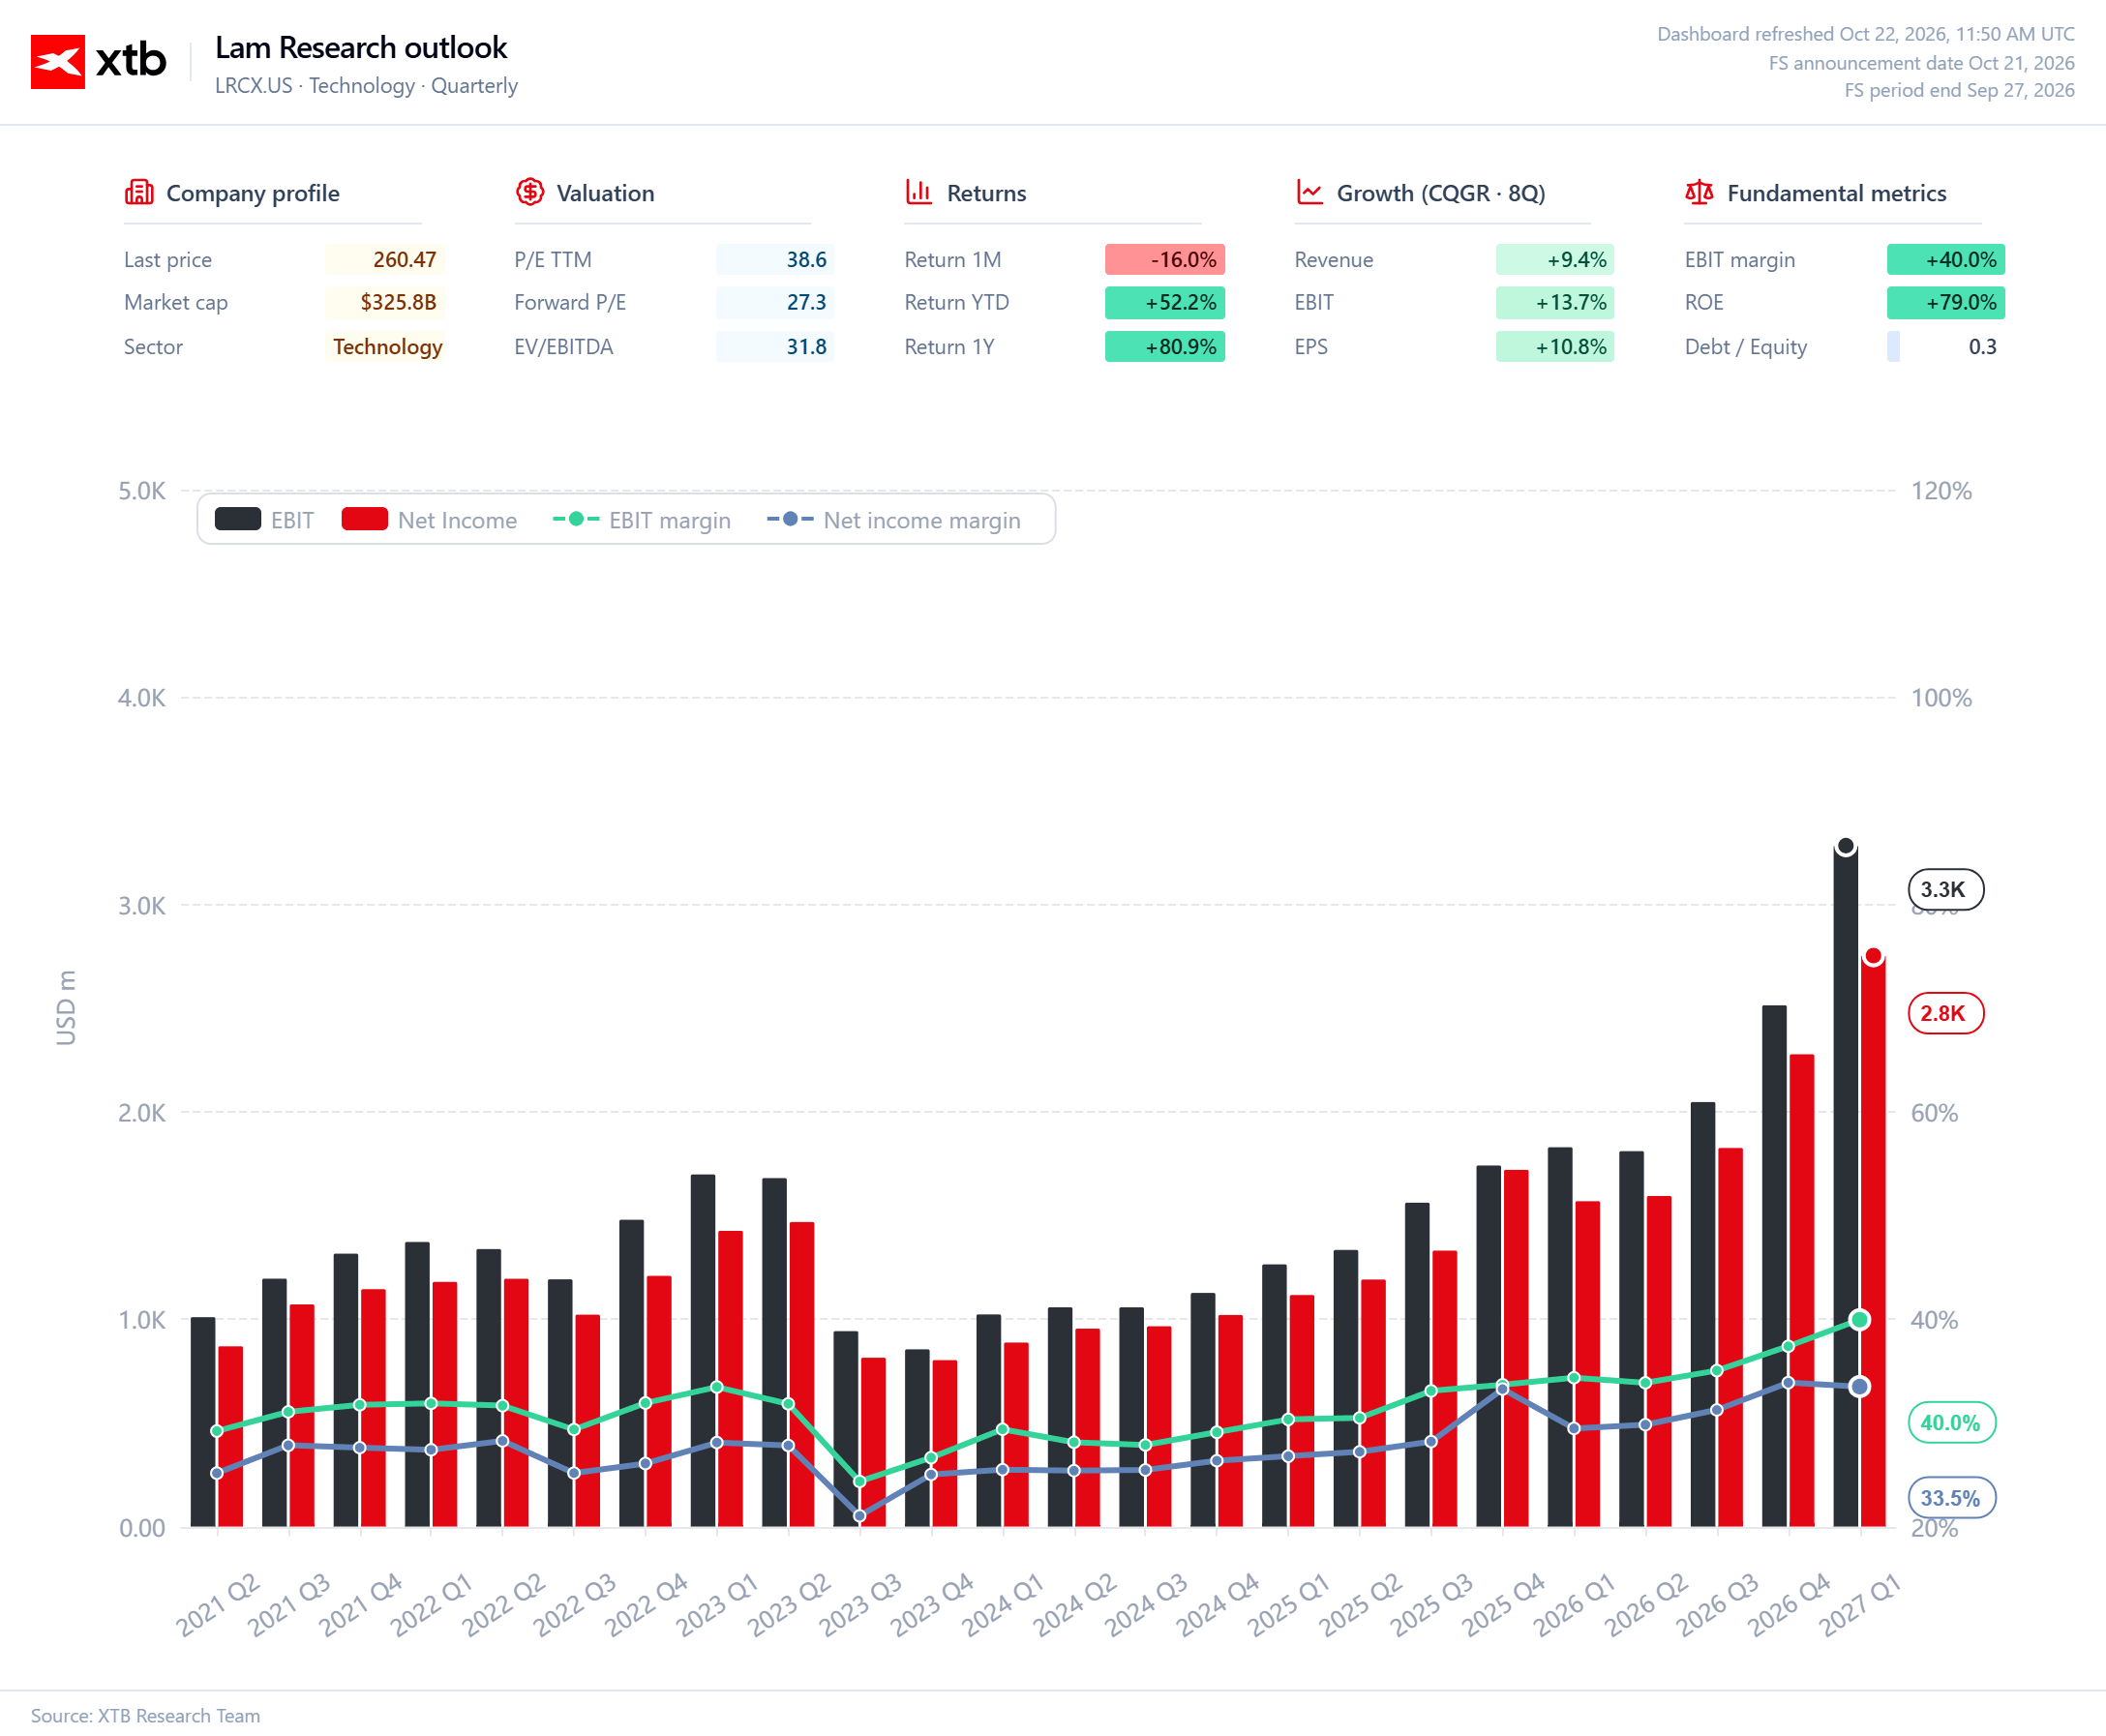
Operating margin: A record 40.2%.
-
Next-quarter revenue guidance: $8.6 billion versus consensus of approximately $8.53 billion.
-
Next-quarter adjusted EPS guidance: $2.33 versus expectations of approximately $2.31.
-
WFE market: Lam estimates the market will be worth approximately $150 billion in 2026 and more than $200 billion in 2027.
The operating performance was strong. Revenue increased 22% quarter over quarter, while the company improved profitability as its business expanded. Even so, with quarterly sales exceeding $8 billion, an $80 million revenue beat and an EPS result just two cents above consensus are hardly major surprises. The market wanted stronger evidence that Lam could capitalize on current demand more effectively than previously expected.
The outlook for the next quarter offers some reassurance. Lam expects revenue of $8.6 billion and adjusted EPS of $2.33. Both figures are above consensus, but the gap remains narrow. The guidance confirms that growth is continuing, although it provides little reason to raise expectations significantly.
Supply constraints are also worth watching. Management acknowledged that revenue could have been higher if certain components had been more readily available. Some deliveries scheduled for the next quarter may also be pushed back to a later period. The issue may therefore be less about a lack of orders and more about suppliers’ ability to fulfill them on time. However, the company has not disclosed the potential scale of these delays, making it difficult to assess their impact on upcoming results.
The broader industry outlook remains very strong. Lam expects the global WFE market, or Wafer Fab Equipment, to reach approximately $150 billion in 2026 and exceed $200 billion in 2027. WFE includes equipment used in semiconductor fabrication facilities, including etch and deposition systems, which are important parts of Lam Research’s product portfolio. These figures refer to the entire market, not Lam’s own revenue.
Growth is being driven by investment in advanced logic chips and memory, with demand further supported by the expansion of artificial intelligence. Lam is benefiting directly from this trend. In the latest quarter, revenue from systems used to manufacture memory chips increased by approximately 120% year over year, accounting for 46% of the company’s systems revenue.
Risks remain, however. Management expects China’s share of revenue to decline in the next quarter, while limited component availability could continue to hamper order fulfillment.
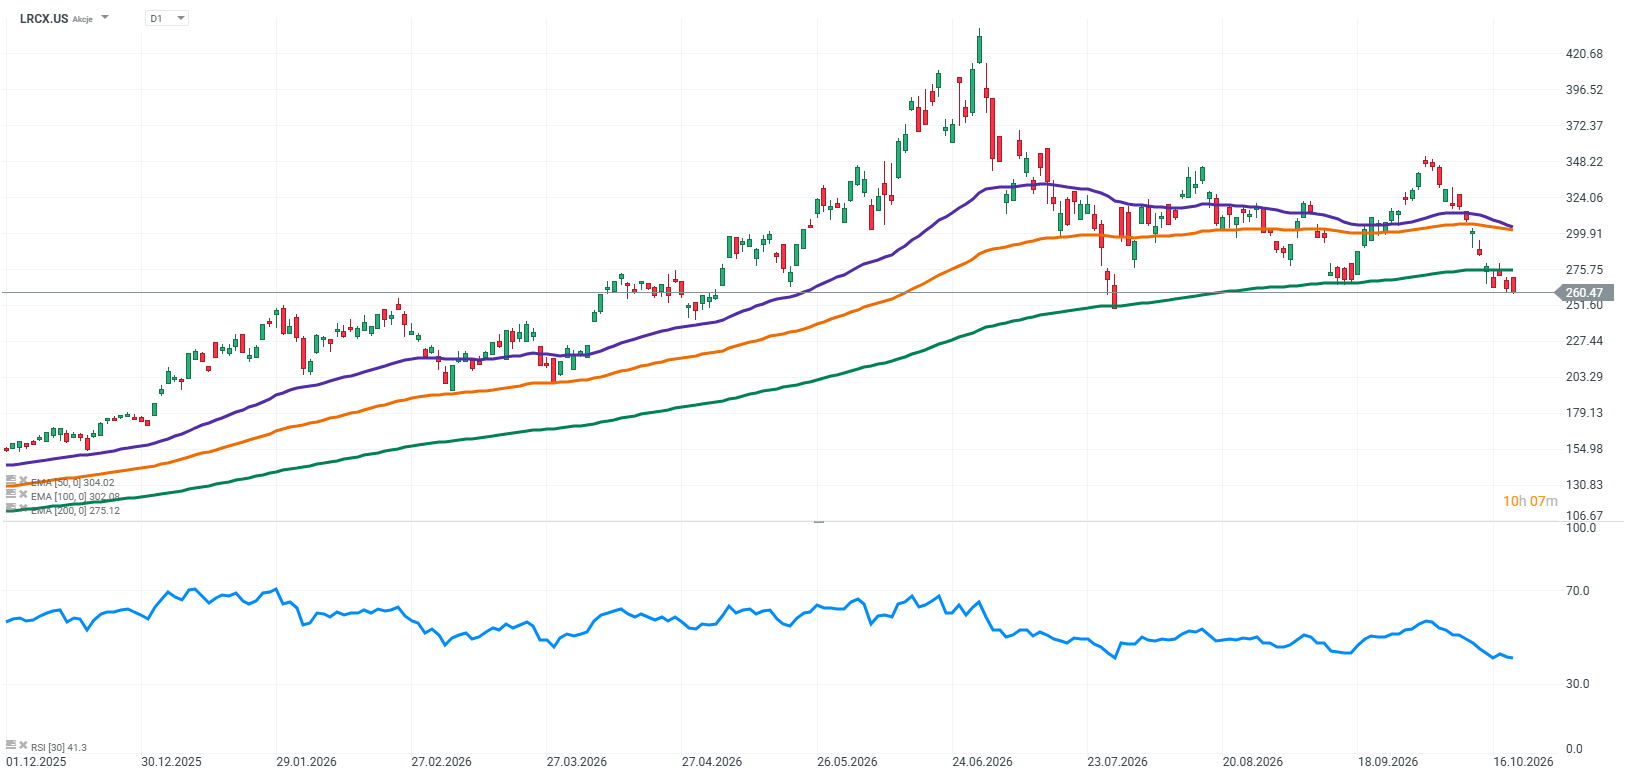
Lam remains a clear beneficiary of rising investment in semiconductor manufacturing, but this time its results failed to impress investors with the size of the earnings beat. Better-than-expected guidance and the disclosure of supply constraints provide some context, but investors are still waiting for a stronger catalyst to justify raising expectations for the company further.
Source: XTB Research


US100 drops 1.8% 🚨


Tesla was supposed to burn $5 billion, but posted a positive result. Will Tesla still be a car company in a year?

Record-breaking Meta, though with a cash loss. Investors (for now) are buying Zuckerberg's plan anyway


US OPEN: Preparations for Tesla's mega-merger with SpaceX. Diplomatic stalemate with Iran cools Wall Street's enthusiasm
This content has been created by XTB S.A. This service is provided by XTB S.A., with its registered office in Warsaw, at Prosta 67, 00-838 Warsaw, Poland, entered in the register of entrepreneurs of the National Court Register (Krajowy Rejestr Sądowy) conducted by District Court for the Capital City of Warsaw, XII Commercial Division of the National Court Register under KRS number 0000217580, REGON number 015803782 and Tax Identification Number (NIP) 527-24-43-955, with the fully paid up share capital in the amount of PLN 5.869.181,75. XTB S.A. conducts brokerage activities on the basis of the license granted by Polish Securities and Exchange Commission on 8th November 2005 No. DDM-M-4021-57-1/2005 and is supervised by Polish Supervision Authority.