


Monday’s session on European stock exchanges is dominated by selling. Declines are led primarily by French stocks and indices. The CAC 40 was down by around 1.4%. The German and UK indices are limiting losses to about 1%. EU50 futures are down only about 0.25%.
The European market is weighed down mainly by political instability in France, worsening sentiment toward the banking sector, and persistent uncertainty around technology company valuations.
A clear divergence between Europe and the US is also visible in after-hours trading, with the US market performing noticeably better than Europe.
- Protests in France have triggered another wave of concern about the political and fiscal stability of the eurozone’s second-largest economy. Nearly 2,400 people were detained during weekend demonstrations, and rising tensions are further complicating work on the state budget. Investors are responding by selling both equities and bonds. The yield on French 10-year debt rose toward 4.86%, increasing the risk premium versus German Bunds. French banks are among the hardest hit. Another source of uncertainty in Europe remains the political situation in Spain, which is preparing for snap elections.
- After an exceptionally weak week for US technology companies, investors are increasingly questioning the sustainability of gains driven by investment in artificial intelligence. The Philadelphia Semiconductor Index ended Friday’s session down about 4%, extending its losing streak to eight sessions, the longest since 2008. At the same time, Goldman Sachs data point to a clear reduction in hedge fund exposure to AI, from nearly 32% in June to 26% currently. Credit risk among entities financing computing infrastructure is also becoming more important, as the cost of insuring CoreWeave bonds against default has exceeded 1,000 basis points.
- Brent crude prices were down about 2% on Monday, but as the US session approaches, prices are recovering losses. Prices are reacting mainly to reports of a partial easing of certain US restrictions on Russian energy exports. Potentially greater availability of Russian commodities could partially reduce pressure on global supply, although transport conditions in the Persian Gulf remain a serious threat to global trade. Disruptions in the Strait of Hormuz are now affecting not only tankers but also vessels carrying commercial cargo. According to Bloomberg, the daily rate indicator for the largest tankers on the Middle East to China route reached $1.37 million, more than six times higher than before the war began.
Company News
- DHL Group (DHL.DE): The German logistics operator raised its 2026 operating profit (EBIT) forecast to more than EUR 7 billion, from a prior forecast of more than EUR 6.5 billion. The change is supported by improved performance and the prospect of a stronger year-end season. The stock is down about 2%.
- EQT (EQT.SE): The Swedish private equity group agreed to acquire Australia’s Cleanaway Waste Management for about AUD 9.3 billion, including debt. The target’s shares rose as much as 21% in Sydney. The deal increases EQT’s exposure to the waste management sector. EQT shares are up about 3%.
- Mowi (MOWI.NO): The Norwegian salmon producer reported a record harvest volume in Q3 of about 186,000 tonnes. The stock gained about 3.8%, standing out positively against a declining market.
- Rheinmetall (RHM.DE): The German defense group took a small stake in Rock Tech Lithium and its German lithium processing project. The investment may be part of securing strategic raw-material supply chains for the defense industry. However, investors are expressing concerns about the resilience of the company’s margins, and the stock is under pressure.
- Euronext (ENX.FR): The stock is up about 1% following a positive publication from Citibank. The bank’s analysts point to the company’s advantages in clearing and in solutions for the debt instruments market.
Technical Analysis: DE40 (D1)
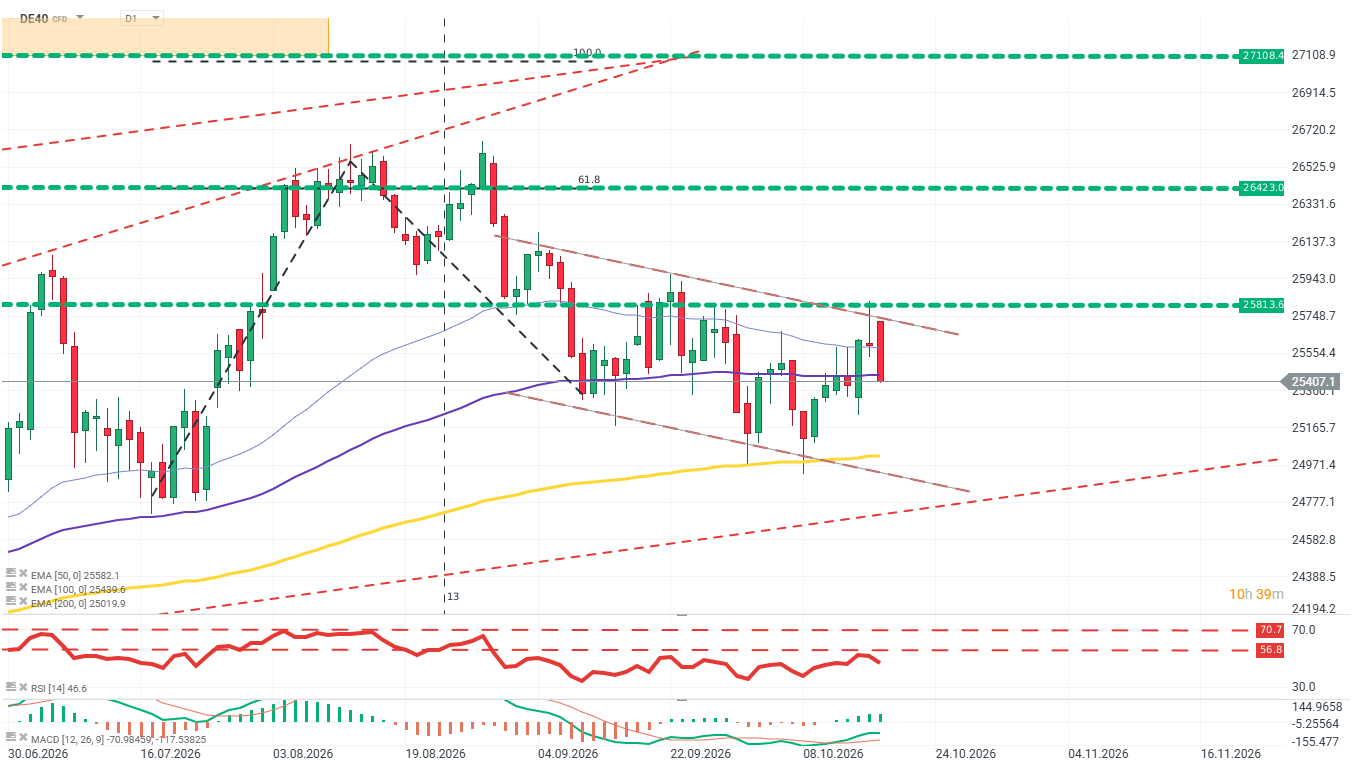
The latest strong red candle shows a rejection from the descending resistance line. The market remains in a downward correction, although the long-term uptrend has not been invalidated. Source: xStation5
Forex
- Pressure on European assets is also visible in the currency market, where EUR/USD has fallen toward 1.12.
Macroeconomic Data
- China’s economy grew by 4.5% year on year in Q3, beating the 4.4% consensus and accelerating from 4.3% in the previous quarter.
- Ahead of the market is the release of Canada’s September CPI inflation. The consensus for annual inflation is about 3.2%, versus 3.0% a month earlier. The data will be important for expectations regarding the Bank of Canada’s next decisions.



Chart of the Day: What’s next for tech stocks after the deepest sell-off since April 2025? (19.10.2026)


Optimism Returns to Asia❔


Economic Calendar: Big tech earnings week and test for the AI rally (19.10.2026)

Morning Wrap: Nasdaq rebounds ahead of Mag7 earnings, bonds regain favour, oil falls from peak (19.10.2026)
This content has been created by XTB S.A. This service is provided by XTB S.A., with its registered office in Warsaw, at Prosta 67, 00-838 Warsaw, Poland, entered in the register of entrepreneurs of the National Court Register (Krajowy Rejestr Sądowy) conducted by District Court for the Capital City of Warsaw, XII Commercial Division of the National Court Register under KRS number 0000217580, REGON number 015803782 and Tax Identification Number (NIP) 527-24-43-955, with the fully paid up share capital in the amount of PLN 5.869.181,75. XTB S.A. conducts brokerage activities on the basis of the license granted by Polish Securities and Exchange Commission on 8th November 2005 No. DDM-M-4021-57-1/2005 and is supervised by Polish Supervision Authority.