


Wall Street futures are trading around 0.2% lower, Asian indices are down roughly 0.6%, while European equity futures point to the possibility of further losses at the open. U.S.-Iran talks held in New York failed to deliver the expected breakthrough, while bond yields are rising again.
- Iranian President Masoud Pezeshkian said Tehran would not allow freedom of navigation through the Strait of Hormuz as long as sanctions and the U.S. blockade remain in place. His comments underline how difficult it remains to reach a peace agreement despite efforts to revive negotiations, while the risk of disruptions to oil and energy-product flows remains significant.
- The global bond selloff is deepening after the strongest U.S. PMI data since 2021 and weak demand at a five-year Treasury auction. The U.S. 10-year yield is holding near 5.11% after Wednesday’s 15 bp surge, the largest increase since the market turmoil following Trump’s April 2025 tariff announcement.
- The pressure has spread across Asia-Pacific markets. Bonds sold off in Japan, Australia and New Zealand, while emerging-market debt also weakened. The average yield on global government debt has moved close to 4%.
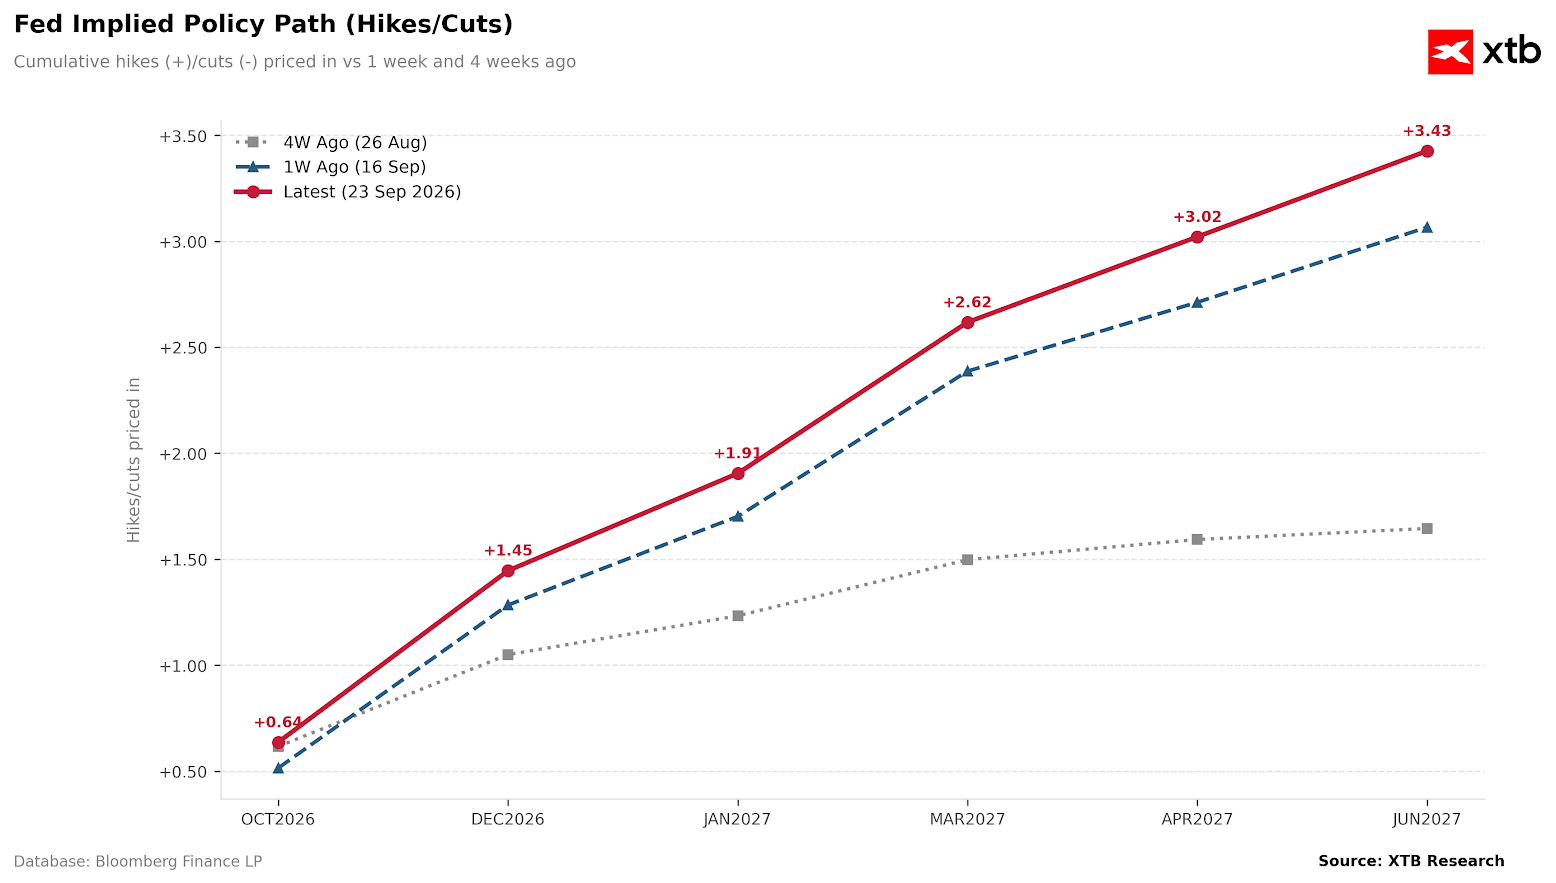
- Investors are increasing bets on further Fed tightening following last week’s first rate hike since 2023. Money markets are now fully pricing in two additional rate hikes over the next three Fed meetings.
- Fed Governor Michael Barr said yesterday that further monetary tightening will likely be needed to bring inflation back toward the 2% target.
- Higher yields and expectations of further rate hikes remain the main source of pressure on risk assets, including Bitcoin, which has pulled back to around $84,000.
- Oil is giving back part of its recent gains. After the contract rollover, Brent opened near $97 per barrel. Gold remains under pressure after yesterday’s 1.7% decline and is trading close to $4,290 per ounce. Higher interest rates and bond yields are reducing the relative appeal of precious metals.
- Mainland Chinese equities are down more than 1%, despite Treasury Secretary Scott Bessent saying the U.S. and China agreed to extend their trade truce by another two months.
- Xi Jinping has arrived in Washington for his first U.S. state visit in 11 years, focusing market attention on trade relations and possible agreements between Beijing and the Trump administration.
- The Trump administration is working with refiners on voluntary restrictions on fuel exports aimed at reducing overseas shipments and increasing domestic supply, although LSGASOIL diesel futures remain broadly stable after the rollover.
- Australia’s unemployment rate rose to 4.6% from 4.5%, above the 4.5% consensus forecast. Employment nevertheless increased by 39.5k, well above the expected 20k and compared with a 15.8k decline previously, while the participation rate rose to 67.1% from 66.9%.
- Today the Swiss National Bank is set to announce its policy decision, followed by Sweden’s Riksbank. Both central banks are expected to leave interest rates unchanged. Germany’s Ifo business sentiment data will be released at 8 AM GMT, while at 12:30 PM GMT markets will receive U.S. jobless claims and Canadian retail sales.
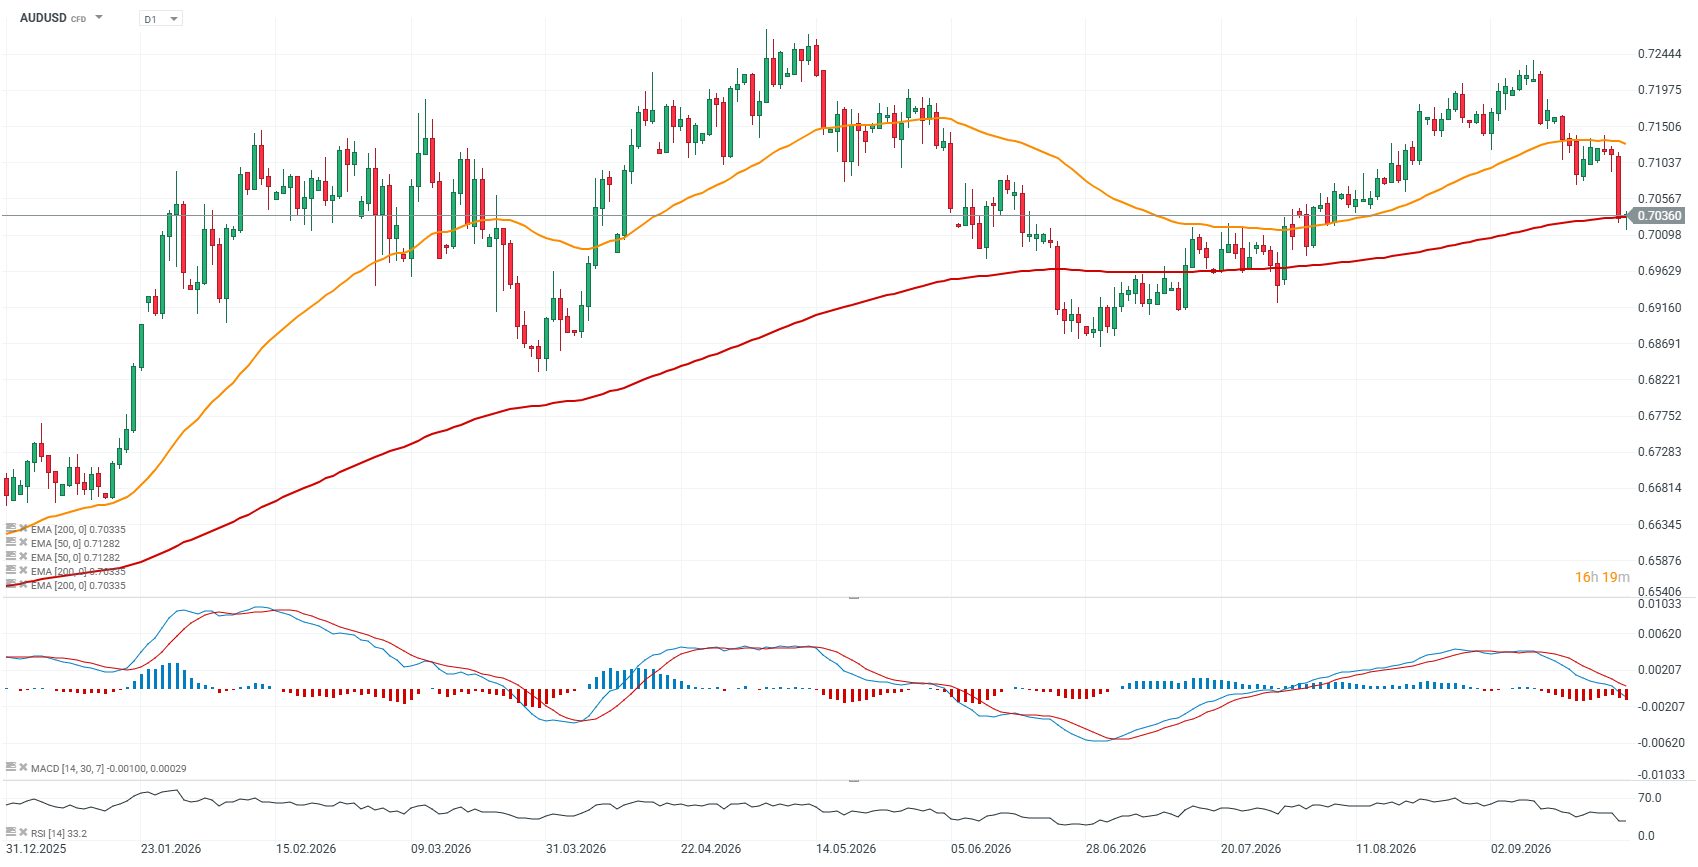
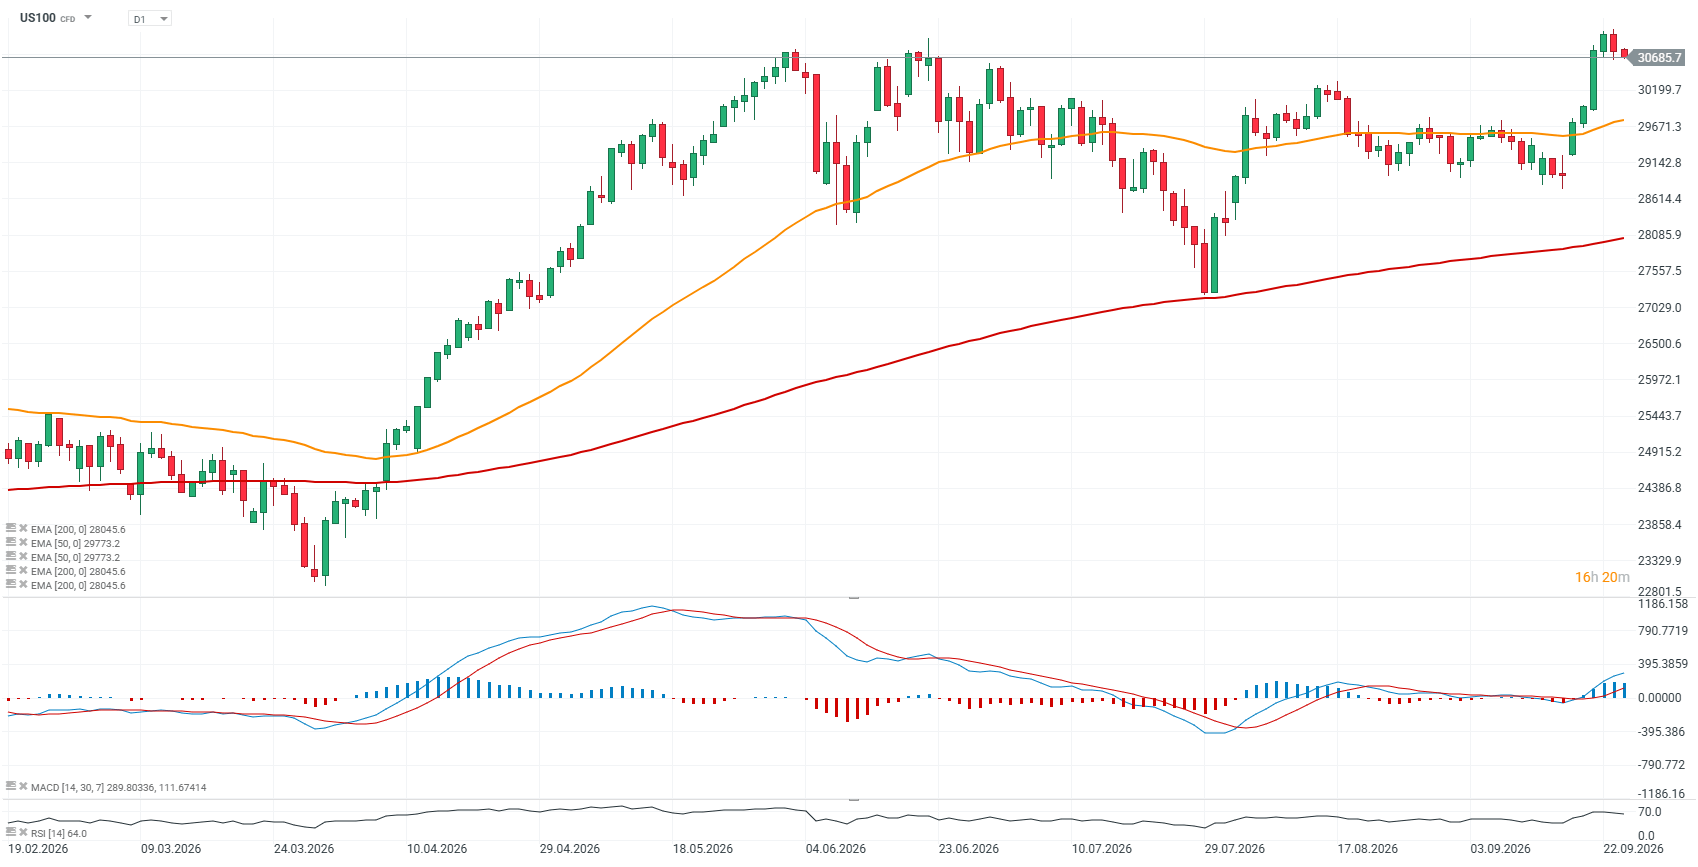
AUDUSD, US100 charts (D1 timeframe)
Despite mixed Australian labor-market data, with unemployment rising alongside a strong increase in employment, AUDUSD is attempting to recover losses and is testing its 200-day exponential moving average, EMA200 (red line), as it tries to return to an upward trend. The Aussie is strengthening slightly against the U.S. dollar.
 Source: xStation5
The Nasdaq 100 futures contract has posted two consecutive declining sessions but remains above 30,000 points. For now, the move should still be treated as a normal correction within a strong upward trend. Key resistance is located near 30,800 points, and only a break above that level could open the way toward 31,000 points and higher. The 29,700–30,000 area remains an important support zone for bullish momentum.
 Source: xStation5
The market has clearly shifted toward a more hawkish Fed path, pricing in significantly more rate hikes than it did a month ago. By June 2027, futures imply a cumulative total of around 3.4 hikes, compared with roughly 1.6 priced in four weeks earlier. The biggest shift came after the latest Fed meeting and yesterday’s stronger preliminary manufacturing and services PMI readings. These data increased investors’ conviction that U.S. interest rates are likely to remain higher for longer.
 Source: XTB Research



Daily Summary: US dollar reaches new highs, Wall Street, gold and bitcoin fall (23.09.2026)

US Open: Nasdaq drops from the all-time high (23.09.2026)
US PMIs skyrocket to a 5-year high

Market wrap: European indices under pressure from a stronger dollar 🚩 Quantum stocks Gain, IONQ jumps 12%
This content has been created by XTB S.A. This service is provided by XTB S.A., with its registered office in Warsaw, at Prosta 67, 00-838 Warsaw, Poland, entered in the register of entrepreneurs of the National Court Register (Krajowy Rejestr Sądowy) conducted by District Court for the Capital City of Warsaw, XII Commercial Division of the National Court Register under KRS number 0000217580, REGON number 015803782 and Tax Identification Number (NIP) 527-24-43-955, with the fully paid up share capital in the amount of PLN 5.869.181,75. XTB S.A. conducts brokerage activities on the basis of the license granted by Polish Securities and Exchange Commission on 8th November 2005 No. DDM-M-4021-57-1/2005 and is supervised by Polish Supervision Authority.