


Today's reshuffle in the equity market may appear somewhat surprising. Under normal conditions, an increase in interest rates should weigh on the stock market, primarily as a result of rising bond yields.
Yesterday's Fed Meeting
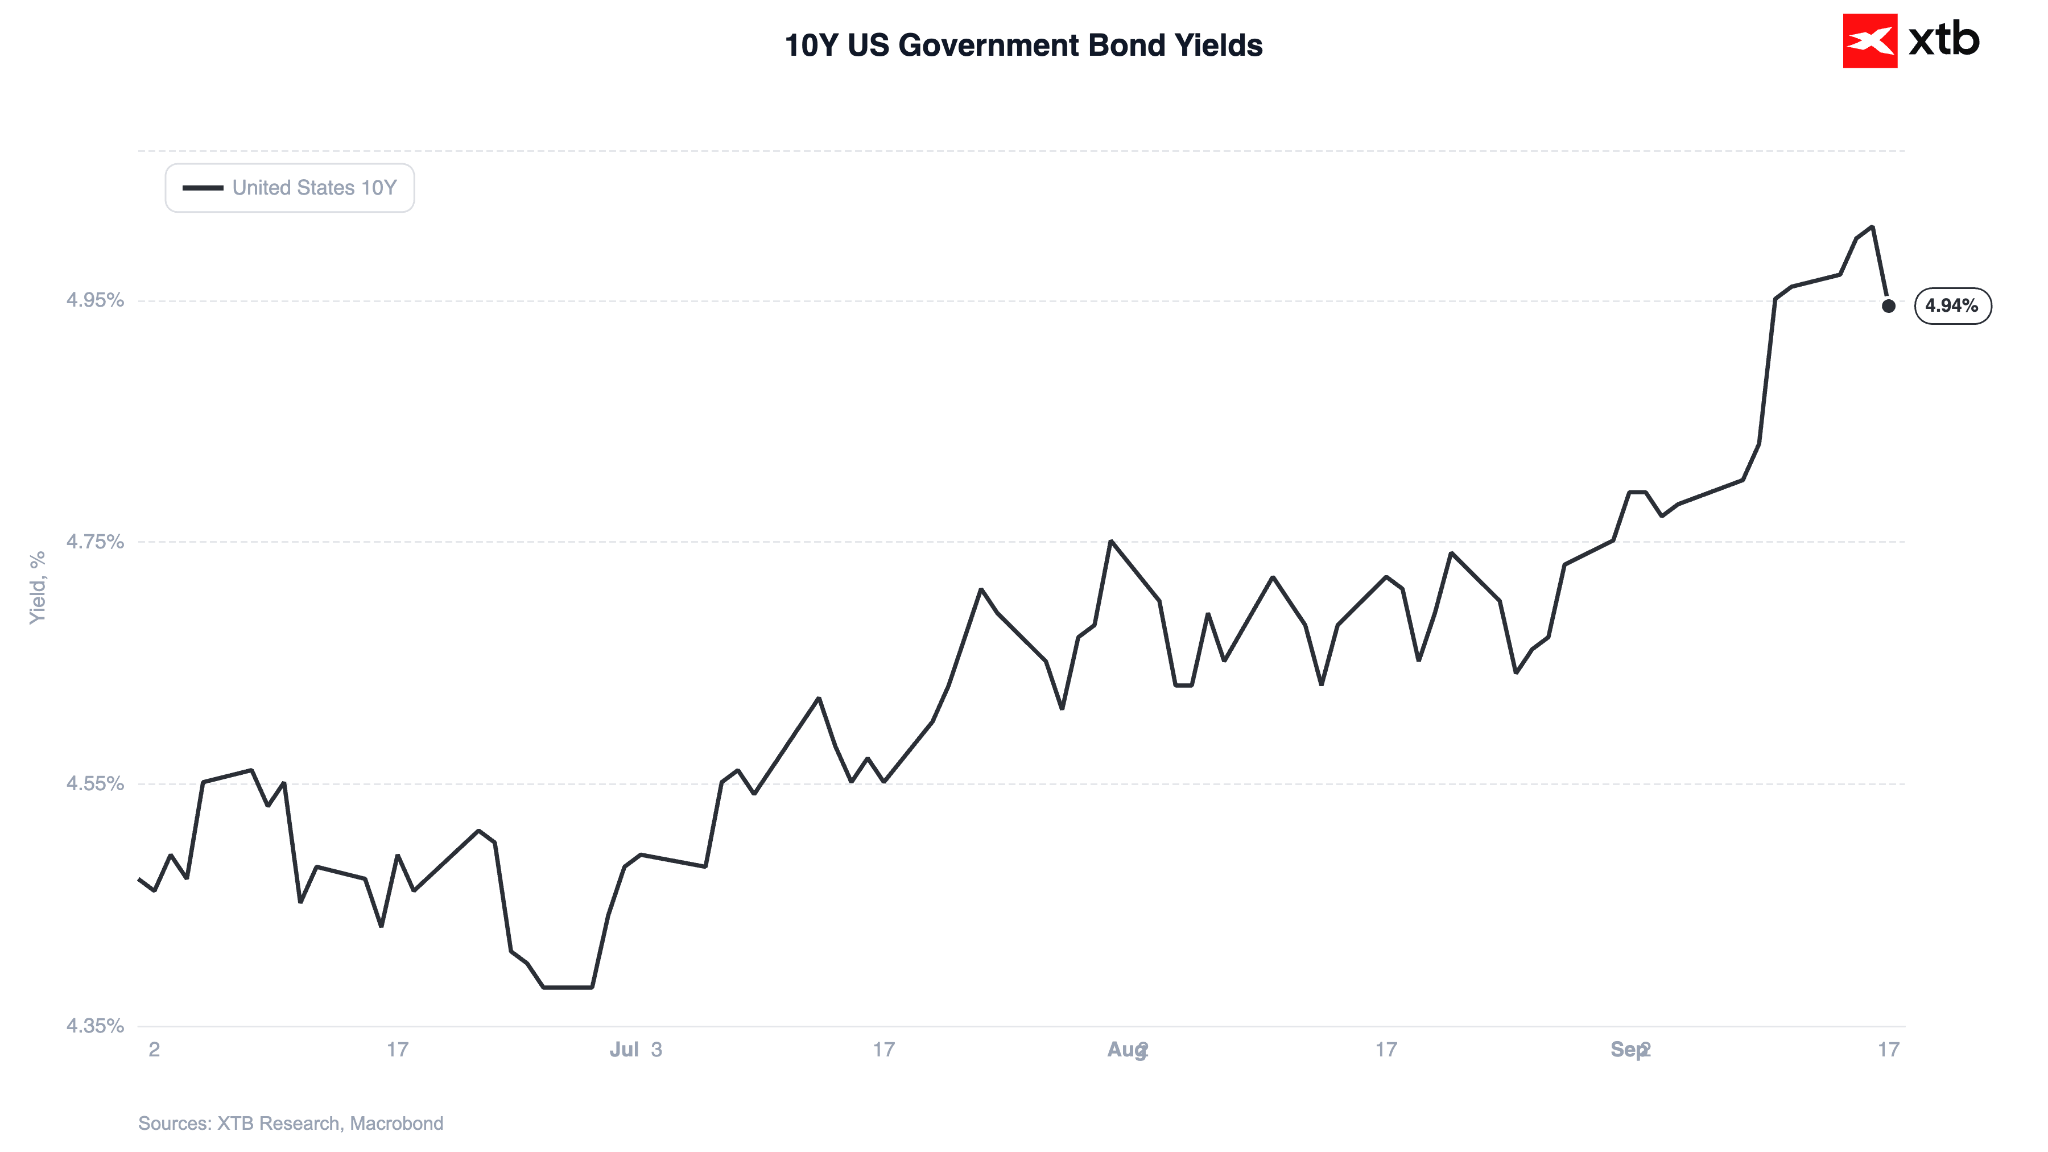
Yields on 10-year US Treasury bonds did indeed rise yesterday, climbing by nearly 1.5%. The primary driver of the move was not the rate hike itself, as the move had been almost fully priced in by the markets, meaning it should already have been reflected in asset prices.
Attention was focused on the Dot Plot, which projects the Fed's interest rate levels for coming years, as well as the rhetoric from Kevin Warsh. The tone of the new Fed Chair's statements was perceived as hawkish, suggesting further rate increases in this context.
Why Are Indices on the Rise Then?
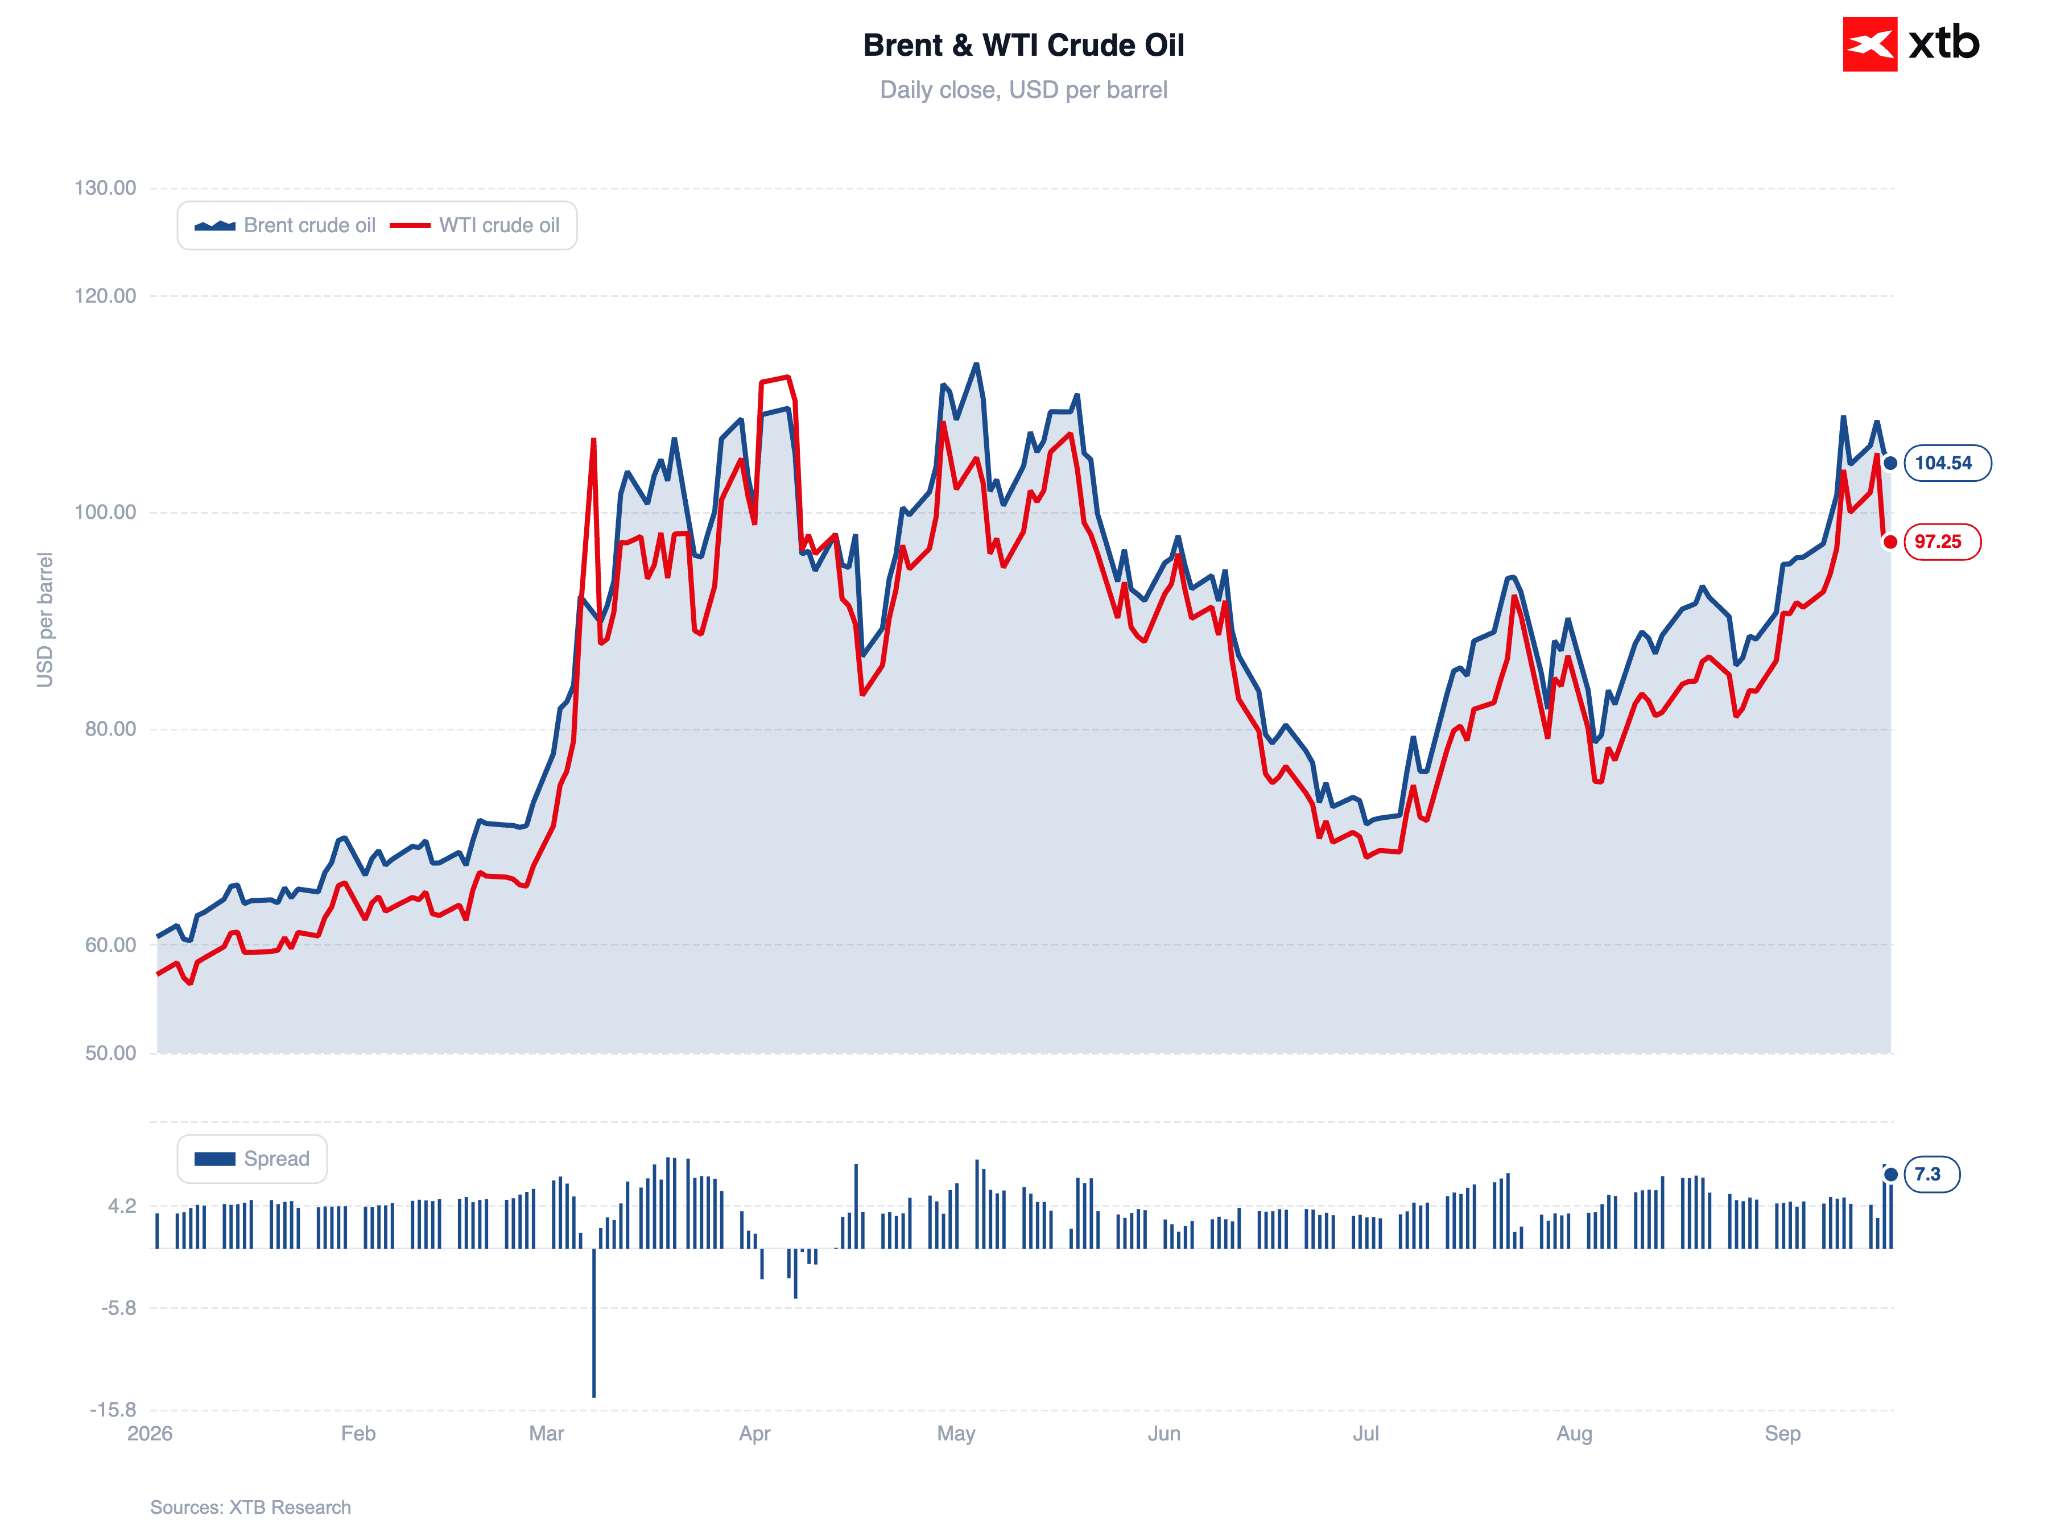
Today, yields on those bonds began to fall sharply, returning to pre-decision levels (around 1.95% for 10-year bonds). The primary catalyst for this move appears to be a sharp drop in crude oil prices. Around 2:00 PM, Brent crude was trading below $102 per barrel.
Figure 1: 10-Year US Government Bond Yields (06.2026 - 09.2026)
 Source: XTB Research, 17.09.2026
We are currently seeing a rebound to higher levels around $105. The correction in the bond market is noticeably weaker. It appears that just as important as the fall in energy commodity prices was the easing of market concerns over the Fed losing its independence, which would have unanchored inflation expectations (and required aggressive monetary tightening in the future). From this viewpoint, the interest rate hike may be seen by investors as the "lesser of two evils".
Figure 2: Brent and WTI Crude Oil (2026)
 Source: XTB Research, 17.09.2026
It is worth noting that despite his hawkish past (while serving on the FOMC between 2006 and 2011, he advocated higher interest rates despite the Great Financial Crisis), Warsh had often hinted at support for rate cuts before taking office. Just over a year ago, he openly backed the President, stating on FOX News that Trump's frustration with Powell's handling of monetary policy was fully justified. At the time, he criticised the institution for lowering rates too slowly and relying excessively on backward-looking economic data.
Yesterday's hike and accompanying rhetoric reduced the ranks of sceptics, giving Warsh a significant vote of confidence. This was something both the Fed and the market desperately needed.
Pressure from Trump
Donald Trump's reaction to the rate hike was surprisingly "calm", if one can call a caps-lock-laden post demanding interest rates be cut to 1% (or lower) calm.
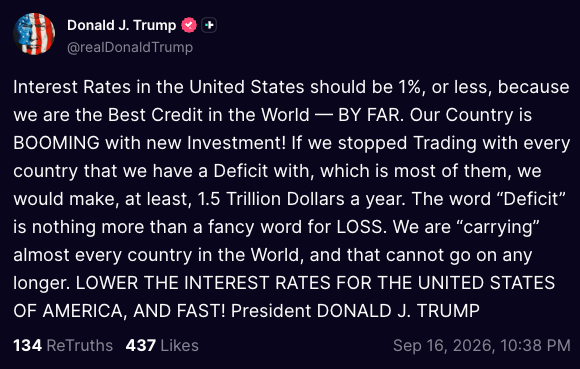 Source: Truth Social, 16.09.2026
Donald Trump's questioning of the Federal Reserve's independence remains, unfortunately, an ongoing issue. Markets remember well the pressure faced during the final months of his term by former Fed Chair Jerome Powell, who in Trump's view kept interest rates insufficiently low. The situation involving Lisa Cook cannot be overlooked either, having been "dismissed" by President Trump. The quotation marks are intentional here: the Supreme Court later overturned the decision, and Cook remains an FOMC member, set to participate in Wednesday's meeting.
Macroeconomic Outlook
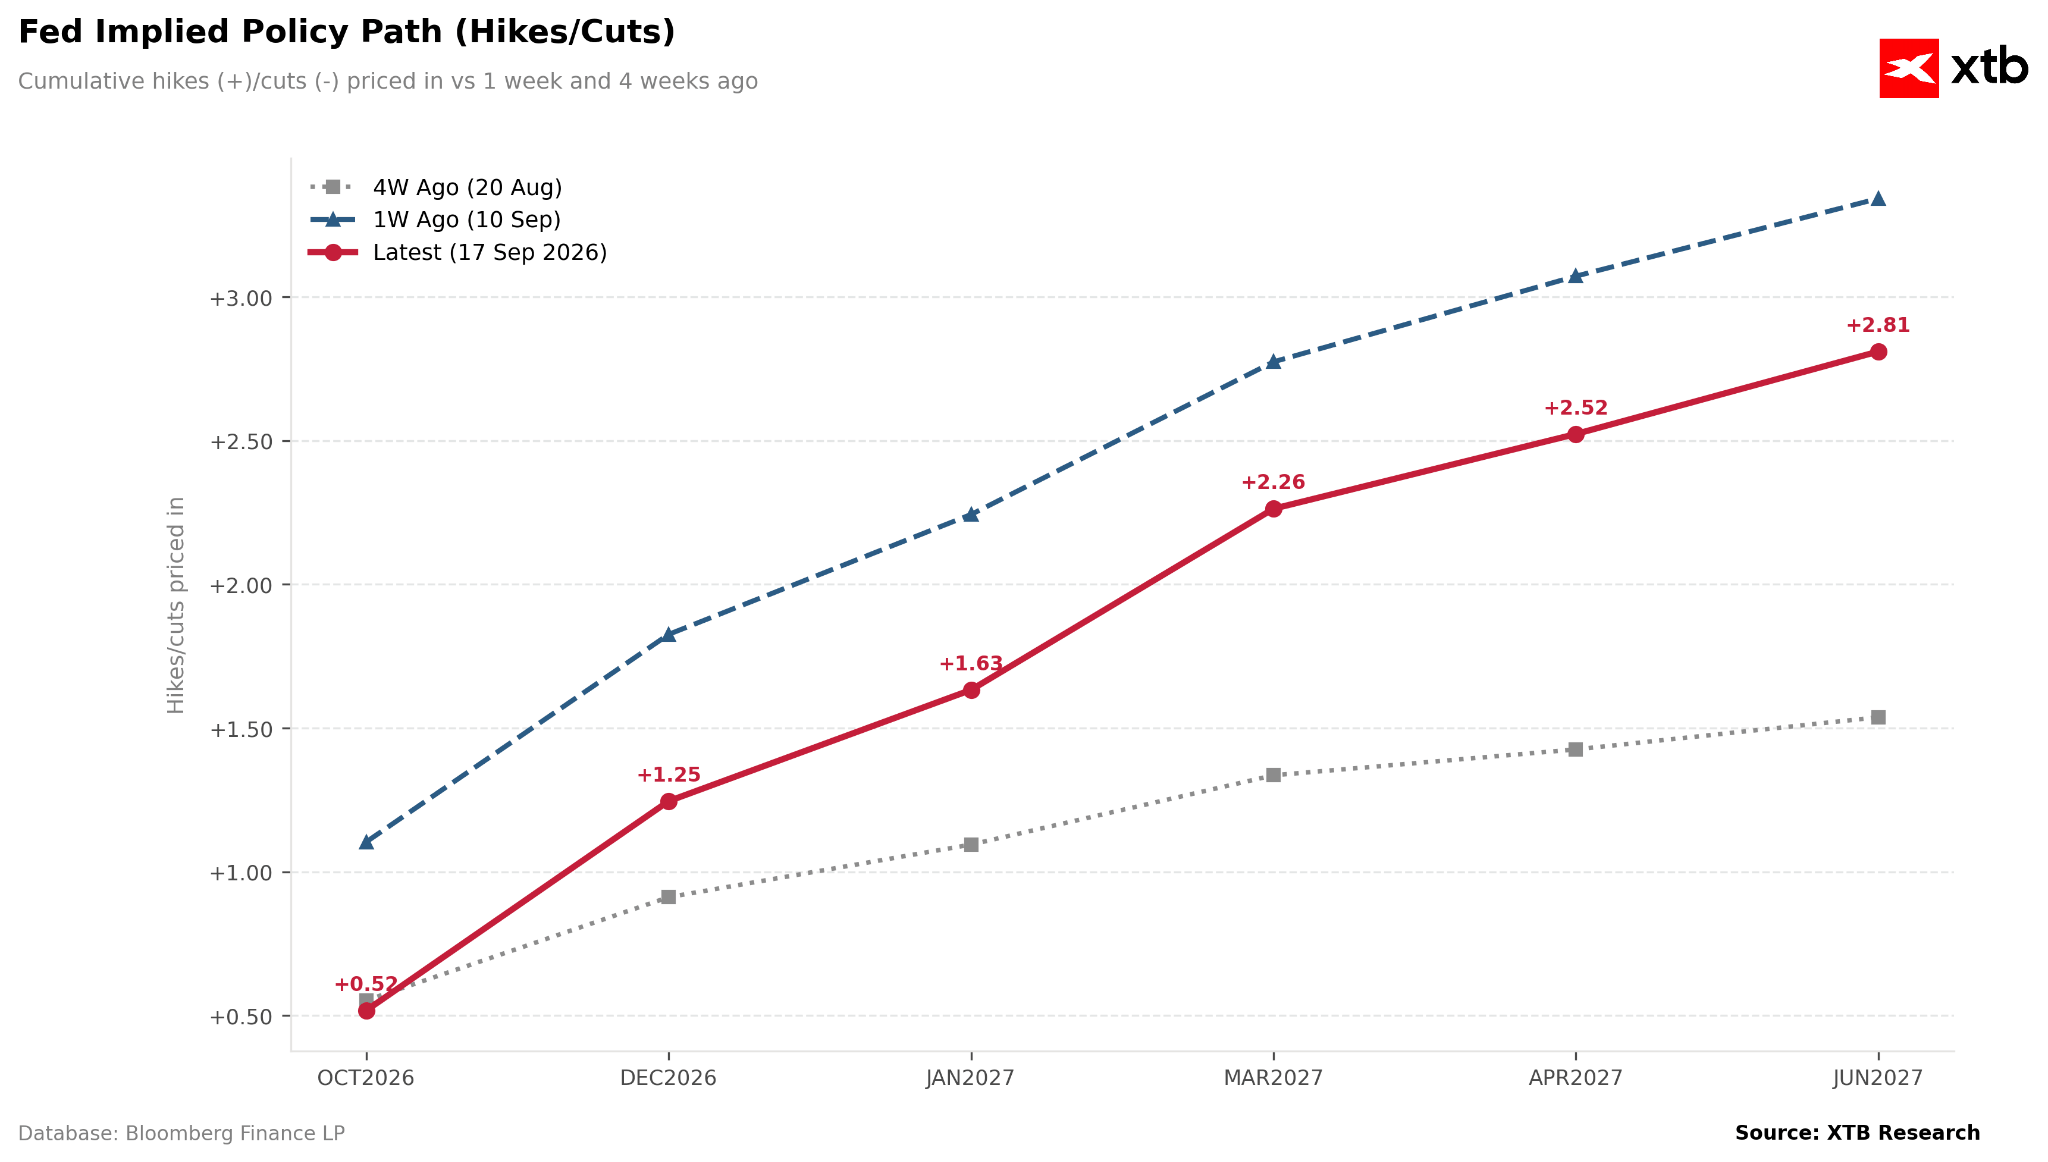
Markets are currently pricing in a relatively dynamic rate-hiking cycle. The baseline scenario envisions three further upward moves before the end of the first half of next year.
Figure 3: Market-Implied Fed Interest Rate Path (2026 - 2027)
 Source: XTB Research, 17.09.2026
*NOTE: The current path references a higher baseline level (i.e. the rate level following yesterday's hike)*
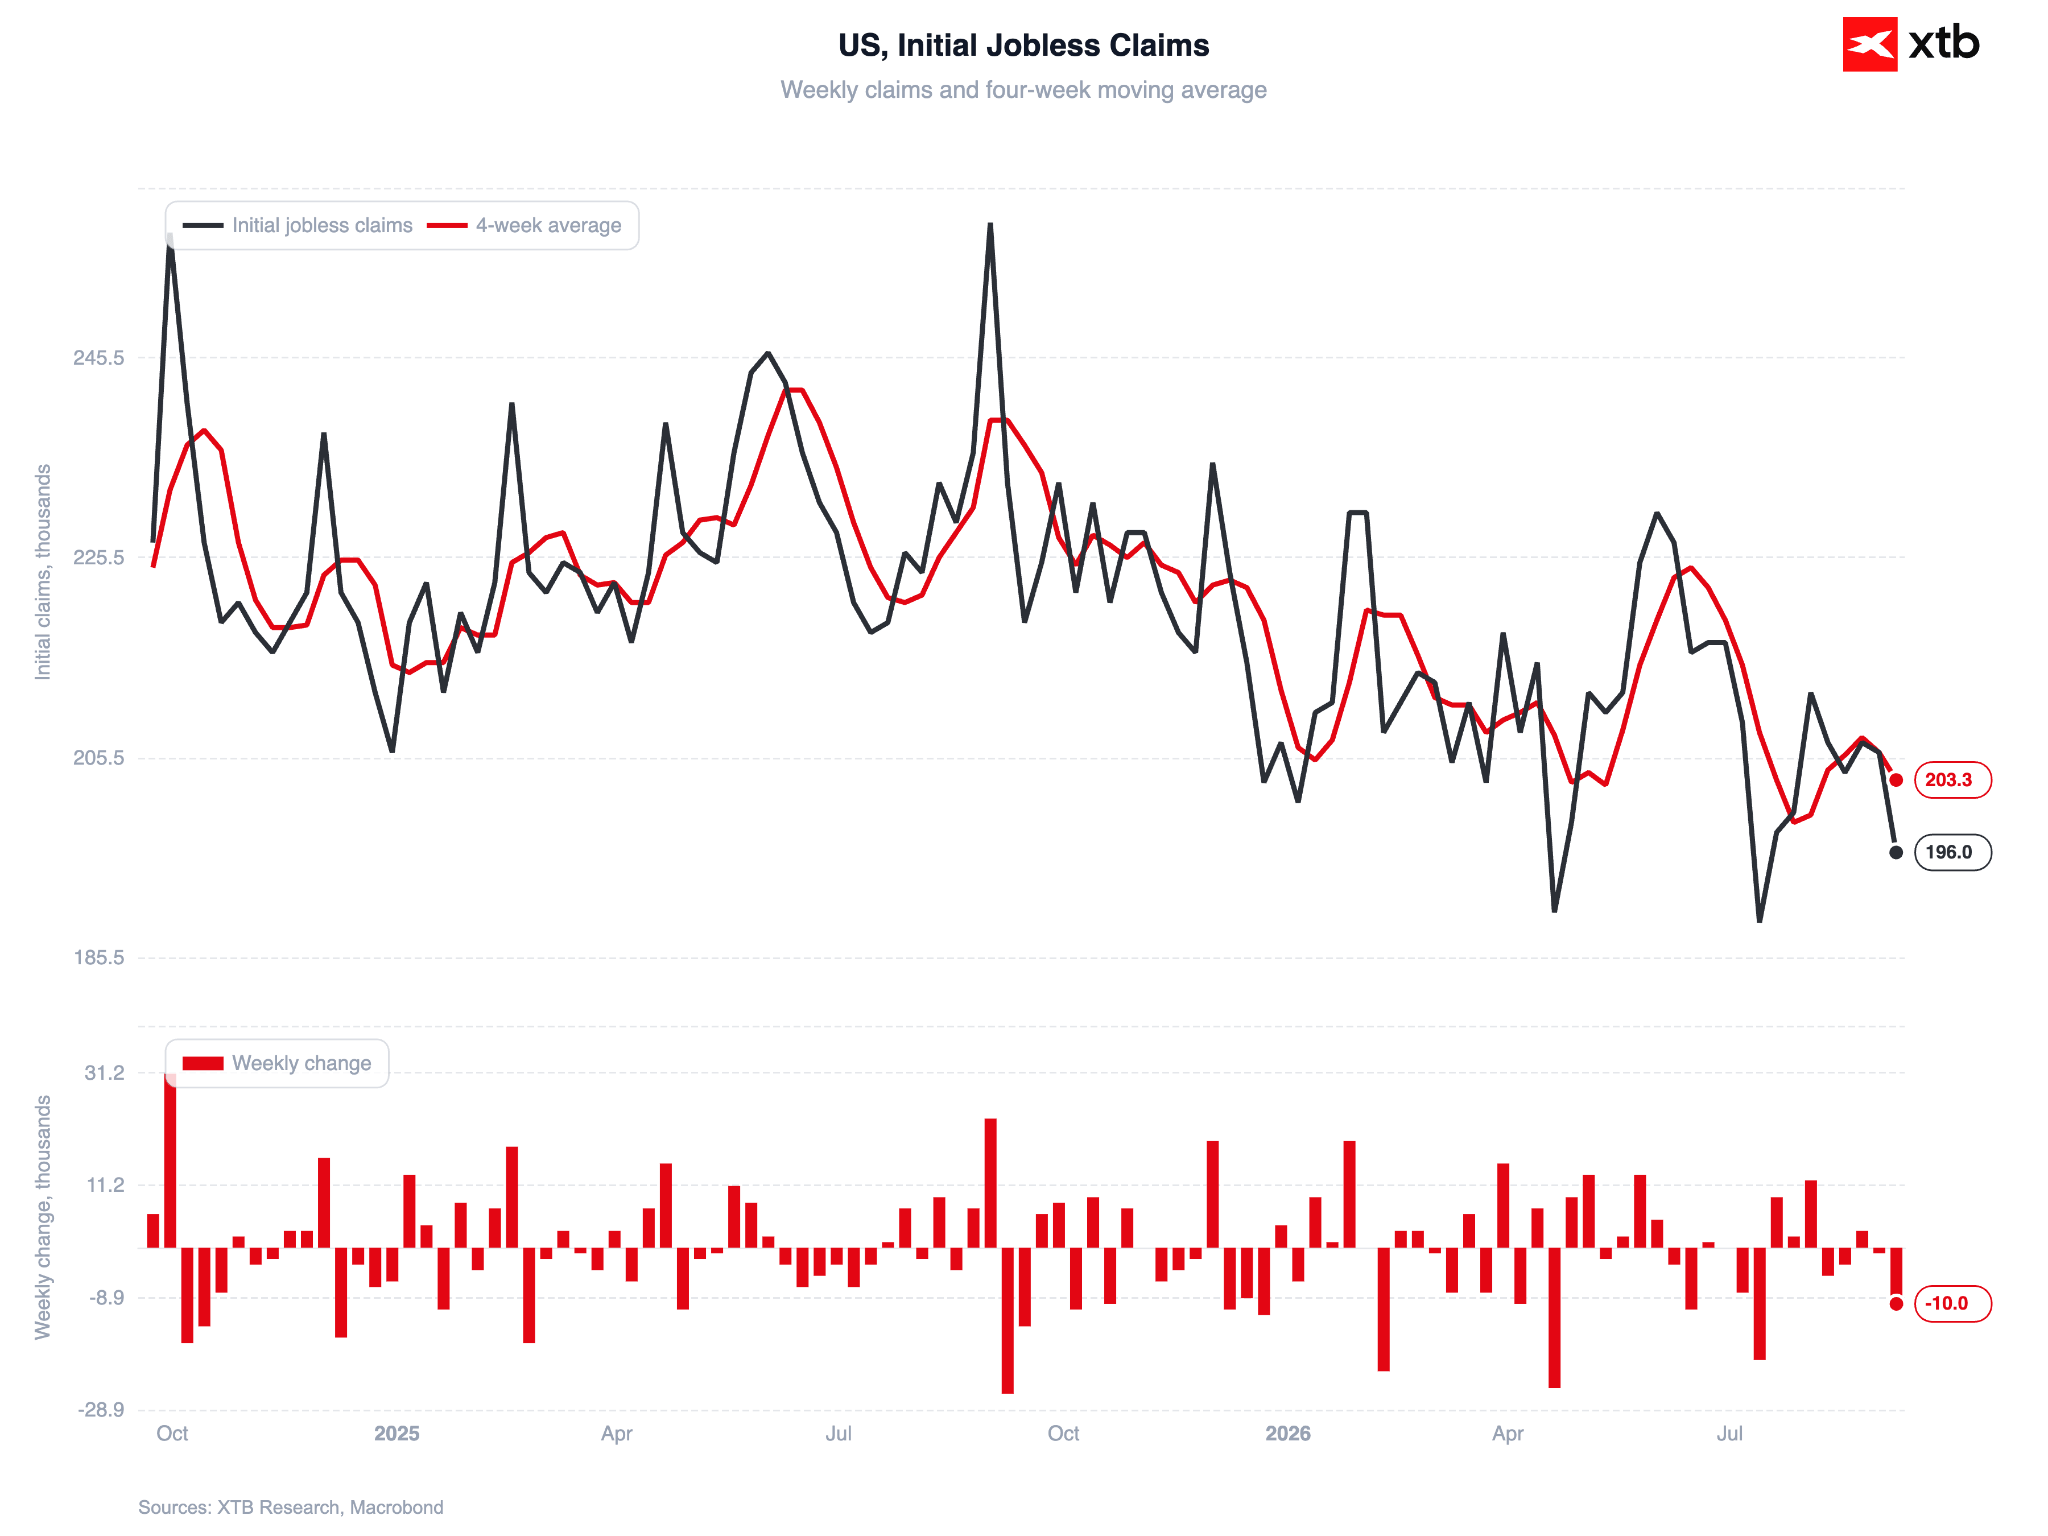
The FOMC enjoys a considerable comfort margin, as the economy remains surprisingly resilient and the labour market stays in a "low fire, low hire" state (low layoffs and low hiring). Therefore, a "soft landing" scenario appears likely, where modest monetary tightening cools buoyant consumption and rising inflation expectations without significantly sapping growth momentum.
Figure 4: US Initial Jobless Claims (2025 - 2027)
 Source: XTB Research, 17.09.2026
Middle East Remains in Focus
A potential correction in energy commodity prices could, of course, trigger a sharp repricing (i.e. unwinding bets on further rate hikes), as observed at the turn of May and June. Attention is focused not only on crude oil and LNG supply (where the situation in the Strait of Hormuz and, increasingly, the Bab-el-Mandeb Strait remains critical), but also on refinery capacity.
The issue of the war in Iran will return to the spotlight in the coming weeks, given the rapid approach of the US midterm elections. From a political perspective, bringing down fuel prices at the pump is of paramount importance.
—
Michał Jóźwiak, Financial Markets Analyst at XTB



US Open: Nasdaq, gold and silver surge following... an interest rate hike (17.09.2026)


🇬🇧 Will the pound recover after the BoE?



📊Daily Summary - Hawkish Fed raises rates and signals more. Dollar gains while gold falls


Hawkish move from the Fed! Warsh takes no prisoners in the fight against inflation. US500 at its lowest since August 3, and gold already below $4,300.
This content has been created by XTB S.A. This service is provided by XTB S.A., with its registered office in Warsaw, at Prosta 67, 00-838 Warsaw, Poland, entered in the register of entrepreneurs of the National Court Register (Krajowy Rejestr Sądowy) conducted by District Court for the Capital City of Warsaw, XII Commercial Division of the National Court Register under KRS number 0000217580, REGON number 015803782 and Tax Identification Number (NIP) 527-24-43-955, with the fully paid up share capital in the amount of PLN 5.869.181,75. XTB S.A. conducts brokerage activities on the basis of the license granted by Polish Securities and Exchange Commission on 8th November 2005 No. DDM-M-4021-57-1/2005 and is supervised by Polish Supervision Authority.