

- US non farm payrolls for October will be released later today at 13:30 GMT.
- Analysts are expecting a reading of 65,000 jobs, this is an increase from the 29,000 jobs created in September.
- The unemployment is expected to remain unchanged at 4.2%.
- There are a wide range of forecasts this month, for example, Barclays expects 50,000, KPMG 45,000, RSM 95,000 and Vanguard 120,000. Wage growth of 0.2% to 0.3% month on month would fit with the "low hiring, low firing" economic narrative.

- US non farm payrolls for October will be released later today at 13:30 GMT.
- Analysts are expecting a reading of 65,000 jobs, this is an increase from the 29,000 jobs created in September.
- The unemployment is expected to remain unchanged at 4.2%.
- There are a wide range of forecasts this month, for example, Barclays expects 50,000, KPMG 45,000, RSM 95,000 and Vanguard 120,000. Wage growth of 0.2% to 0.3% month on month would fit with the "low hiring, low firing" economic narrative.
By Kathleen Brooks, research director at XTB
Backdrop
The September NFP report was weak. Payrolls rose just 29,000, below every estimate in a Bloomberg survey, and July and August were revised down by a combined 60,000. Since then the data has firmed. ADP private payrolls rose 86,000 in October, above the 75,000 expected. A strong JOLTS report on Tuesday also surprised the market, and some investors may read a strong jobs report as the labour market re-accelerating after a summer soft patch.
Payrolls and the Fed
This is a rate-hike debate, not a cutting one. The FOMC is focused on inflation. Barclays says 50,000 jobs with slightly lower unemployment would keep a December hike in play, anything above this would likely boost expectations of further hikes in Q1 2027. That makes good news potentially bad news for rate-sensitive assets, and could add to the downward pressure on tech stocks.
Scenario analysis
Below we take a look at the potential outcomes for payrolls and what they could mean for markets.
- Soft (below ~40k, unemployment up): The chance of a December rate hike falls and yields and the dollar ease further. Equities get near-term relief, though a deeper slump would revive growth fears.
- In line (50-70k, 4.2%): Little reaction. Attention shifts to the next main economic release, the inflation data.
- Hot (100k+, wages 0.3%+): Rate hike expectations rise into 2027 and the dollar firms after underperforming in recent weeks. Growth stocks may come under even more pressure, which could add to fears that the AI bubble is bursting.
It is worth noting that evisions to prior months and the unemployment rate could matter as much as the headline number.
Chip stocks
Semiconductors are among the most exposed to a hot print. They are long-duration, richly valued growth assets, so they react sharply to yield moves. The Philadelphia chip index fell 14% on Thursday, wiping out about $2 trillion in market value, Nvidia dropped nearly 10%, as investors reassess the outlook for AI based on potential future regulatory hurdles and a potential ban on AI development and some data centres. There are also concerns about excessive expansion and leverage, which all added to the market crash.
A hot NFP report that stokes fears of more rate hikes, while stock markets are struggling could add fuel to Thursday’s fire, so expect volatility if jobs growth is strong.
Below are some potential scenarios for the AI trade on the back of the NFP release.
- Hot print: The most likely trigger for another sharp chip sell-off. Nvidia, AMD, Broadcom and Micron would feel it most.
- Soft-but-stable print: The best case for the sector, since it eases hike fears without signalling a demand collapse.
- Very weak print: A mixed outcome. Lower yields help valuations, but AI-capex-sensitive names could wobble if growth worries take over.
This payrolls report comes at a fragile time for market sentiment. Asset prices will be extremely sensitive to today’s data, and a reading that is larger or smaller than expectations could trigger further market volatility.
Chart 1: Nasdaq 100, drops below its 200-day sma to its lowest level since April
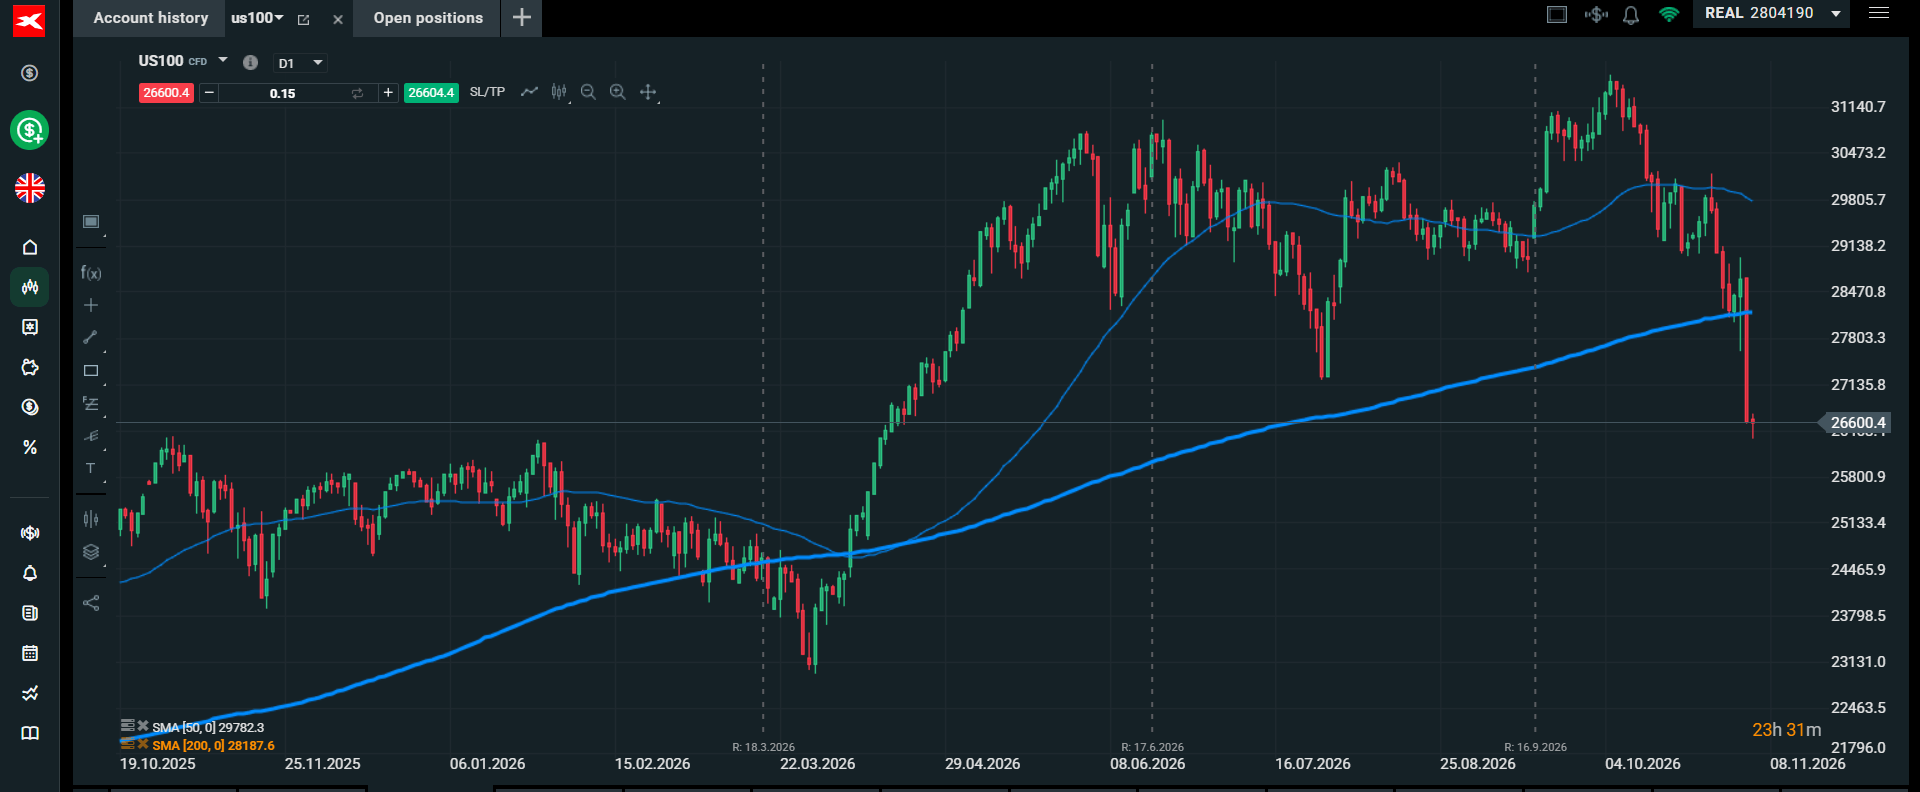
Source:XTB. Past performance is not a reliable indicator of future results.


BOE review
BREAKING: BoE raises interest rates by 25pbs to 4%⏰
BOE checklist

FTSE 100 nears record high, as markets welcome US political change
This content has been created by XTB S.A. This service is provided by XTB S.A., with its registered office in Warsaw, at Prosta 67, 00-838 Warsaw, Poland, entered in the register of entrepreneurs of the National Court Register (Krajowy Rejestr Sądowy) conducted by District Court for the Capital City of Warsaw, XII Commercial Division of the National Court Register under KRS number 0000217580, REGON number 015803782 and Tax Identification Number (NIP) 527-24-43-955, with the fully paid up share capital in the amount of PLN 5.869.181,75. XTB S.A. conducts brokerage activities on the basis of the license granted by Polish Securities and Exchange Commission on 8th November 2005 No. DDM-M-4021-57-1/2005 and is supervised by Polish Supervision Authority.