


Nvidia (NVDA.US) reported fiscal Q3 2027 results that significantly exceeded Wall Street expectations, confirming exceptionally strong demand for artificial intelligence infrastructure; shares initially surged nearly 4% following the release. Revenue reached a record $115.8 billion, increasing more than 103% YoY and exceeding analysts' consensus estimate of $109.33 billion. The Data Center segment delivered even more impressive results, with revenue climbing to $107.6 billion, well above expectations and accounting for nearly 93% of the company's total revenue. Adjusted earnings per share reached $2.68 versus expectations of $2.47, while net income hit a record of approximately $65.3 billion. However, the most important takeaway from the report may be Nvidia's fourth-quarter revenue guidance of $130 billion, suggesting further sales acceleration and exceeding analysts' expectations. The company also announced an additional $150 billion share repurchase authorization, highlighting its substantial cash-generating capacity.
The results could provide a significant catalyst for restoring investor confidence in the AI sector, although questions remain about the sustainability of current technology investment levels and potential pressure on profit margins. Nvidia indicated that its share repurchases during the current quarter could, on average, more than double compared with the previous quarter, based on its announced spending plans. In the CFO commentary, the company stated that it intends to utilize the remaining $227.3 billion authorized under its current share repurchase program through fiscal 2028. This would imply average buyback spending of $45.46 billion per quarter over the next five quarters. Following the US market close, reports emerged that Nvidia had become the subject of an investigation by the US Securities and Exchange Commission (SEC). However, the full scope of the investigation remains unclear, with speculation suggesting that it may focus on shareholder communications rather than directly on accounting or financial reporting matters.
Key results for Q3 FY2027 (calendar Q3 2026)
-
Revenue: $115.8 billion versus $109.33 billion expected, up 103% YoY and 20.3% QoQ.
-
Adjusted EPS: $2.68 versus $2.47 expected, representing an earnings beat of approximately 8.5%.
-
Net income: Approximately $65.3 billion, a record high for the company.
-
Data Center: $107.6 billion versus $101.87 billion expected, up approximately 110% YoY.
-
Hyperscale: $60.1 billion in revenue, above the $59.27 billion consensus estimate.
-
AI Clouds, Industrial & Enterprise: $47.5 billion in revenue, indicating the growing importance of customers beyond the largest cloud service providers.
-
Edge Computing: $8.2 billion versus $7.5 billion expected.
-
Adjusted gross margin: 74.9%, above market expectations.
-
Q4 FY2027 revenue guidance: $130 billion (±3%) versus consensus expectations of approximately $124.4 billion.
-
Q4 operating expenses: Approximately $10.7 billion, in line with management's expectations.
-
Share repurchases: An additional $150 billion authorization, increasing the remaining buyback capacity to approximately $227.3 billion.
-
China: According to management's earlier statements, the company had not included Data Center computing chip sales to China in its forecasts, highlighting regulatory risks to its Asian operations.
Nvidia: AI demand shows no signs of slowing as record results confirm the scale of investment
The most important takeaway from Nvidia's earnings report is the sustained growth momentum in its Data Center segment, where quarterly revenue has now exceeded $100 billion. Compared with the previous quarter, Nvidia's total revenue increased by more than $19.5 billion, demonstrating that the company continues to generate extraordinary sales growth even in absolute dollar terms. Importantly, growth is no longer driven exclusively by the largest hyperscalers, as AI infrastructure providers, industrial customers and enterprises deploying new artificial intelligence models are playing an increasingly important role.
Nvidia's $130 billion revenue forecast for the fourth quarter may matter more to investors than the company's Q3 earnings beat itself. It suggests that Nvidia expects another double-digit increase in sequential revenue despite an already exceptionally high comparison base. Meanwhile, Data Center's share of total revenue is approaching 93%, making the company's financial performance increasingly dependent on global AI infrastructure spending. As long as major technology companies and cloud service providers continue expanding capital expenditure, Nvidia remains one of the primary beneficiaries of this trend, although any reduction in CAPEX could quickly affect the pace of new orders.
Record profits and Nvidia's buyback: Can earnings reverse the selloff?
Nvidia has demonstrated its ability to combine extraordinary revenue growth with exceptionally high profitability, delivering an adjusted gross margin of 74.9%. Net income of approximately $65.3 billion shows that the expansion of AI infrastructure is translating not only into greater business scale but also into enormous profits. Another sign of financial strength is the additional $150 billion share repurchase authorization, which could support earnings per share in future periods, although it does not eliminate downside valuation risks.
Despite the impressive results, investors are likely to focus on the sustainability of profit margins, component costs and risks associated with exporting advanced processors to China. The company also faces leadership uncertainty following Jensen Huang's departure, alongside rising expectations regarding returns on the technology industry's multibillion-dollar investments in AI infrastructure. Furthermore, the high concentration of revenue in the Data Center segment means that even a modest slowdown in order growth could trigger a substantial market reaction. Nevertheless, the Q3 report demonstrates that Nvidia's underlying financial performance remains exceptionally strong, while the stock's next major move may depend on whether the company can sustain its rapid growth into fiscal 2028.
Record AI demand, but dependence on infrastructure financing is growing
Nvidia's results show that demand for artificial intelligence infrastructure is increasingly expanding beyond the largest hyperscalers. Revenue from major cloud providers rose 71% YoY to $60.1 billion in Q3, significantly exceeding analysts' expectations of $54.1 billion. The AI Clouds, Industrial & Enterprise segment grew even faster, with revenue surging 195% YoY to $47.5 billion, although slightly missing the $48.4 billion consensus estimate. Meanwhile, shipments of Hopper chips to data centers in China generated $2.4 billion in revenue, confirming that the Chinese market remains important to Nvidia despite US export restrictions.
However, rising sales are accompanied by an unprecedented level of commitments related to future supplies and infrastructure expansion. Nvidia's purchase commitments increased from $279 billion to $390 billion in just one quarter, primarily driven by multi-year contracts for memory components used in AI systems. At the same time, commitments related to cloud service agreements and data center leases rose from $74 billion to $102 billion. Such extensive contractual obligations could help Nvidia secure access to strategic components and infrastructure, but they also increase the company's exposure to a potential slowdown in AI investment, particularly if future demand falls short of current expectations.
Nvidia is financing its customers' expansion: Record cash flow and $118 billion in guarantees
Nvidia is becoming increasingly involved not only in selling AI processors but also in financing the infrastructure that drives demand for its products. The company notes that many AI cloud providers and developers of advanced AI models are expanding faster than their balance sheets can support, prompting Nvidia to help finance new projects. Its maximum exposure under guarantees provided to partners increased to $118 billion from $108.5 billion in the previous quarter. As much as $105 billion of this amount represents credit support for SB Energy's planned 4.25 GW campus in Ohio, which is expected to host Nvidia infrastructure for OpenAI under 20-year lease agreements. The company has also disclosed $20 billion in equity investment commitments focused on leading AI laboratories and infrastructure financing partners.
This raises an important question: To what extent is Nvidia simply benefiting from the AI boom, and to what extent is it beginning to finance future demand for its own products? Such involvement could accelerate data center development and strengthen Nvidia's competitive position, but it also increases concentration risk and financial interdependencies between the chipmaker and its customers. Nvidia emphasizes that it has not made any payments under these guarantees to date, meaning that the disclosed exposure should not be confused with losses already incurred. Importantly, the company generated a record $43.8 billion in free cash flow in Q3, more than double the $21.3 billion recorded in the previous quarter, while returning a record $28.1 billion to shareholders. This highlights Nvidia's extraordinary cash-generating capacity, although the growing scale of guarantees and multi-year commitments makes assessing the company's financial risks increasingly complex.
Nvidia stock chart (D1 timeframe)
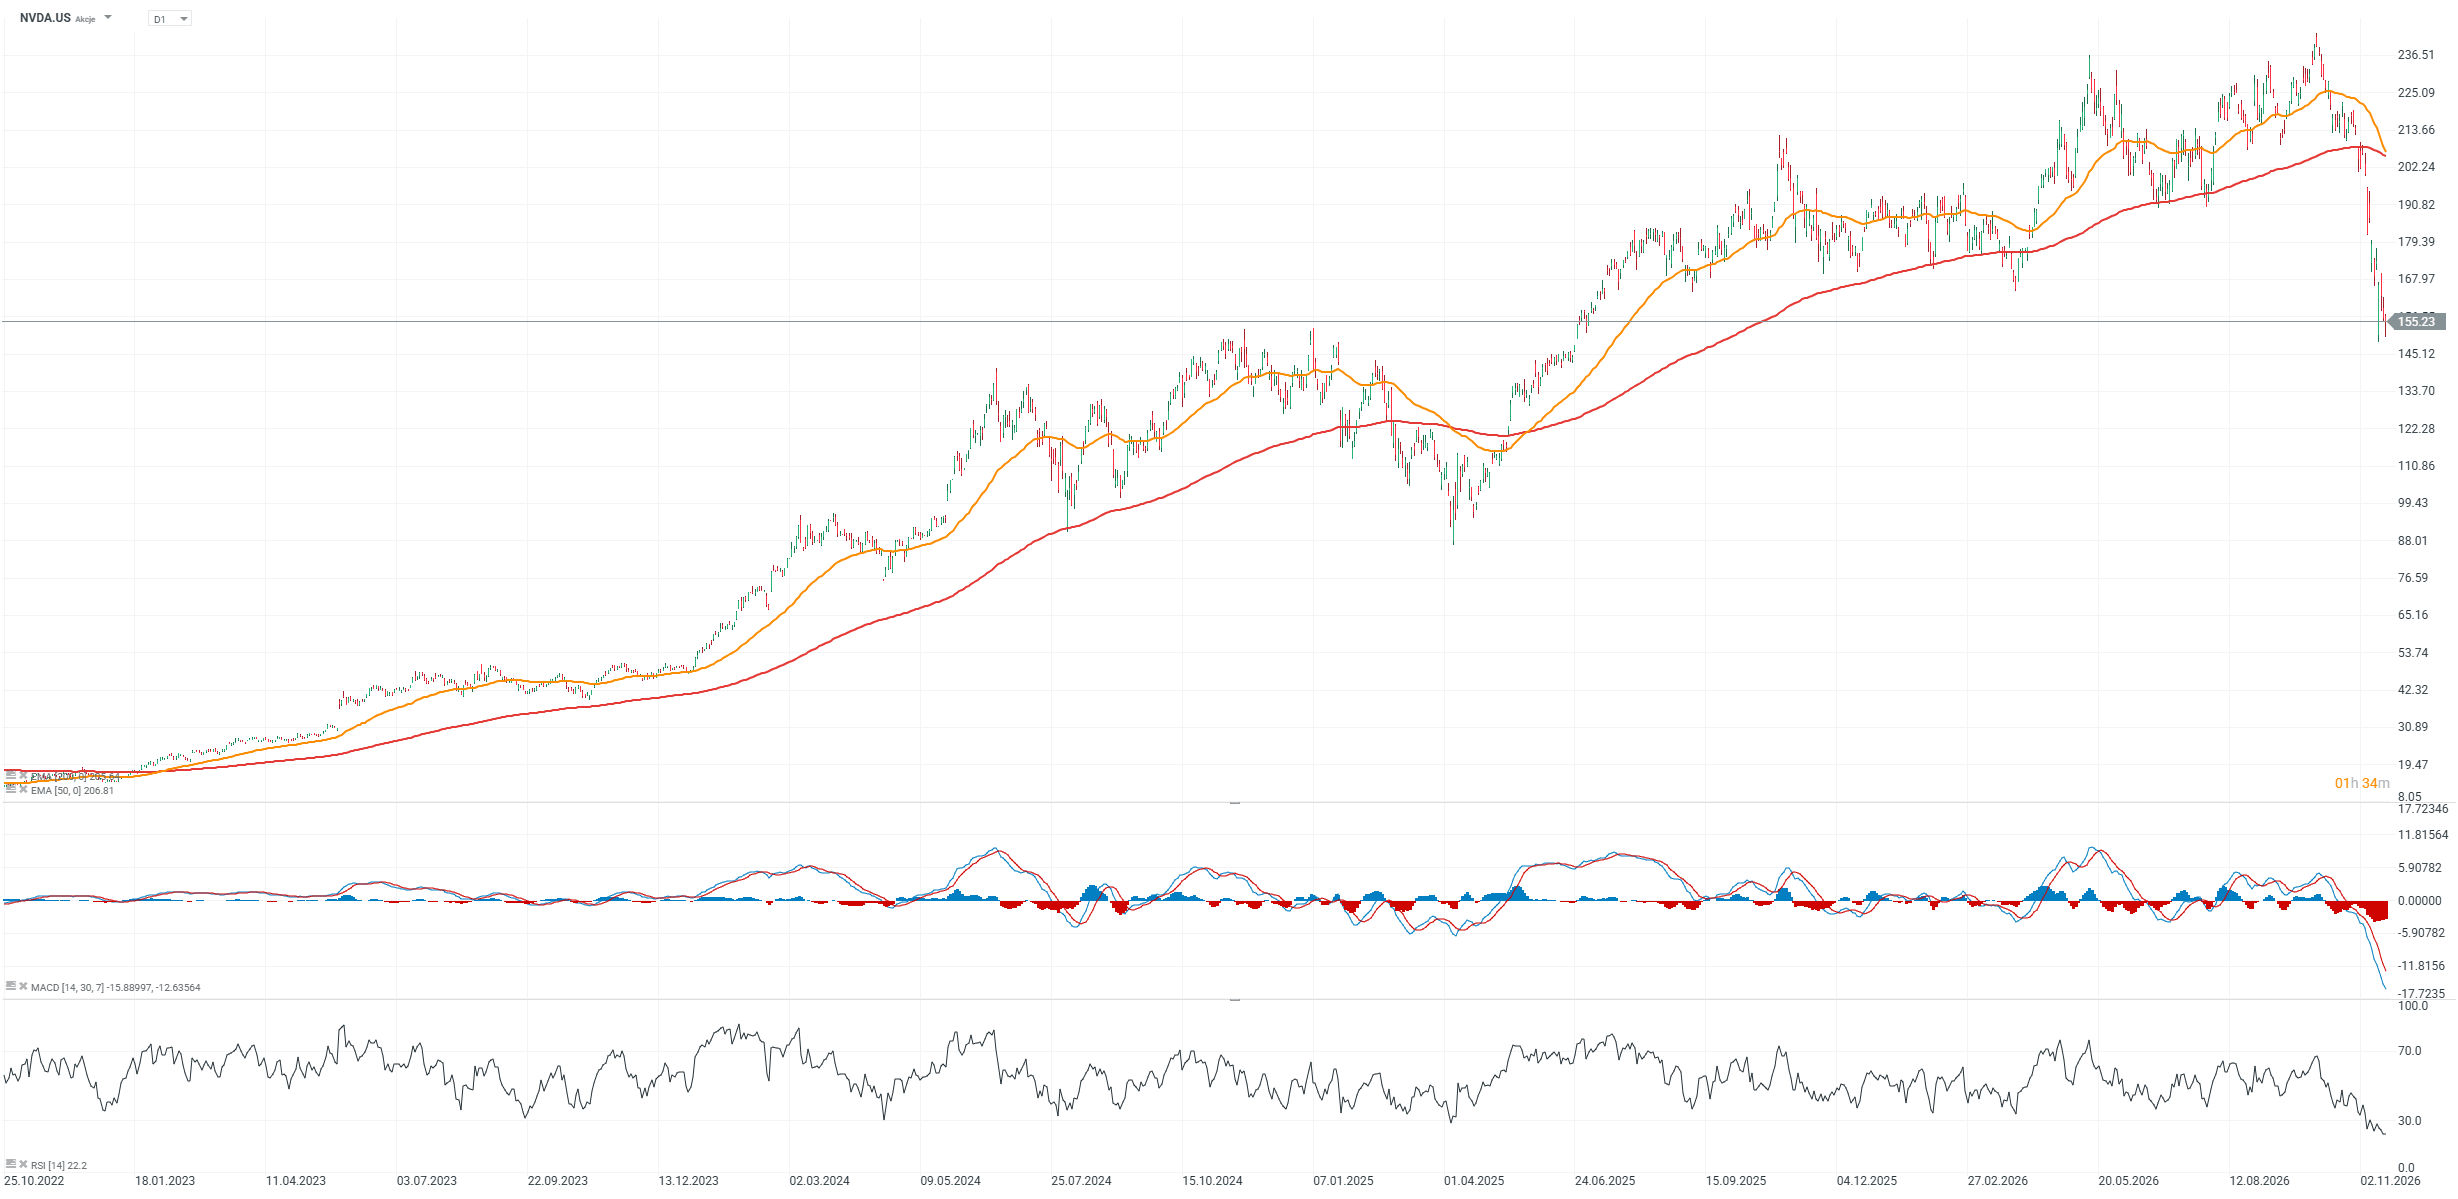 Source: XTB


Shares of Nike drop despite business turnaround 🚩Disney and Home Depot after earnings reports

US Open: Wall Street on Edge Ahead of Nvidia Earnings 🚩 Could Rising Oil Prices Weigh on Stocks?



Nvidia stabilises ahead of earnings, but the AI outlook remains unclear
Nvidia Preview: Strong Results, Uncertain Future
This content has been created by XTB S.A. This service is provided by XTB S.A., with its registered office in Warsaw, at Prosta 67, 00-838 Warsaw, Poland, entered in the register of entrepreneurs of the National Court Register (Krajowy Rejestr Sądowy) conducted by District Court for the Capital City of Warsaw, XII Commercial Division of the National Court Register under KRS number 0000217580, REGON number 015803782 and Tax Identification Number (NIP) 527-24-43-955, with the fully paid up share capital in the amount of PLN 5.869.181,75. XTB S.A. conducts brokerage activities on the basis of the license granted by Polish Securities and Exchange Commission on 8th November 2005 No. DDM-M-4021-57-1/2005 and is supervised by Polish Supervision Authority.