



Shares of Palantir Technologies (PLTR.US) initially fell by almost 2.5% following the quarterly earnings release, despite the company reporting strong Q3 2026 results that exceeded analysts' expectations for both revenue and adjusted earnings per share. Revenue surged 96% year over year to $2.31 billion, with the US commercial segment remaining the fastest-growing business, posting 149% year-over-year growth amid rapid adoption of artificial intelligence solutions. Particularly impressive is Palantir's ability to combine nearly triple-digit revenue growth with exceptionally high operating profitability, distinguishing it from many AI infrastructure and software providers. Management also significantly raised its full-year 2026 guidance, signalling continued strong demand for its analytics platforms and AI solutions among both commercial and government customers. Importantly, the company now expects full-year revenue growth of 91%, suggesting a slightly slower pace of expansion than the 96% recorded in Q3. However, investors will have to wait until tomorrow's trading session to assess the broader market reaction, as the initial buying response to the earnings beat appears relatively subdued.
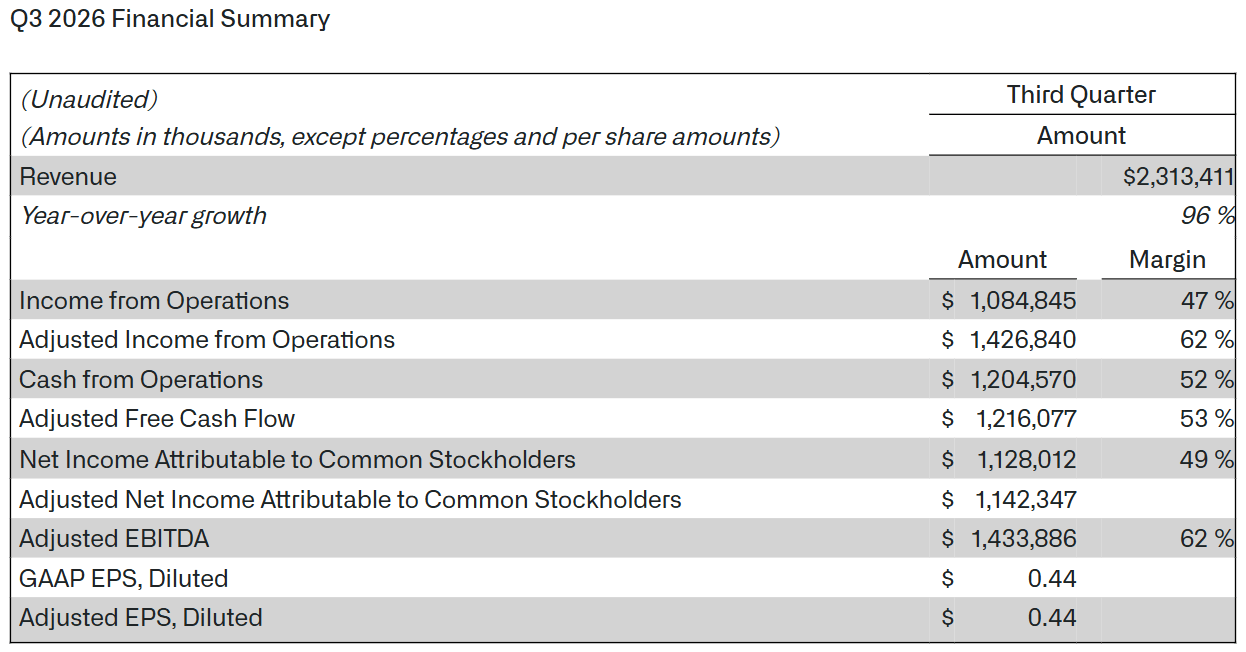
Palantir Q3 2026 earnings: Key figures
-
Revenue increased 96% year over year to $2.31 billion, beating analysts' consensus estimate of $2.18 billion by approximately 6%. Such rapid growth at a multibillion-dollar revenue scale highlights the exceptional pace of business expansion and increasing adoption of the company's Artificial Intelligence Platform (AIP).
-
Adjusted earnings per share (EPS) reached $0.44, compared with expectations of $0.41. Adjusted operating income climbed to $1.43 billion, significantly exceeding the $1.26 billion consensus estimate. This demonstrates how strong revenue growth is translating into substantial improvements in operating profitability.
-
US commercial revenue surged 148% year over year to $984 million, surpassing expectations of $943 million. This is among the most important aspects of the report, as it demonstrates that Palantir's expansion extends well beyond its traditional government business, with demand from private-sector customers remaining exceptionally strong.
-
Total US revenue reached $1.94 billion, representing 119% year-over-year growth. The US government segment generated $953 million in revenue, up 96% from the previous year and above the $862 million consensus estimate. These figures highlight simultaneous expansion across both major business segments, although commercial operations are currently growing considerably faster.
Source: Palantir
Profitability, new contracts and the quality of growth
-
Adjusted operating margin reached an impressive 62%, an exceptionally high level for a company growing revenue at almost 100% annually. This reflects substantial operating leverage, as further revenue expansion does not require a proportional increase in operating expenses. However, adjusted operating margin should not be confused with profitability calculated under GAAP accounting standards.
-
Palantir's Rule of 40 score reached 158%, calculated as the sum of revenue growth and adjusted operating margin. A result far above the software industry's commonly referenced 40% benchmark highlights the company's unusual combination of growth and profitability, although the metric does not account for equity valuation or the risk of future growth deceleration.
-
Total contract value (TCV) reached $2.92 billion, increasing 86% year over year. Within the US commercial segment alone, TCV climbed to $1.46 billion, representing growth of 116%. This is an important indicator of future revenue potential, although the total value of signed contracts should not be confused with revenue recognised during the current quarter.
-
Remaining Deal Value (RDV) increased 79% year over year to $6.52 billion. The expanding contract backlog improves visibility into future revenue and suggests that demand for Palantir's solutions could remain strong in subsequent quarters. However, the timing of revenue recognition will depend on contractual terms and implementation schedules.
-
Palantir signed 212 contracts worth at least $1 million during the quarter, including 107 deals valued at $5 million or more and 64 contracts exceeding $10 million. The large number of high-value agreements points to increasingly substantial deployments rather than growth driven solely by smaller pilot projects. These categories overlap and should not be added together.
Palantir raises its 2026 and Q4 guidance
-
Full-year 2026 revenue guidance was raised to $8.530–8.534 billion, compared with the consensus estimate of approximately $8.2 billion. This indicates that management expects exceptionally strong business momentum to continue into the final quarter of the year. Adjusted operating income is projected to reach $5.245–5.249 billion, significantly above analysts' expectations of around $4.76 billion. Such a substantial premium to consensus suggests that Palantir expects to maintain elevated margins despite the rapid expansion of its operations.
-
Adjusted free cash flow (FCF) guidance was set at $4.8–5.0 billion, compared with market expectations of $4.52 billion. Strong conversion of operating performance into cash remains one of the most important characteristics of Palantir's business model, although evaluating cash flow quality also requires consideration of the adjustments included in the company's definition of adjusted FCF.
-
US commercial revenue is expected to exceed $3.6 billion for the full year. This is a particularly important forecast because it confirms that expansion among enterprise customers remains central to Palantir's growth strategy.
-
For Q4 2026, Palantir expects revenue of $2.649–2.653 billion, comfortably above the consensus estimate of approximately $2.46 billion. The midpoint of this range implies roughly 15% sequential revenue growth compared with Q3, indicating further acceleration in absolute revenue generation.
-
Adjusted operating income is expected to reach $1.640–1.644 billion, versus analysts' expectations of approximately $1.41 billion. At the midpoint of the revenue guidance range, this would imply an adjusted operating margin close to 62%, pointing to continued operating scalability.
Palantir's business has shifted into overdrive. Is it enough?
The report confirms that Palantir remains one of the fastest-growing providers of artificial intelligence solutions for commercial and government customers. Particularly noteworthy is the combination of nearly triple-digit revenue growth, exceptionally high adjusted operating profitability and increasing contract values, which supports the outlook for subsequent quarters. Management emphasises that the development of sovereign artificial intelligence applications could fundamentally reshape how businesses and government institutions operate. However, the company's valuation and its ability to maintain such exceptional growth rates remain the most significant risks. Even results that substantially exceed expectations may not be enough to drive the share price higher if investors have already priced in years of nearly flawless execution.
CEO Alex Karp emphasised that Palantir's ambition is to capture the entire addressable market for defence-related AI software rather than merely increase its share in selected segments. He noted that Palantir's quarterly revenue had almost doubled over the past year to approximately $2.3 billion, while describing the 29% quarter-over-quarter growth in US commercial revenue as extraordinary even by the standards of America's fastest-growing technology companies. Karp also highlighted record quarterly profit of $1.13 billion, pointing out that not long ago the company's entire quarterly revenue was lower than this amount. He additionally portrayed Palantir as an exceptional environment for developing future entrepreneurs, claiming that the company surpasses even Stanford, MIT, Google and McKinsey in this respect. His comments reflect an exceptionally ambitious expansion strategy and management's conviction that technological advances could enable Palantir to scale its operations further. Nevertheless, given the demanding valuation and the nearly 30-fold increase in the share price from May 2023 levels, investors may increasingly face pressure to realise profits.
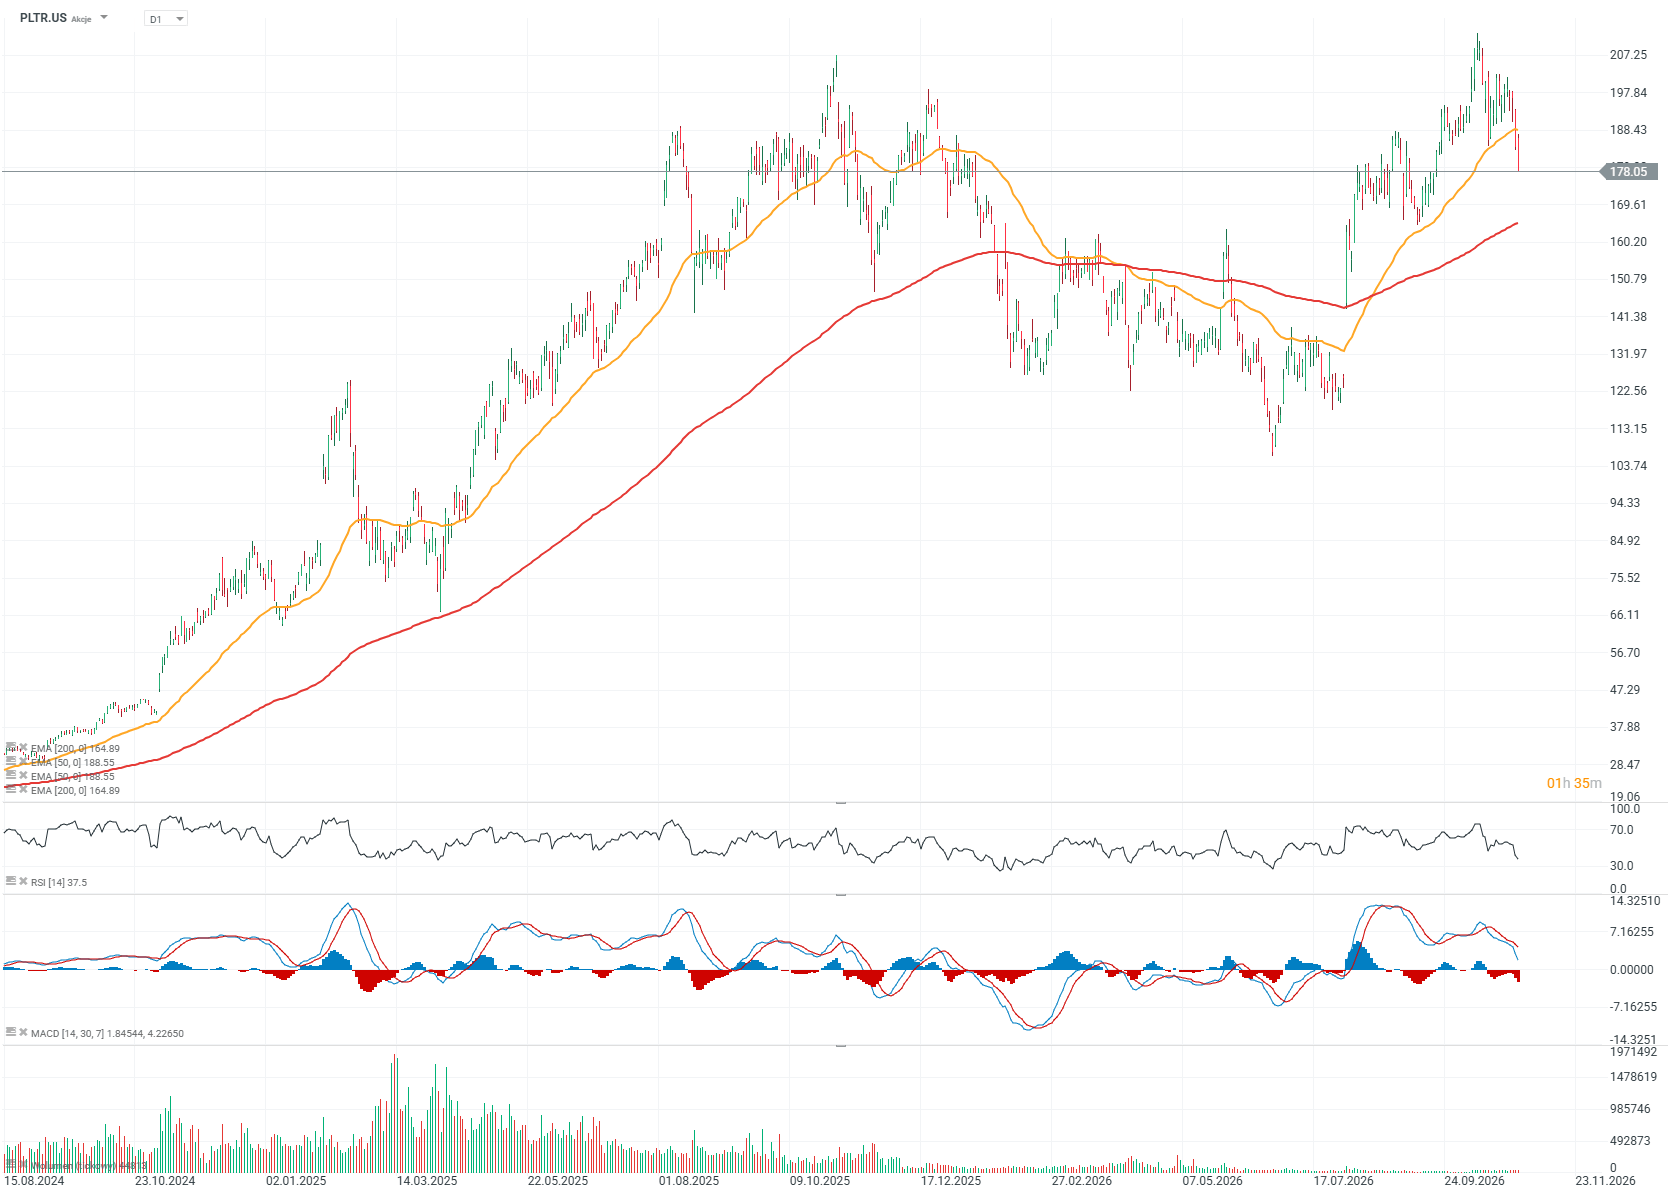
Palantir shares (D1 timeframe)
Palantir shares have declined approximately 10% from their recent all-time high and have experienced several particularly weak trading sessions. The market's initial response to the earnings release appears cautious and provides little indication of where the shares will open tomorrow. Valuation remains the company's biggest challenge, as current share prices already reflect numerous optimistic scenarios.
Source: xStation5
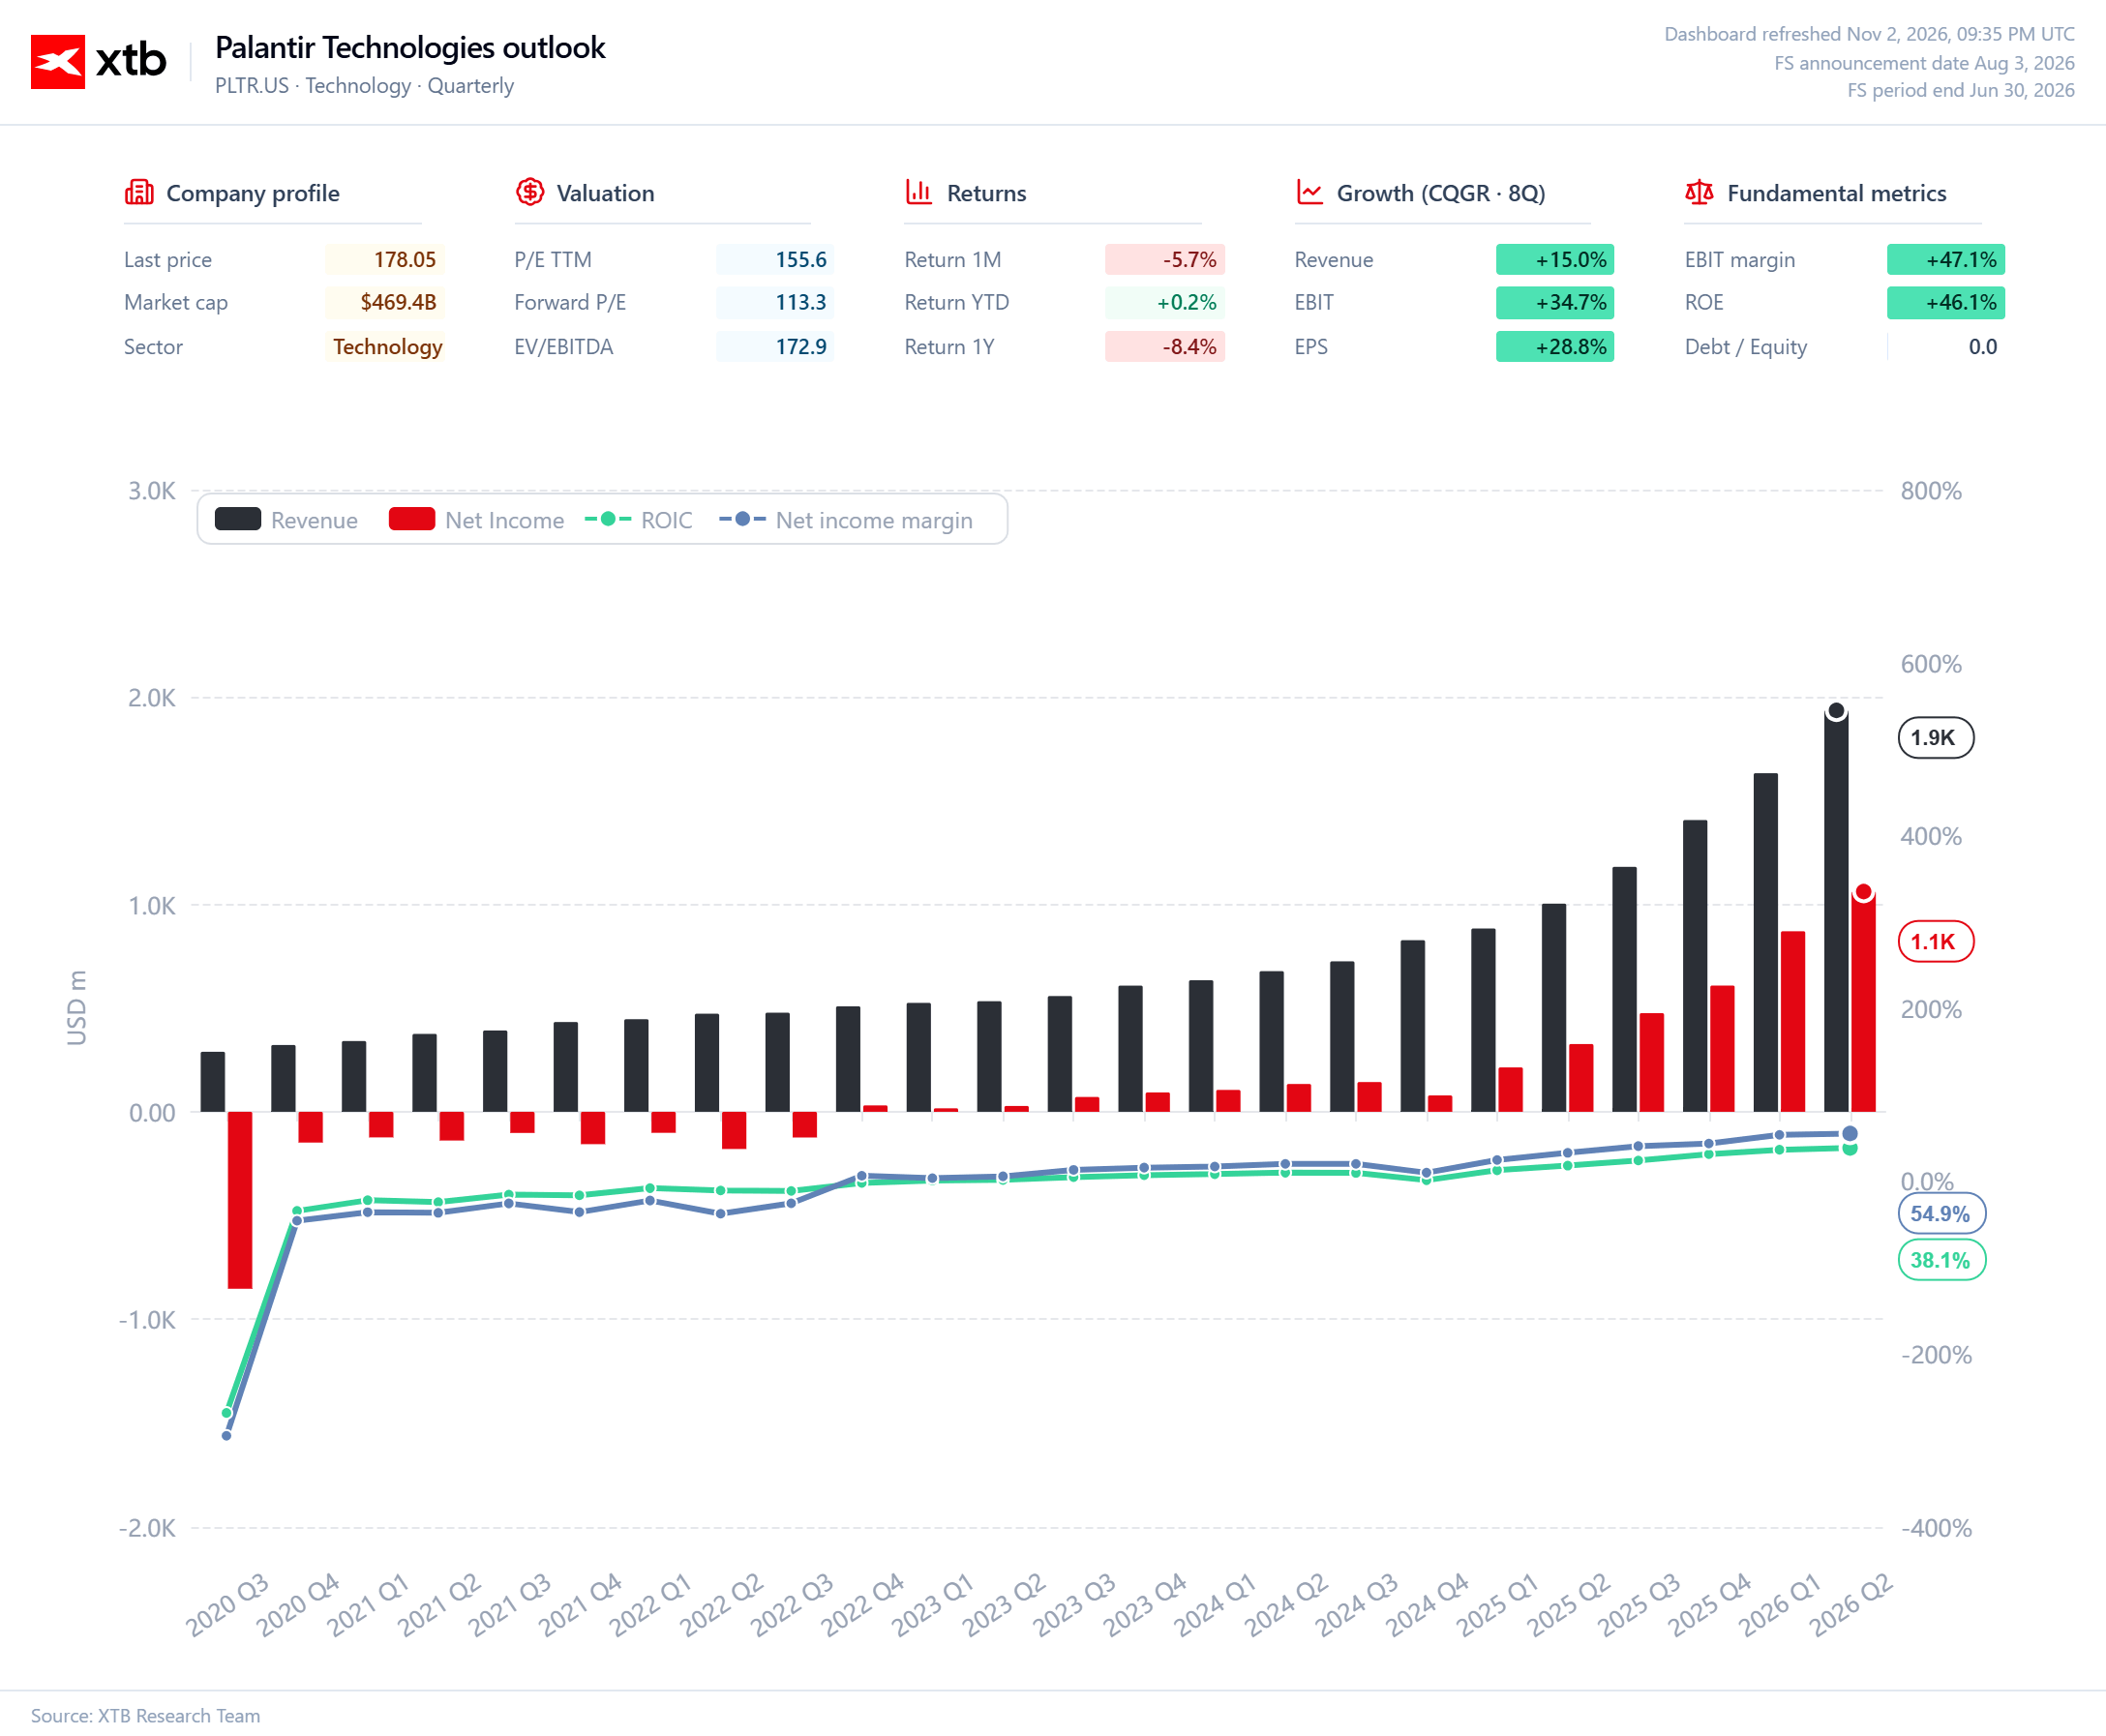
Chart 1. Palantir: Revenue, net income and equity valuation
Over recent years, Palantir has transformed from a loss-making business into a company generating rapidly growing revenue and positive earnings, reaching approximately $1.9 billion in revenue and $1.1 billion in net income in Q2 2026. Net profit margin increased to 54.9%, while return on invested capital (ROIC) reached 38.1%, indicating a substantial improvement in capital efficiency and overall profitability. Particularly impressive is the fact that improving profitability has been accompanied by accelerating revenue growth, suggesting strong demand for Palantir's analytics software and artificial intelligence solutions. From an investor's perspective, however, the main constraint remains the company's price-to-earnings (P/E) ratio of 155.6 and forward P/E of 113.3, indicating that the market is already pricing in considerable future earnings growth. The lower forward P/E relative to the trailing multiple reflects expectations of rising profits, but it does not automatically imply an attractive valuation, given that the projected multiple still exceeds 100 times annual earnings. Palantir combines exceptional fundamental growth with extremely demanding investor expectations, meaning its future share price performance will depend not only on revenue and earnings growth but also on the company's ability to consistently outperform analysts' forecasts.
Source: XTB Research
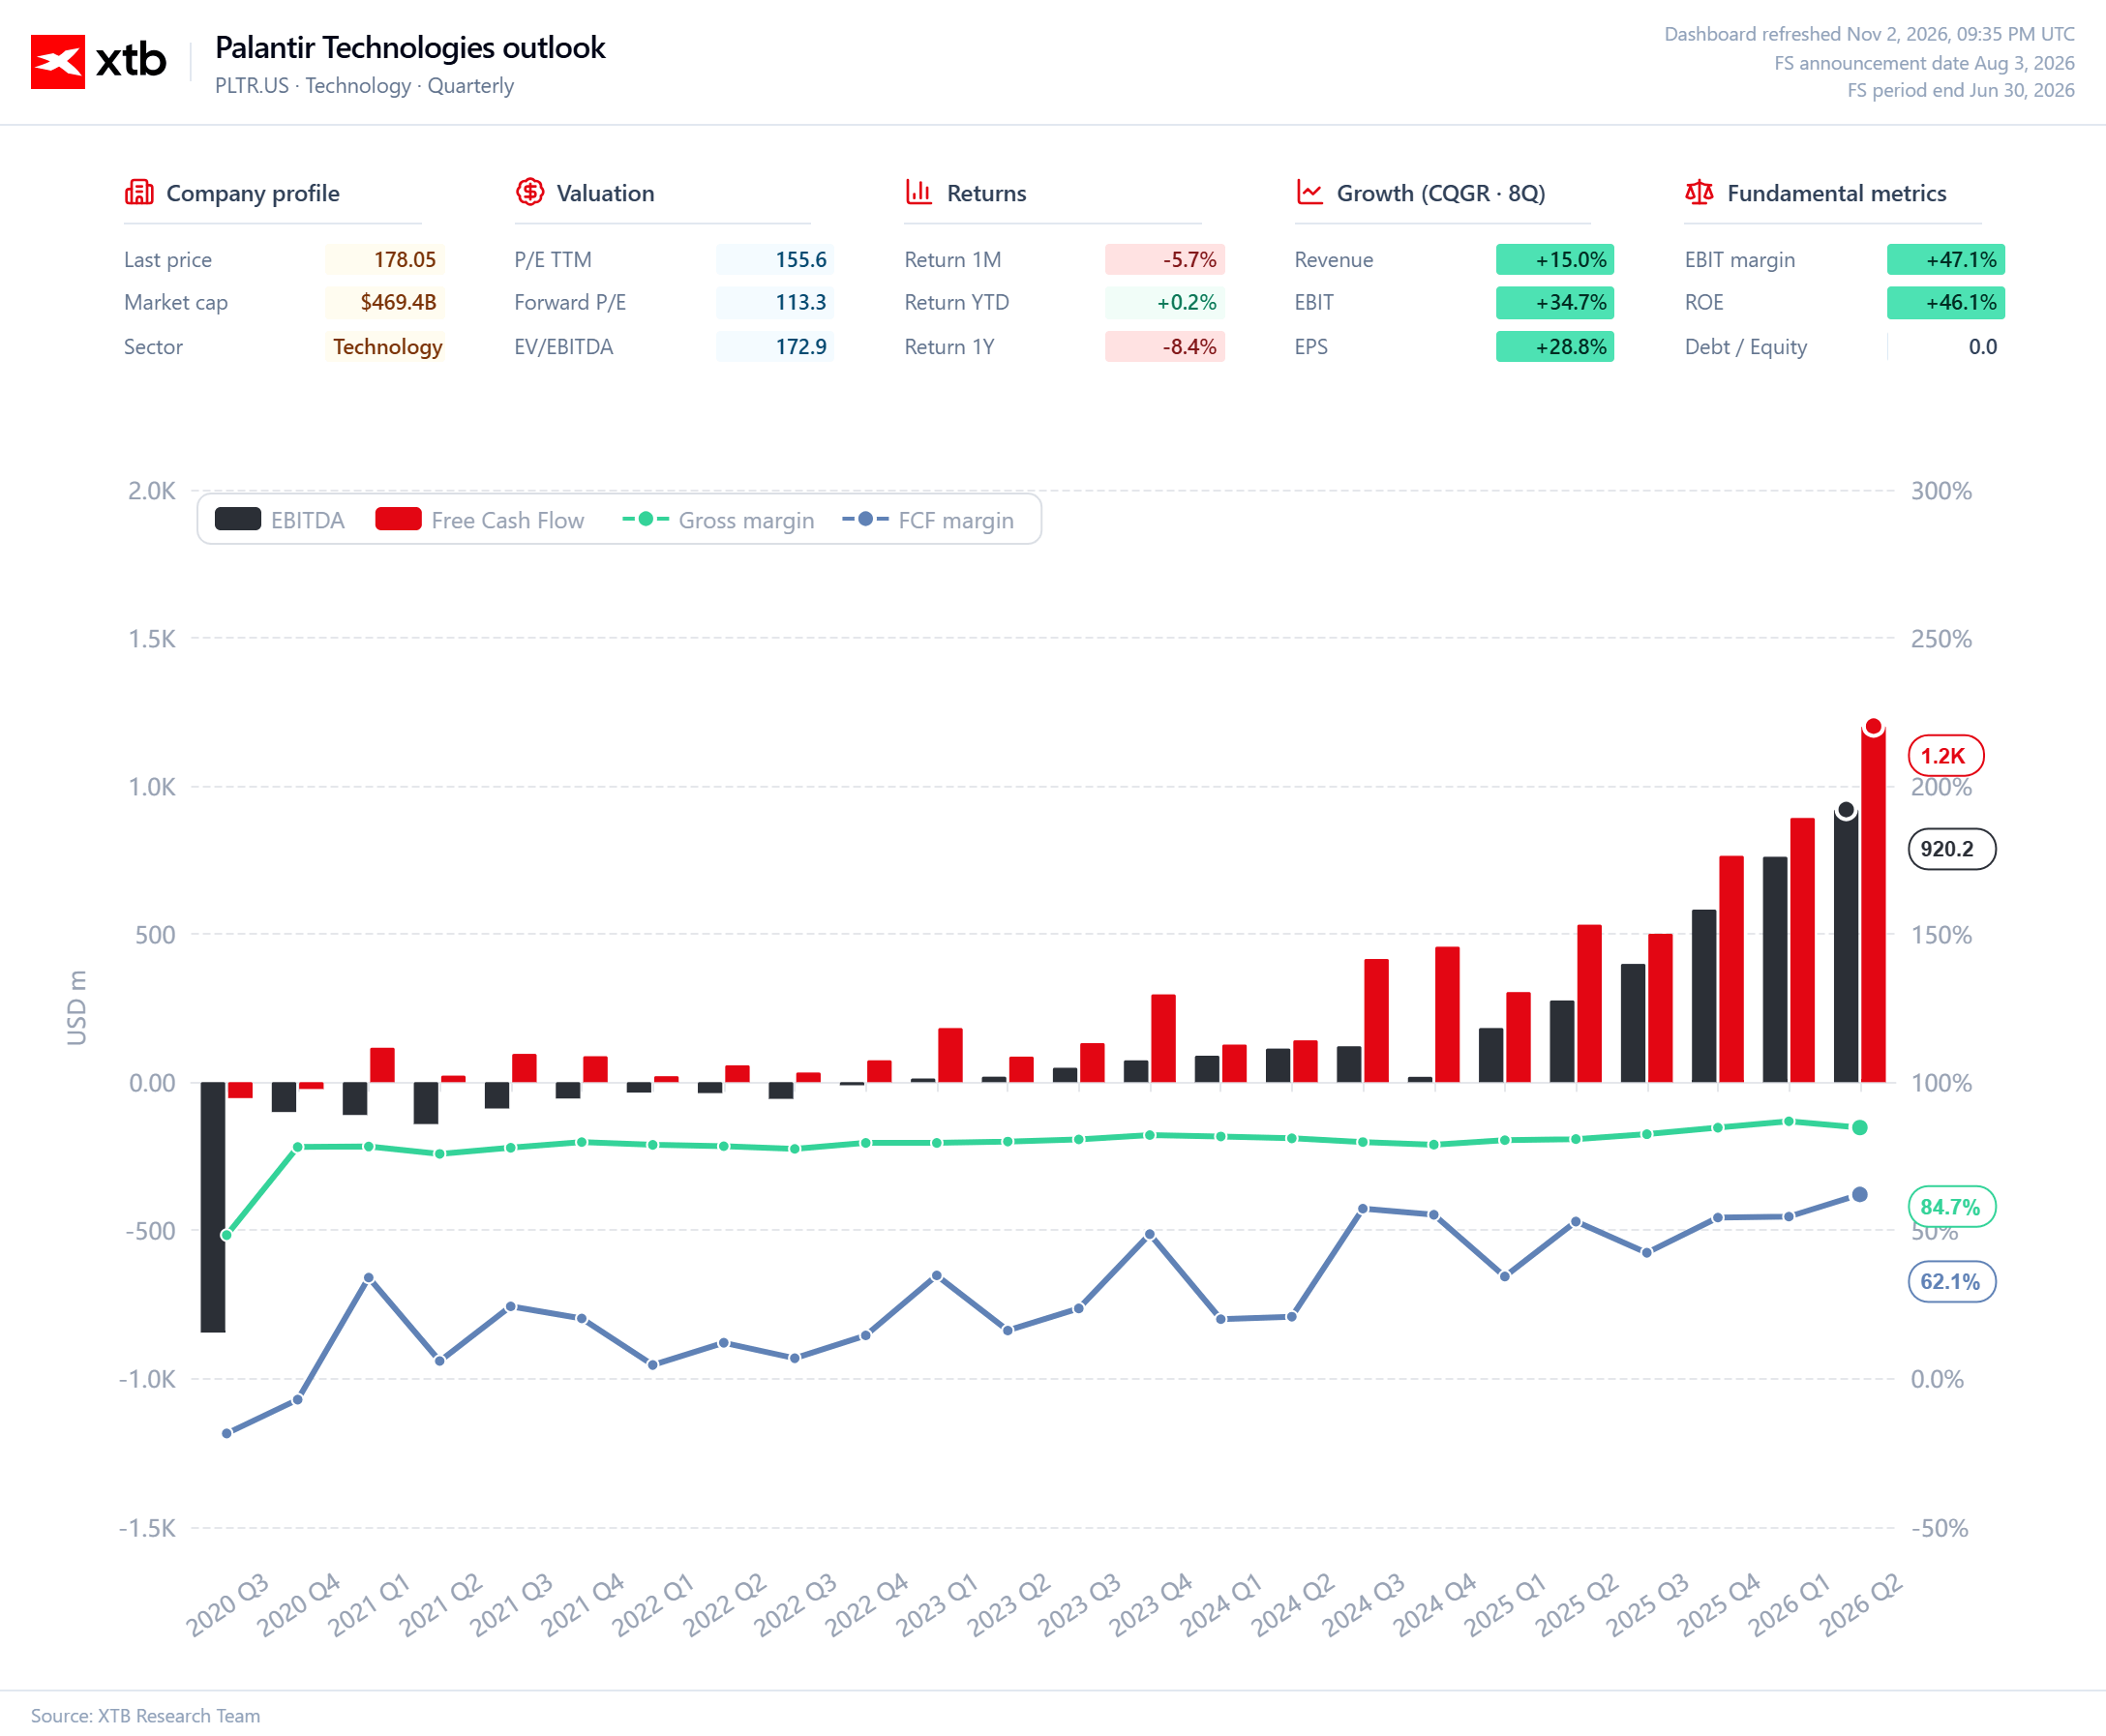
Chart 2. Palantir: EBITDA, free cash flow and profitability (as of the close on November 2, 2026)
Palantir has steadily increased its cash flow generation since 2023, with free cash flow (FCF) reaching approximately $1.2 billion in Q2 2026, compared with EBITDA of around $920 million. Particularly important is the improvement in FCF margin to 62.1% and the maintenance of gross margin at 84.7%, highlighting the scalability of the company's business model and its ability to convert rising revenue into cash. Free cash flow growth outpacing EBITDA growth suggests exceptionally strong cash conversion, although its sustainability requires closer examination of working capital movements and the impact of stock-based compensation. At the same time, an EV/EBITDA multiple of 172.9 indicates that investors are paying a substantial premium for expectations of continued earnings expansion. At such a demanding valuation, even strong EBITDA growth may prove insufficient to support further share price appreciation if business performance begins to fall short of market expectations. Palantir's fundamentals demonstrate an exceptional ability to generate cash, but its current valuation assumes sustained rapid growth for years to come, leaving limited room for disappointment.
Source: XTB Research

Apple beats Wall Street estimates 🔼 iPhone and Mac drive earnings, China disappoints



Daily Summary: A Rollercoaster Ride in the Commodities Market🚨Oil Drops 7%; Gold Rallies Over 2%💥



US Midterms preview


Alstom shares slump 25% in panic mode after the business guidance cut
This content has been created by XTB S.A. This service is provided by XTB S.A., with its registered office in Warsaw, at Prosta 67, 00-838 Warsaw, Poland, entered in the register of entrepreneurs of the National Court Register (Krajowy Rejestr Sądowy) conducted by District Court for the Capital City of Warsaw, XII Commercial Division of the National Court Register under KRS number 0000217580, REGON number 015803782 and Tax Identification Number (NIP) 527-24-43-955, with the fully paid up share capital in the amount of PLN 5.869.181,75. XTB S.A. conducts brokerage activities on the basis of the license granted by Polish Securities and Exchange Commission on 8th November 2005 No. DDM-M-4021-57-1/2005 and is supervised by Polish Supervision Authority.