


POET is a Canadian company that has been trying, with mixed results, to establish itself in the photonics industry, which has recently been gaining importance in the investment “race for AI”.
As of today, POET has a market capitalization of around USD 1.3 billion, revenue of about USD 1.7 million, and a net loss of as much as USD 75 million.
In most cases, companies like POET would remain on the fringes of the market, mentioned mainly in the context of an assumed impending restructuring mechanism. However, a set of fairly unique circumstances has pushed the company into the basket of so called “meme stocks”, which can often act as a cushion that softens the fall from price level down to the company’s fundamentals.
Quo vadis
Like many similar companies, POET entered the public market in 2020, quickly multiplied its valuation, and then, after 2022 arrived, lost most of its value in response to the re pricing of the cost of capital.
Most investors who recognize the company’s name likely heard about it in April or May 2026, when rumors of a deal with Marvell sent the company’s valuation up by several hundred percent.
The rumors turned out to be true, but a Marvell subsidiary terminated the agreement because the CEO failed to comply with the confidentiality terms of the agreement between the companies. This is an especially interesting phenomenon because the CEO’s response that constituted the breach of confidentiality was a response to a report by short seller fund WolfPack Research.
POET price chart (D1)
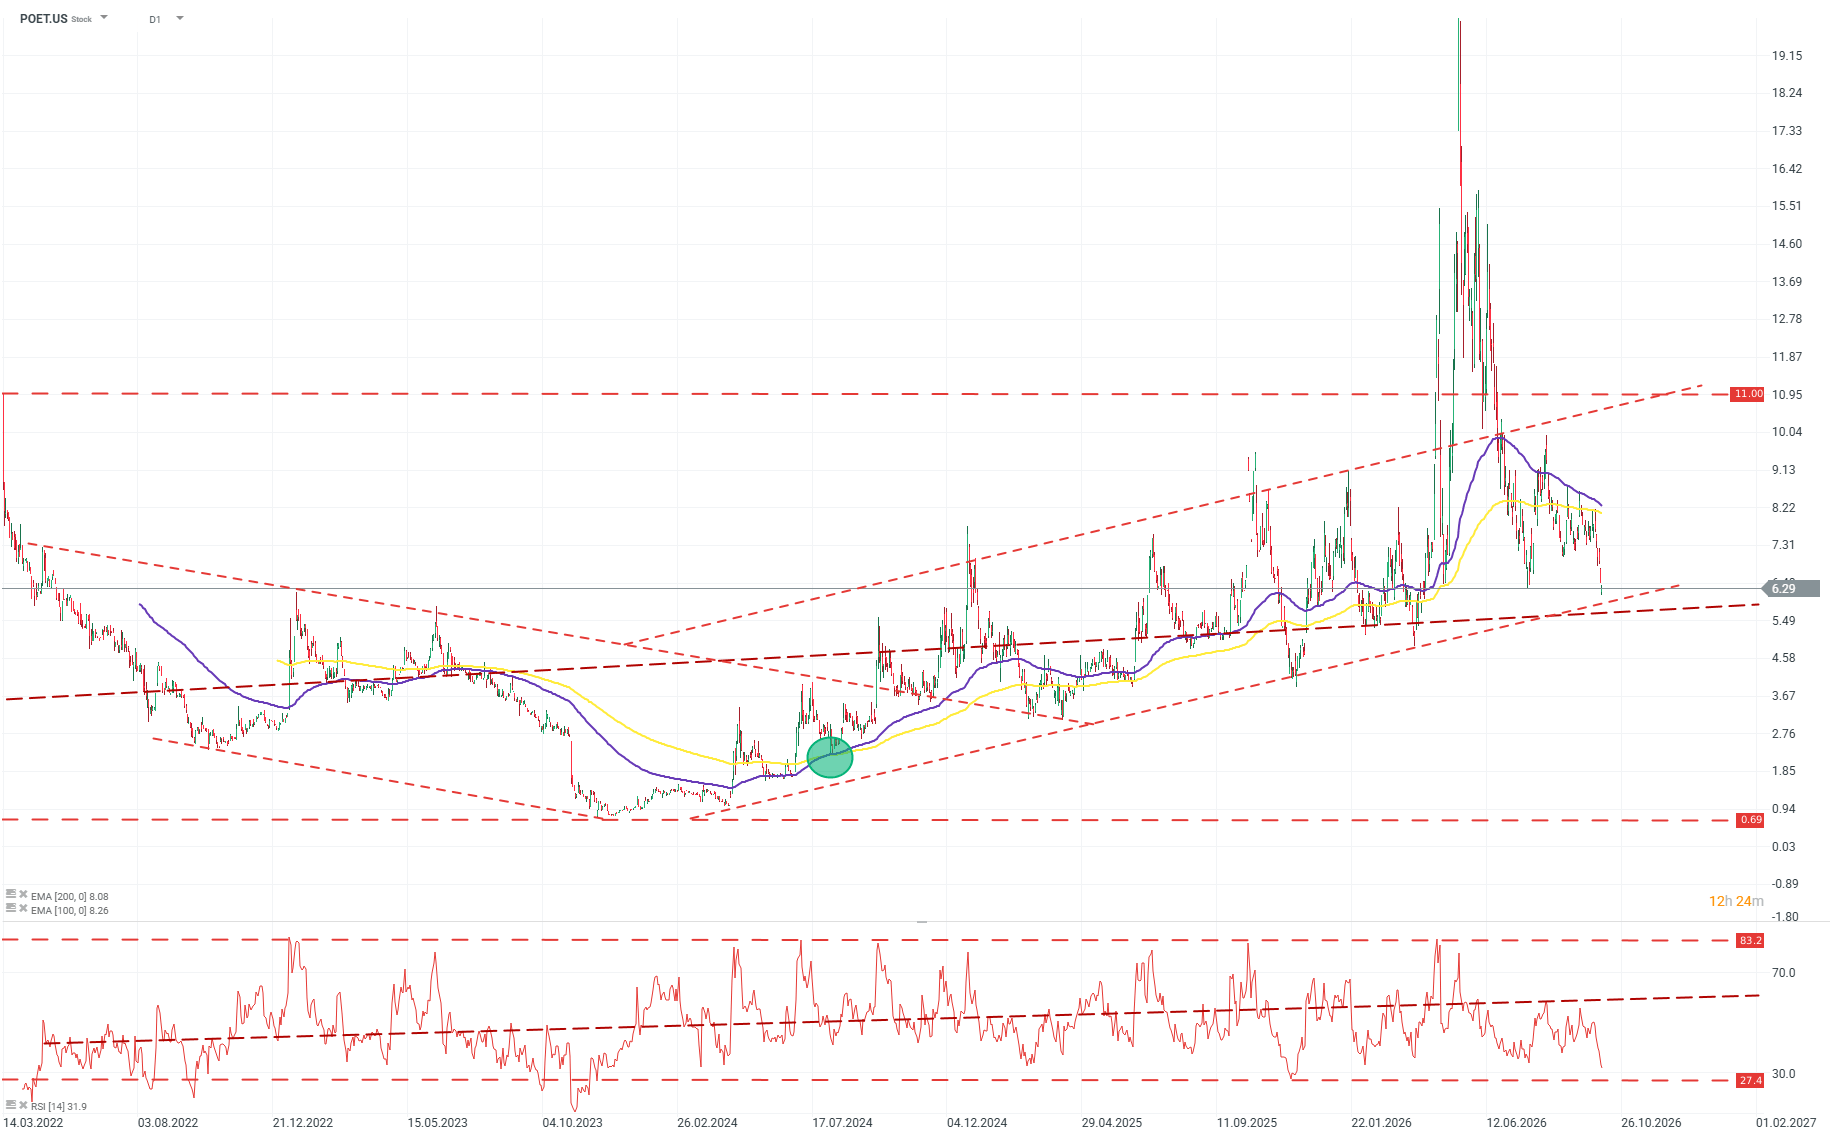
Several months have passed since the “drop” from around USD 17 per share to current levels between USD 9 and USD 6, and the market has had time to cool off and often to forget about the company. In a month, the company will publish its financial results for the next quarter, which may provoke a return of some interest in the stock. Source: xStation5
Expectations are not particularly high, but they may still prove challenging for the company. The market expects year over year revenue growth from USD 0.5 million to USD 0.7 million and a reduction in losses to around -0.05 EPS.
POET as a company is in an interesting position which, despite the rather grim situation on the chart and in the financial data, is not hopeless. From the current valuation level, the balance of opportunity versus risk is starting to look favorable.
WolfPack Research accused the company of having no real product platforms, pointing for example to the fact that the company repeatedly changed its area of specialization to whatever, in the author’s view, was currently “popular” among investors. However, this thesis looks more like a series of cognitive errors stacked on top of each other than a high quality analysis.
The company has a functioning “Optical Interposer” platform, an ecosystem of optical relays and switches ultimately intended for AI data centers. When analyzing the company through the lens of its products, the company’s outlook becomes much more optimistic than current figures suggest.
The system sold by POET is compact and features extensive customization of deployment, making it a highly versatile and attractive solution in many more or less niche applications.
More important than the product itself, however, may be the market in which the company operates. While competition in the market is formidable, including Broadcom, Lumentum, Marvell, and Coherent, it must be stated clearly, as Lumentum recently confirmed, that demand for photonics solutions currently exceeds supply by approximately an order of magnitude.
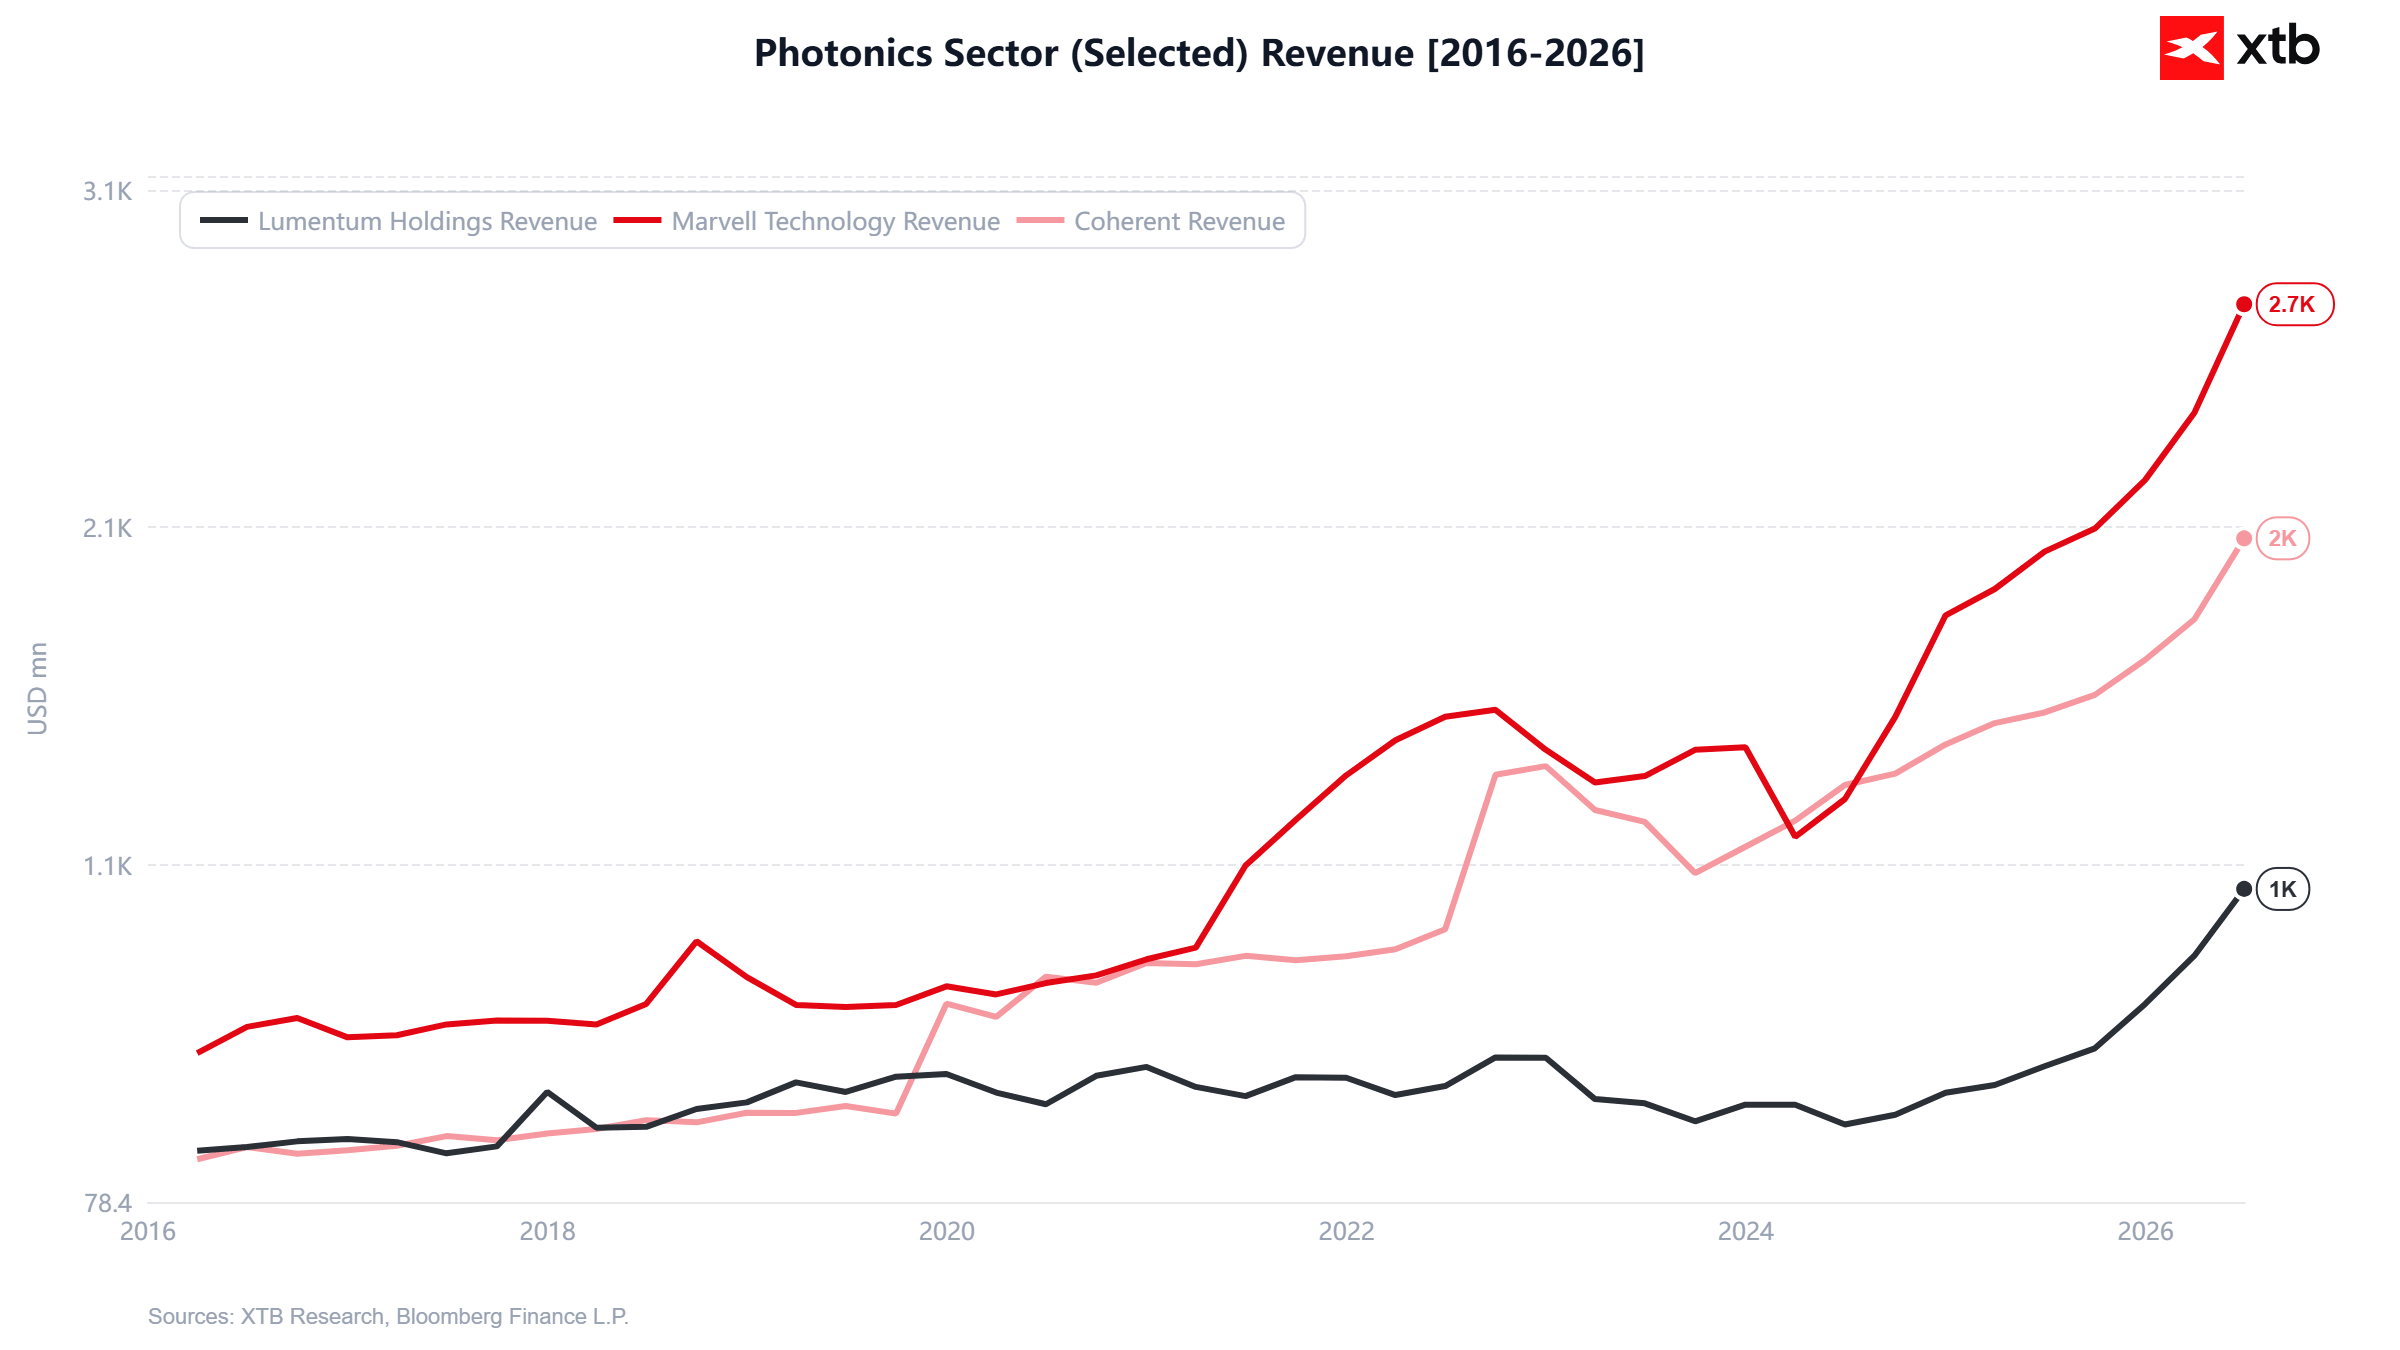
POET effectively operates in a market and an industry where the customer needs everything and needs it “yesterday”. If POET manages to diversify its customer base, win the sector’s trust, and optimize its production yield, then management’s target of around USD 300 million in revenue in 2028 would not look particularly distant. Based on a discounted cash flow model, such a scenario would justify not only today’s valuation but also a very significant increase in the share price.
What to watch
For every opportunity at POET, there is currently at least one threat. Key items to watch in the coming quarters will be:
- Sales: How the company is doing in acquiring customers, retaining and expanding existing relationships, and managing its backlog.
- Yield: Achieving the right production yield for advanced components is the company’s economic make or break. This is the company’s biggest technical challenge and must be addressed for the product to move beyond the late prototype phase.
- Financing: The company has generated losses consistently for nearly its entire existence. This is not particularly surprising for tech small caps, but for the investment thesis to play out, it is crucial to monitor the company’s capital reserves. The risk is huge but of low probability. The June balance sheet shows strong financial buffers and resources for continued development. It is management’s job to keep it that way.



US Open: Earnings season kicks off on a high note (13.10.2026)


🖥️Chart of the Day - US100: Is the KOSPI crash a foretaste of Nasdaq's troubles?



Morning Wrap: Tech Crash in Asia and Hawkish Central Banks in the Shadow of an Oil Shock (13.10.2026)


Morning Wrap: Oil cheaper despite attacks on Saudi Arabia, markets await CPI (12.10.2026)
This content has been created by XTB S.A. This service is provided by XTB S.A., with its registered office in Warsaw, at Prosta 67, 00-838 Warsaw, Poland, entered in the register of entrepreneurs of the National Court Register (Krajowy Rejestr Sądowy) conducted by District Court for the Capital City of Warsaw, XII Commercial Division of the National Court Register under KRS number 0000217580, REGON number 015803782 and Tax Identification Number (NIP) 527-24-43-955, with the fully paid up share capital in the amount of PLN 5.869.181,75. XTB S.A. conducts brokerage activities on the basis of the license granted by Polish Securities and Exchange Commission on 8th November 2005 No. DDM-M-4021-57-1/2005 and is supervised by Polish Supervision Authority.