

- Micron Technology reported Q4 FY2026 revenue of 54.23 billion USD, beating market expectations.
- Adjusted earnings per share reached 33.42 USD, exceeding Wall Street estimates of 31.83 USD.
- Strong AI infrastructure demand drove a gross margin of 87 percent for the quarter.
- Micron projected Q1 FY2027 revenue of 61.5 billion USD, surpassing analyst consensus.
Record-breaking revenue, gross margin reaching 87%, and guidance significantly exceeding Wall Street expectations. Micron Technology presented its financial results for the fourth fiscal quarter of 2026, which completely surpassed analysts' estimates and bodes well ahead of upcoming AI-related earnings releases in the coming weeks. Demand for memory chips driven by the construction of artificial intelligence (AI) infrastructure and the transition into the "Super Intelligence" era proved so massive that the company's website stopped working for several minutes following the report's release. Investor reaction in after-hours trading was immediate. According to some reports, Micron's share price surged by as much as 15%, while more realistic estimates from Yahoo Finance or CNBC indicate a 2% gain, following a temporary negative initial reaction.
Key Highlights & Figures (Q4 & FY2026)
- Q4 FY26 Revenue: $54.23 billion (up 379% YoY from $11.32 billion) vs. market consensus of $51.07 – $51.49 billion.
- Adjusted Earnings Per Share (Non-GAAP EPS, Q4): $33.42 compared to Wall Street expectations of $31.61 – $31.83 (and $3.03 a year earlier).
- Adjusted Gross Margin (Q4): 87.0% Non-GAAP (vs. market consensus of 86.2%).
- Adjusted Operating Income (Q4): $44.64 billion (operating margin of 82.3%).
- Operating Cash Flow (Q4): $43.97 billion (vs. $5.73 billion in Q4 FY25 and market forecast of $33.87 billion).
- Business Segment Results in Q4:
- Core Data Center: $18.00 billion (+1,042% YoY, operating margin 85%).
- Cloud Memory: $16.28 billion (+258% YoY, operating margin 76%).
- Mobile & Client: $13.11 billion (+249% YoY, operating margin 85%).
- Automotive & Embedded: $6.82 billion (+376% YoY, operating margin 88%, massive upside surprise vs. forecast of $4.73 billion).
- Full-Year FY2026 Summary:
- Full-Year Revenue: $133.19 billion (up from $37.38 billion in FY25).
- Full-Year Non-GAAP Net Income: $86.76 billion (Non-GAAP EPS: $75.52).
- Annual Free Cash Flow (FCF): $62.31 billion.
Official Q1 FY2027 Guidance:
- Revenue: $61.5 billion (± $1.5 billion) vs. market consensus around $56.3 – $56.77 billion.
- Non-GAAP EPS: $38.15 (± $1.00) vs. analyst expectations of $36.02 – $36.05.
- Non-GAAP Gross Margin: approx. 86.25%
Earnings Commentary and Broader Outlook
End of the Cyclical Era — Structural Shift in the Memory Market
The published report definitively refutes Wall Street's traditional narrative regarding the boom-and-bust cycle in the semiconductor industry. Maintaining a gross margin at an astronomical 87.0% on such a massive sales scale proves that any cooling of price dynamics was a structural change rather than a sign of weakening demand. Demand for HBM memory and fast SSDs for data centers exceeds production capacities and will remain tight throughout calendar year 2027.
Incredible Operational Efficiency and Breakthrough in Automotive
While all segments recorded triple-digit growth (and Core Data Center achieved a 4-digit surge), the Automotive & Embedded segment ($6.82 billion) warrants special attention. Delivering results over $2 billion higher than analyst expectations indicates that the compute chip boom has gained a second growth engine in Edge AI, autonomous systems, and advanced AI workstations (where Micron secured contracts with all key OEMs).
Balance Sheet Strength and Capital Return to Shareholders
Micron ended the fiscal year with an astronomical $73.48 billion in cash and liquid assets. Generating over $62 billion in free cash flow (FCF) in 12 months grants management virtually limitless capacity for further investments (including $10 billion for the Boise, Idaho R&D center) alongside ample headroom for an aggressive share buyback program.
Impact on the Electronics Market and Stock Valuation
Reallocating factory capacities toward AI chips negatively impacts the availability of standard memory, driving price increases for consumer devices (e.g., Apple's $100 price increase for the iPhone 18 Pro). From a stock market perspective, however, Micron remains exceptionally attractively valued. With median analyst price targets sitting at $1,510 (+41.8% from current levels) and a forward P/E ratio in single digits at ~7x, the market continues to discount the giant with caution. These results provide a strong catalyst for a re-rating of the stock.
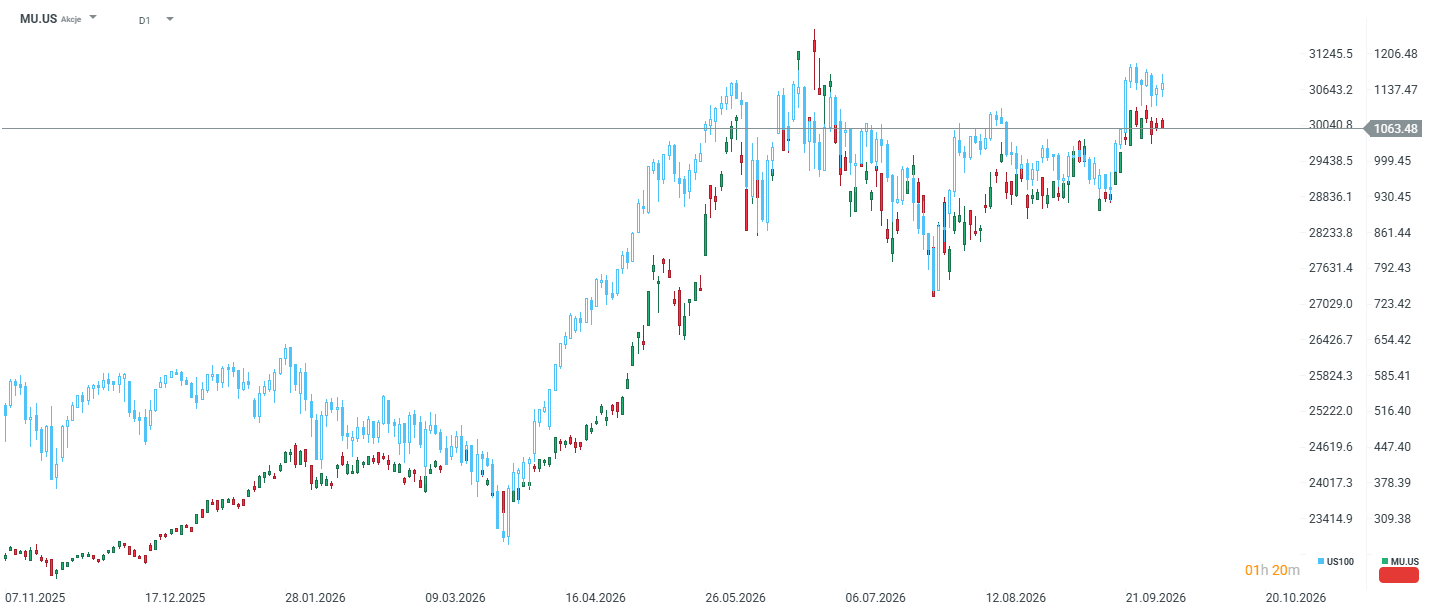
It is also worth remembering that during the press conference, we will learn more details regarding the company's planned capital expenditures (CAPEX). Currently, the stock is trading in after-hours around $20 higher than today's close, though given these results, tomorrow's market reaction should arguably be much stronger.



📊Daily Summary: PCE inflation slowdown brings relief to Wall Street, but oil continues gains despite return of supply



Morning Wrap: AI drives Nikkei 225 gains, oil prices decline (30.09.2026)


Daily Summary: Lack of progress in negotiations weighs on Wall Street and precious metals (28.09.2026)


US Open: Wall Street starts the week in red (28.09.2026)
This content has been created by XTB S.A. This service is provided by XTB S.A., with its registered office in Warsaw, at Prosta 67, 00-838 Warsaw, Poland, entered in the register of entrepreneurs of the National Court Register (Krajowy Rejestr Sądowy) conducted by District Court for the Capital City of Warsaw, XII Commercial Division of the National Court Register under KRS number 0000217580, REGON number 015803782 and Tax Identification Number (NIP) 527-24-43-955, with the fully paid up share capital in the amount of PLN 5.869.181,75. XTB S.A. conducts brokerage activities on the basis of the license granted by Polish Securities and Exchange Commission on 8th November 2005 No. DDM-M-4021-57-1/2005 and is supervised by Polish Supervision Authority.