


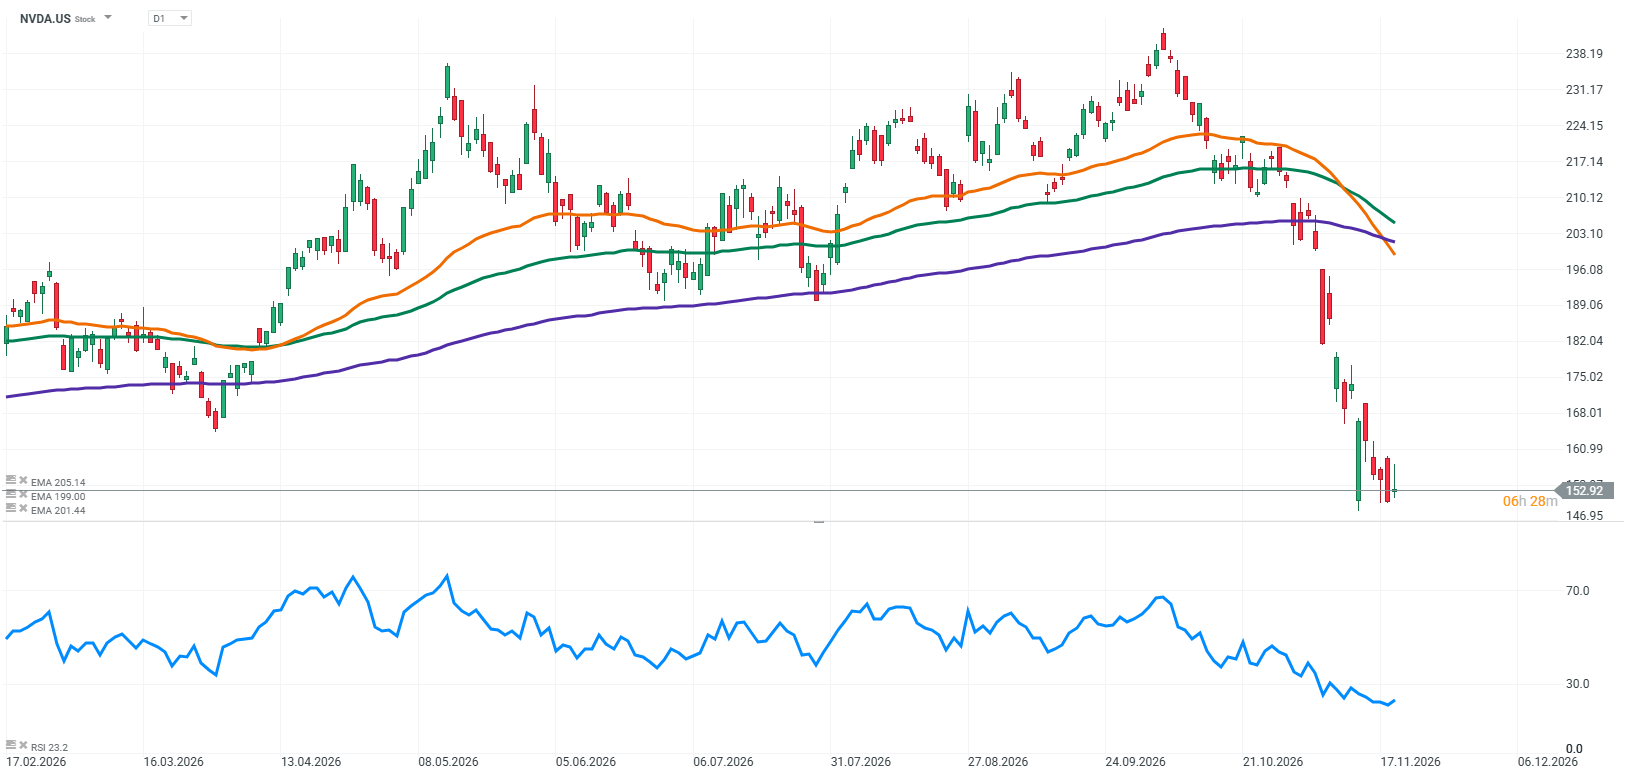
In recent weeks, the semiconductor sector has come under significant pressure, along with the companies that have driven the technology stock market rally over the past few years. Investors have begun questioning the sustainability of the artificial intelligence boom. Inflation, high interest rates and the rising costs of expanding computing infrastructure have fuelled concerns that the largest cloud service providers may eventually scale back their spending. This would represent a major shift for the market, as investments in data centres have become one of the main drivers of growth across the technology sector.
NVIDIA’s latest earnings report, however, provided arguments that are difficult to reconcile with the idea of a significant slowdown in demand. The company once again delivered record revenue, its Data Center segment maintained impressive growth, and its guidance for the following quarter showed that management continued to expect further expansion. Demand for computing power remains enormous, while the development of AI infrastructure continues to require increasingly advanced chips. Despite these strong figures, the market reaction was surprisingly muted. Share price performance is increasingly reflecting uncertainty surrounding the departure of Jensen Huang, the long-standing CEO and the person who has shaped the company's strategic direction for years.
NVIDIA therefore finds itself in an unusual position. Its business is sending strong signals, while its leadership is facing a major crisis. Investors must decide whether problems at the top of the organisation could threaten the competitive advantage built over many years or whether they will remain primarily a source of short-term uncertainty.
Latest Quarterly Results
NVIDIA’s third-quarter fiscal 2027 results can hardly be interpreted as a sign of weakening business conditions. The company generated $115.8 billion in revenue, representing a 103% increase year over year and 20% growth compared with the previous quarter. The largest contribution came from the Data Center segment, which generated $107.6 billion. Revenue in this segment increased by as much as 110% year over year. This is particularly important because it is the area that best illustrates the scale of investment in the infrastructure required to train and run artificial intelligence models.
Record sales were accompanied by equally impressive profitability. Operating income reached $77.5 billion, while net income amounted to $65.3 billion. Earnings per share came in at $2.70. Gross margin remained at 74.8%. These figures demonstrate that NVIDIA is not only selling an increasing number of chips but is also capable of maintaining exceptionally high profitability while rapidly expanding its business.
The outlook is even more impressive. For the fourth quarter of fiscal 2027, the company expects revenue of approximately $130 billion, with a margin of error of $3 billion. This would represent another record and further growth on top of an already exceptionally high revenue base. It is worth noting that this forecast does not include revenue from Data Center computing products sold to China. NVIDIA is therefore not basing its expectations on the assumption that export restrictions will be eased in the near future.
NVIDIA's key Q3 FY2027 results:
-
Revenue: $115.8 billion, up 103% year over year.
-
Data Center revenue: $107.6 billion, up 110% year over year.
-
Gross margin: 74.8%.
-
Operating income: $77.5 billion.
-
Net income: $65.3 billion.
-
Earnings per share: $2.70.
-
Q4 FY2027 revenue guidance: 130billion,withamarginof±3 billion.
-
Expected gross margin for the next quarter: 71–72%.
-
Shareholder returns through share buybacks and dividends in Q3: $28.1 billion.
Another important element of the report is the development of the next generation of infrastructure. The company announced the start of shipments of its Vera Rubin NVL72 systems, which are expected to represent the next stage in its product offering for the most demanding AI applications. NVIDIA is already preparing its next platform, aiming to sustain demand from customers expanding their data centre infrastructure.
The report paints a picture of a business that continues to grow at a pace rarely seen among the world's largest companies. However, it does not resolve all market concerns. Strong revenue growth does not guarantee that current AI investments will prove profitable for every customer, and NVIDIA's outlook remains dependent on continued spending on infrastructure. Despite these reservations, it is difficult to argue, based on the latest figures, that demand for the company's products is clearly slowing. At the operational level, NVIDIA continues to deliver results that contradict such a scenario.
Financial Analysis
NVIDIA's greatest strength today is its ability to scale its business while maintaining exceptionally high profitability. In the third quarter of fiscal 2027, revenue reached $115.8 billion, while gross profit amounted to $86.7 billion. The company generated $77.5 billion in operating income and $65.3 billion in net income. Particularly noteworthy is the fact that revenue increased by 103% year over year, while operating income grew by 115%. NVIDIA is not only selling more products but is also increasing its profits faster than its overall business.
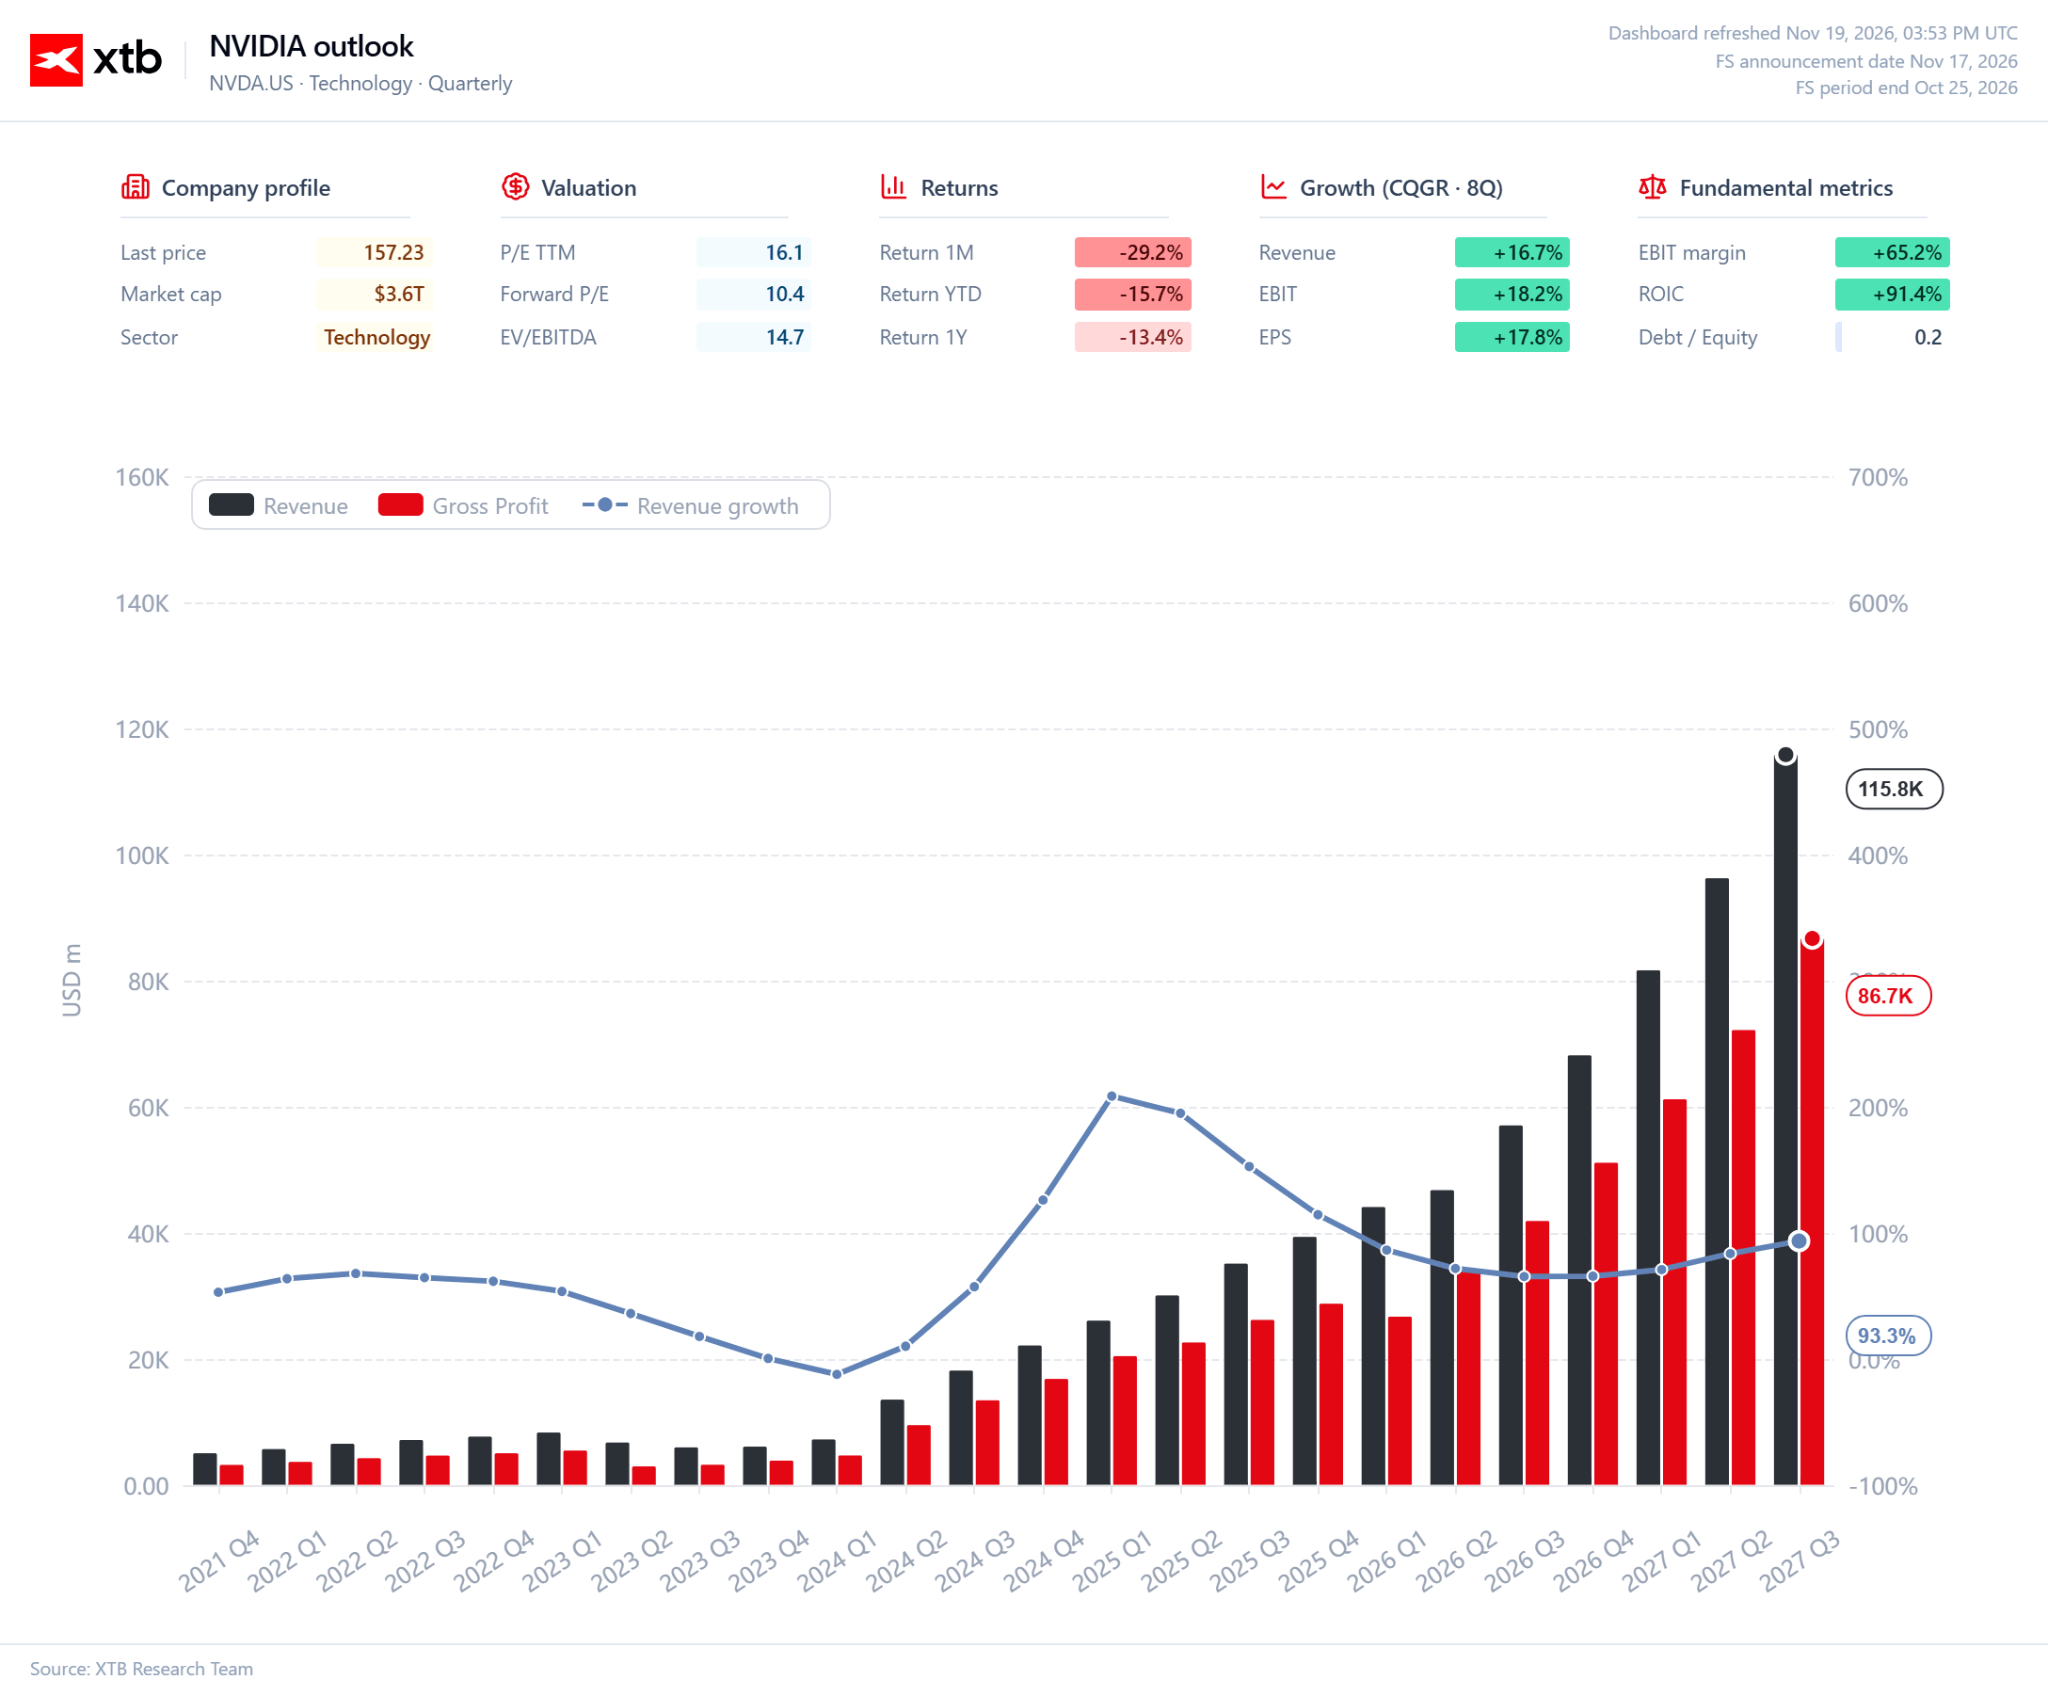
It is also worth looking at the broader picture. During the first nine months of fiscal 2027, the company's revenue reached $293.7 billion, compared with $147.8 billion a year earlier. Operating income increased from $86.1 billion to $194.8 billion over the same period. This pace demonstrates that we are not dealing with a one-off earnings spike in a single quarter. NVIDIA is expanding its business on an enormous scale, and revenue growth is translating into even faster profit growth.
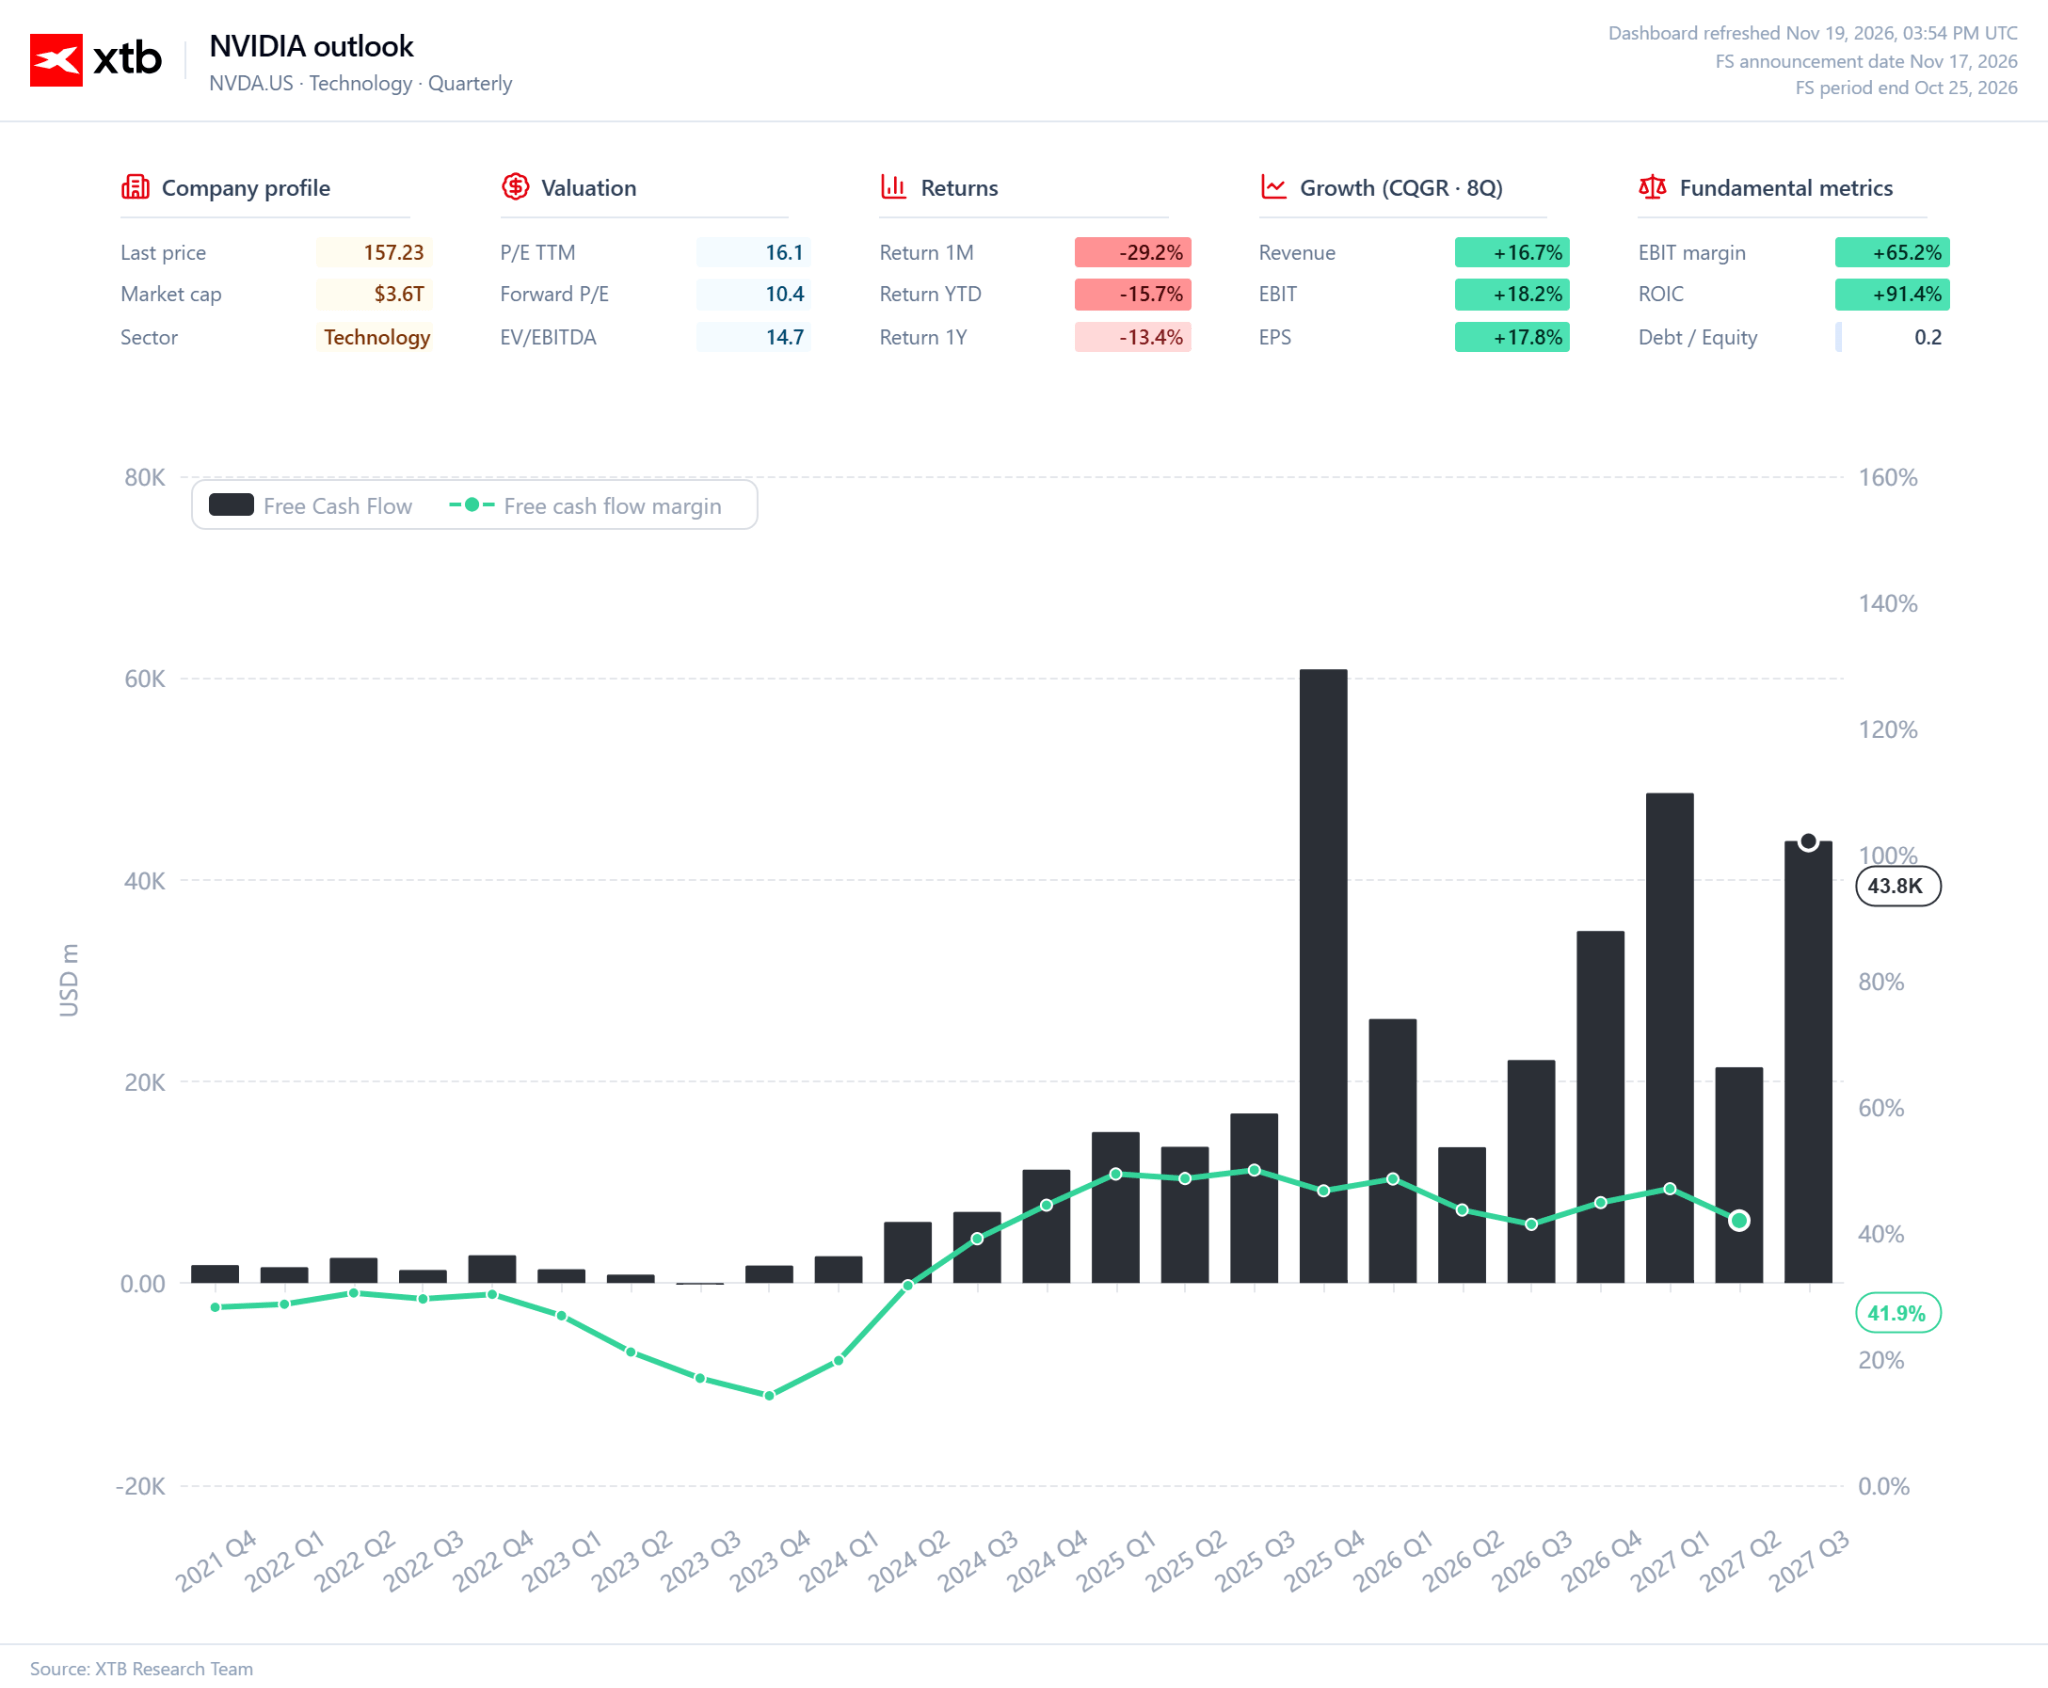
Cash flow is equally impressive. In the third quarter alone, operating activities generated $48.3 billion in cash, while free cash flow reached $43.8 billion. During the first nine months of fiscal 2027, FCF had already reached $113.7 billion, almost twice the amount recorded in the corresponding period of the previous year. This is one of the most important aspects of the investment case. NVIDIA does not need to finance its expansion exclusively through external capital. Its business generates enormous amounts of cash that can be used to develop new technologies, expand its ecosystem and reward shareholders.
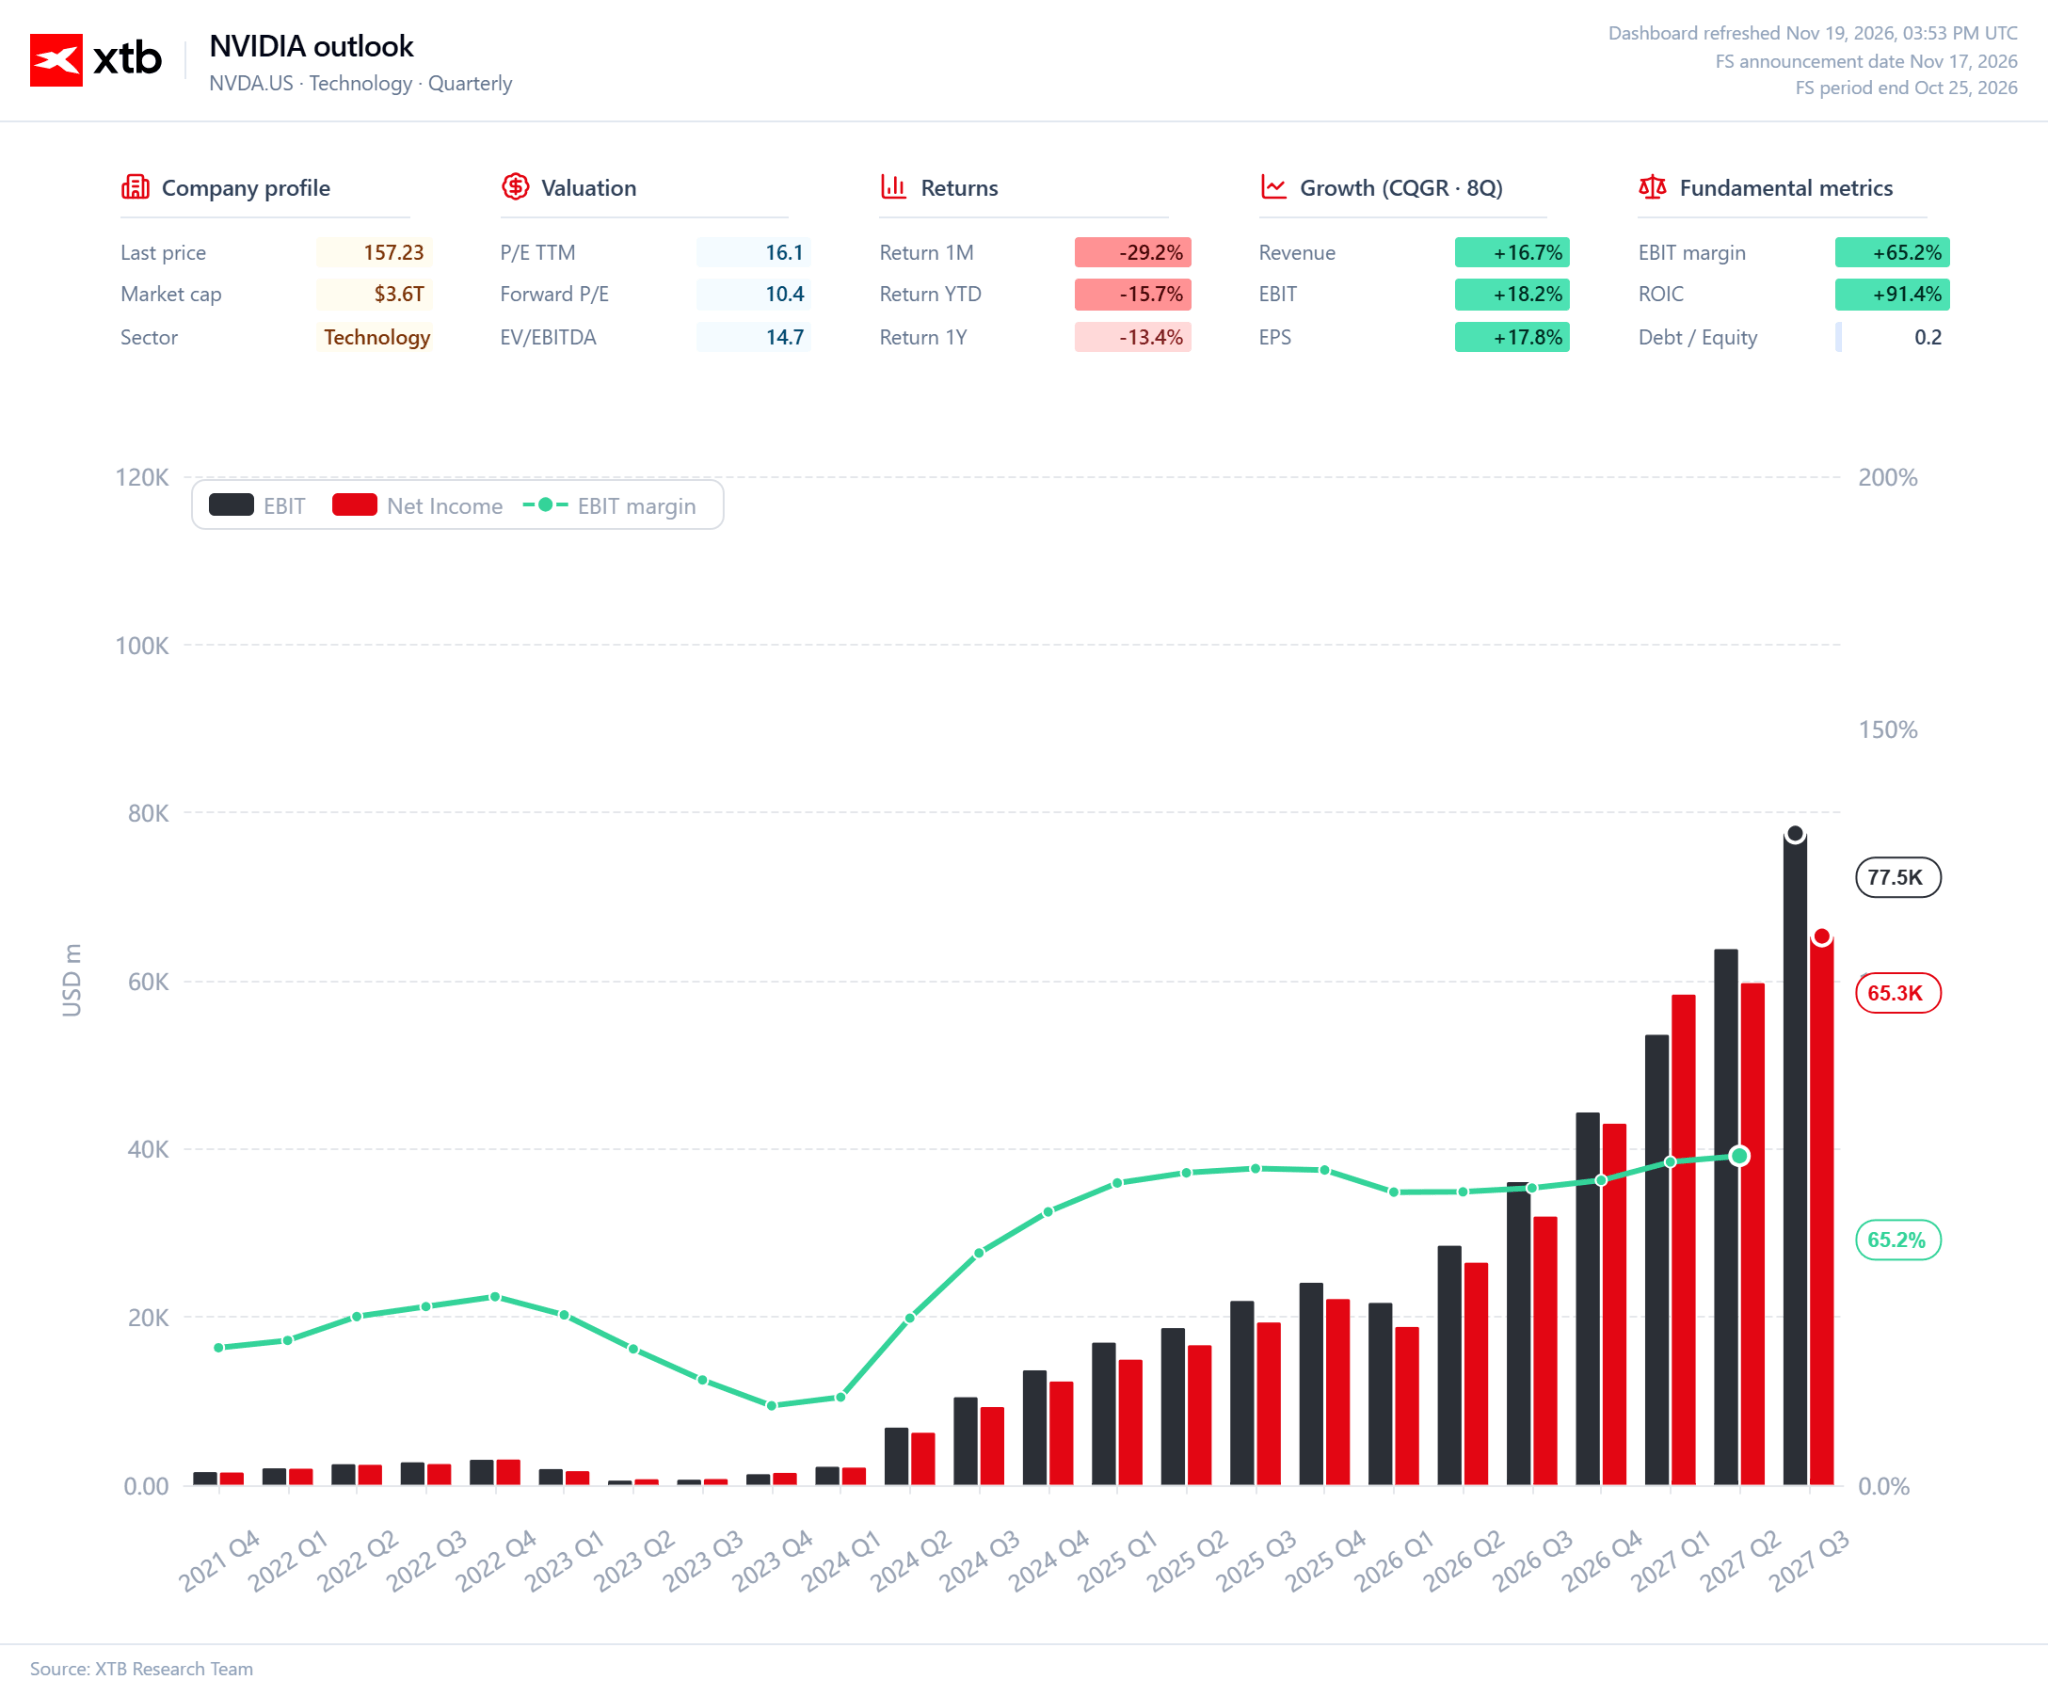
The scale of growth also requires increasingly substantial investment. Research and development expenses amounted to $7.5 billion in the third quarter, compared with $4.7 billion a year earlier. Nevertheless, the company more than doubled its operating income. This is an important characteristic of NVIDIA's business model: the company can invest heavily in successive generations of chips and computing platforms without sacrificing its exceptionally high profitability. Development costs are rising, but revenue and profits are growing even faster.
The balance sheet also reflects a company with substantial financial resources. At the end of the quarter, NVIDIA held $29.1 billion in cash and $24.4 billion in marketable debt securities. Long-term debt stood at $32.4 billion. This does not mean the company has no financial obligations, but the scale of its accumulated resources gives it considerable financial flexibility. NVIDIA can continue the expensive technological race, develop new platforms and respond to market changes without constantly relying on external financing.
The most important conclusion from these figures concerns the company's underlying growth model. NVIDIA has reached a scale at which successive quarters generate tens of billions of dollars in additional revenue, while the company continues to maintain high margins and generate enormous cash flows. Its competitive advantage is not based solely on the popularity of its AI processors. It is built around an entire technological ecosystem encompassing chips, software, networking and complete data centre platforms. This makes it more difficult for competitors to win over customers and allows NVIDIA to benefit from successive stages of AI infrastructure expansion.
Of course, maintaining the current growth trajectory will not be easy. The revenue base is already enormous, and expectations for future results remain exceptionally high. Nevertheless, the latest financial statements demonstrate the company's extraordinary ability to scale. Its business is becoming larger, more profitable and increasingly cash-generative. This is a fundamental strength that should not be confused with short-term fluctuations in the share price.
The Jensen Huang Situation: More Than Just a CEO Departure
Jensen Huang's departure represents a far more serious event for NVIDIA than an ordinary change in the CEO position. He led the company's development for 33 years, built its market position and persuaded its largest customers to adopt successive generations of technology. His influence extended far beyond the management of day-to-day operations. Huang became the public face of the AI revolution, and his presentations and product announcements frequently shaped investor expectations for the entire sector. It is therefore hardly surprising that his sudden departure had such a significant impact on the company's share price.
The circumstances surrounding the decision are particularly challenging for NVIDIA. The situation involves allegations of extramarital relationships involving Huang, including contacts with Alice Huang, a former representative of one of the company's business partners. Reports have also emerged concerning suspicions among US authorities about her possible links to Chinese intelligence. At this stage, however, it is essential to distinguish established facts from unverified information. No public evidence has been presented that Alice Huang was acting on behalf of the Chinese government or that Jensen shared confidential information with her.
From a shareholder perspective, the central issue is not the personal scandal itself but its potential implications for corporate governance and the credibility of the company's leadership. NVIDIA operates in a sector of strategic importance to national security, and its products are subject to export restrictions. Under these circumstances, allegations concerning contacts with individuals who may have links to Chinese intelligence services carry particular weight. The company must deal with a reputational crisis while addressing questions about oversight at the highest levels of management.
The uncertainty is further compounded by the absence of a permanent successor. CFO Colette Kress, a long-standing executive with an in-depth understanding of the company's operations and financial position, has assumed the responsibilities of interim CEO. Her experience provides the organisation with a degree of stability during the transition. However, taking over Huang's full responsibilities will be considerably more difficult than simply overseeing day-to-day operations. The former CEO was responsible for the company's strategic direction, relationships with its largest customers and communicating NVIDIA's technological vision. Finding someone capable of combining all these competencies could take considerable time.
The market has not considered assurances about uninterrupted business operations sufficient. Even record quarterly results have failed to dispel concerns about the future of the company's leadership. During the post-earnings analyst call, the company did not provide convincing answers to questions surrounding Huang's departure, and it has yet to present a permanent succession plan. Over the coming months, investors will therefore focus on whether the new leadership can maintain the confidence of employees, customers and business partners.
NVIDIA Remains a Cornerstone of the AI Boom
The turmoil surrounding the company's leadership does not change NVIDIA's position as one of the key suppliers of infrastructure to the artificial intelligence market. The company continues to develop successive generations of computing solutions, and the start of shipments of its Vera Rubin systems should help it maintain its competitive advantage among customers expanding their data centres. Its strength comes not only from the performance of its chips but also from an ecosystem encompassing software, networking and complete computing platforms. For customers, this means access to solutions designed to work together, while switching suppliers would require costly adjustments to their entire infrastructure.
However, this competitive advantage will face increasingly serious challenges. AMD is developing its own processors, while the largest cloud service providers are designing chips tailored to their specific needs. The profitability of AI investments is equally important. Microsoft, Alphabet and Amazon are committing enormous resources to data centres, but if these investments fail to generate the expected returns, they may reduce the pace of further expansion. Additional constraints include energy availability, the ability to bring new facilities online and export restrictions.
A high-quality business does not automatically translate into an attractive stock investment. Record results and impressive profitability may already be largely reflected in the share price, while maintaining the current growth rate will become increasingly difficult as the business reaches its present scale. Investors must also assess the consequences of Jensen Huang's departure. His successor will be responsible for continuing the company's strategy and maintaining relationships with key customers, which have been one of the foundations of NVIDIA's success for years.
NVIDIA continues to benefit from enormous demand for AI infrastructure and possesses technological and financial advantages that competitors will find difficult to replicate quickly. However, the company faces a dual challenge: maintaining its competitive edge in an increasingly demanding environment and managing the leadership transition without disrupting its growth trajectory.
For investors, this means looking beyond the overall prospects of the artificial intelligence market and carefully assessing the company's valuation, which should reflect both its growth potential and its emerging sources of risk.
Even an exceptional company is not necessarily an attractive investment at every price.
 Source: XTB Research



US Open: Anthropic’s Record-Breaking IPO Restores Optimism on Wall Street


Palo Alto Earnings: Another Record Riding the Cybersecurity Crisis Wave

What's next for Take-Two Interactive's stock after the release of Grand Theft Auto VI❓


Economic Calendar: Trump-Xi Jinping-Putin summit ongoing, time for Walmart results (19.11.2026)
This content has been created by XTB S.A. This service is provided by XTB S.A., with its registered office in Warsaw, at Prosta 67, 00-838 Warsaw, Poland, entered in the register of entrepreneurs of the National Court Register (Krajowy Rejestr Sądowy) conducted by District Court for the Capital City of Warsaw, XII Commercial Division of the National Court Register under KRS number 0000217580, REGON number 015803782 and Tax Identification Number (NIP) 527-24-43-955, with the fully paid up share capital in the amount of PLN 5.869.181,75. XTB S.A. conducts brokerage activities on the basis of the license granted by Polish Securities and Exchange Commission on 8th November 2005 No. DDM-M-4021-57-1/2005 and is supervised by Polish Supervision Authority.