

- Democrats won both houses of Congress in the midterm elections, clearing political uncertainty and lifting major indices.
- The Dow Jones index gained 2.6% to top 53 150 pts, while the S&P 500 rose 1.6% to 7 730 pts.
- Investors rotated capital out of AI infrastructure and into healthcare and green energy sectors.
- Tesla and SpaceX shares dropped following political shifts and tighter regulatory fears.
- AMD quarterly revenue forecasts surpassed Intel for the first time in history.

- Democrats won both houses of Congress in the midterm elections, clearing political uncertainty and lifting major indices.
- The Dow Jones index gained 2.6% to top 53 150 pts, while the S&P 500 rose 1.6% to 7 730 pts.
- Investors rotated capital out of AI infrastructure and into healthcare and green energy sectors.
- Tesla and SpaceX shares dropped following political shifts and tighter regulatory fears.
- AMD quarterly revenue forecasts surpassed Intel for the first time in history.
- The midterm elections resulted in the Democratic Party taking control of both houses of Congress, which investors treated as a classic clearing event for political uncertainty.
- The Dow Jones Index gained about 2.6% after the open, breaching the 53,150 level, while the broader S&P 500 rose 1.6%, supported by a sharp rotation into healthcare and green energy.
- AI data center-related stocks and Elon Musk's companies (Tesla down nearly 3.9%, SpaceX down 6% in private trading) came under pressure following Gina Hinojosa's surprise victory in the Texas gubernatorial race.
- AI stocks may remain under pressure in the near term due to the risk of tighter regulation. On the other hand, the US will not want to fall behind in the technology race.
Wednesday's session on the New York floor began with a spectacular reversal and a decisive move into risk-on mode. Following an initial overnight slump in futures contracts of over 2%, dip buyers stepped into the market, interpreting full control of the legislature by Democrats as a signal ending weeks of election uncertainty. Donald Trump himself certainly helped by conceding the Democratic victory and signaling potential cooperation, which suggests a likely absence of government gridlock in the coming critical budget months.
We are witnessing a massive capital rotation: investors are moving away from overvalued AI infrastructure providers and reallocating funds into the defensive healthcare sector and green transition beneficiaries. Supporting sentiment is the ongoing earnings season, where 83% of S&P 500 companies have beaten profit expectations so far. Today's US macroeconomic data additions include the ADP report showing job growth of 67k vs. 90k previously and a trade deficit widening to -$107.9 billion.
Democratic Takeover of Congress and Tectonic Shifts in the Stock Market
The Democratic victory in the midterms means control over both chambers of Congress – the Senate and the House of Representatives. While President Donald Trump retains veto power over federal legislation, financial markets immediately began pricing in long-term regulatory shifts. However, the biggest shockwaves came from local elections, particularly the win by Democratic candidate Gina Hinojosa in the Texas gubernatorial race against incumbent Greg Abbott. It was a race described by Bank of America strategists as a "referendum between the cost of living and AI data centers." The governor-elect's pledge to immediately place a moratorium on new computing campus construction triggered a sell-off in data center infrastructure entities, hitting CoreWeave and Vertiv, among others.
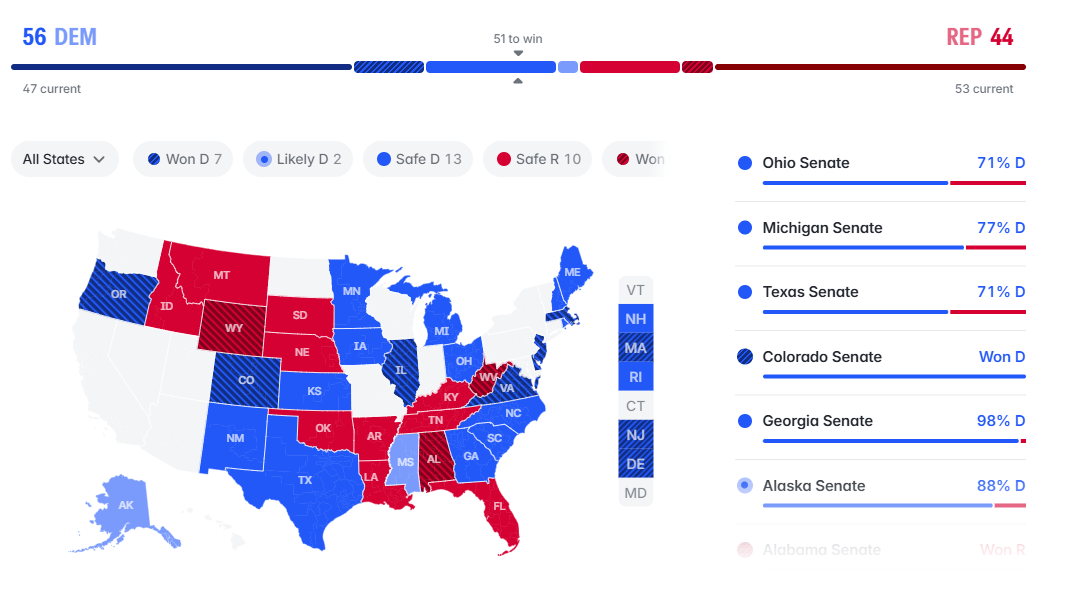 The Democratic win in the Senate makes policy implementation significantly harder for Trump. Such a decisive victory could also increase potential impeachment risks, which would require convincing only 10 Republican senators. Source: Polymarket
At the same time, clear reactions are visible across other asset classes: the dollar is losing value, Treasury yields are falling on fears of slower deregulation, and gold is gaining. Strong demand is seen in the pharmaceutical and insurance sectors, which expect expanded subsidies under healthcare programs and Medicaid, as well as renewable energy producers. Defense companies (including drops in Lockheed Martin and Northrop Grumman of over 2%) and banks are giving back part of their deregulation premium.
Major indices at the opening bell present as follows:
- US500: trading around 7,730 pts (+1.60%), the broader market is rapidly catching up, fueled by demand for defensive sectors and companies with strong balance sheets.
- US100: price near 28,960 pts (+1.8%), tech benchmark turns positive after defending key moving averages despite internal rotation out of the data center segment.
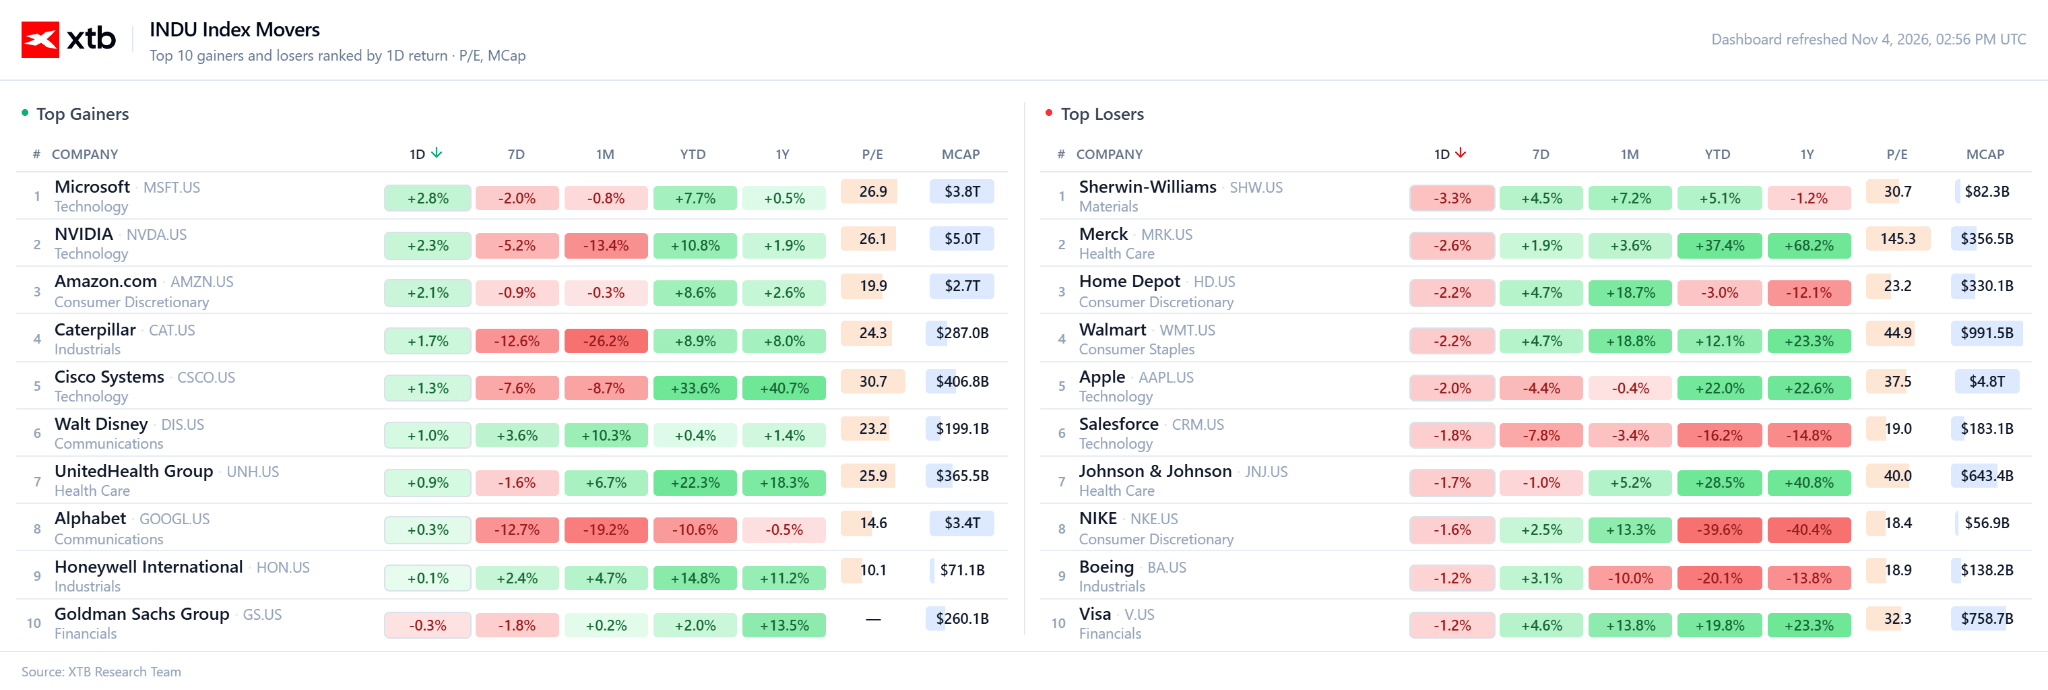
- US30: trading above 53,00 pts (+2.30%), the blue-chip index advances over 1,000 points, leading the wave of optimism driven by industrial and healthcare stocks.
- US2000: level around 2,859 pts (+1.3%), small-cap index rebounds strongly, unwinding recent discount stemming from legislative uncertainty.
S&P 500 Technical Analysis (US500)
The broad market staged a textbook bounce following a deep overnight sell-off, with S&P 500 futures currently hovering around 7,720 pts, up 1.60% on the day and 1.53% on a weekly basis. This movement was triggered by technical oversold conditions in the Nasdaq 100, which tested its 200-day moving average during overnight trading and neared oversold territory. The forward P/E ratio for tech stocks dropped near 19, a level unseen in a decade and significantly below the 10-year average of 23, triggering a dynamic influx of institutional capital.
On the US500 chart, the key task for bulls was to quickly reclaim the support zone in the 7,650–7,700 pts area. Currently, the 7,700 pts level has turned into local intraday support. The nearest major resistance lies at the psychological 7,800 pts barrier, a break above which opens the door to test previous bull market highs. However, ahead of this test, breaking the downward trendline along with the 25 and 50 SMAs will be crucial.
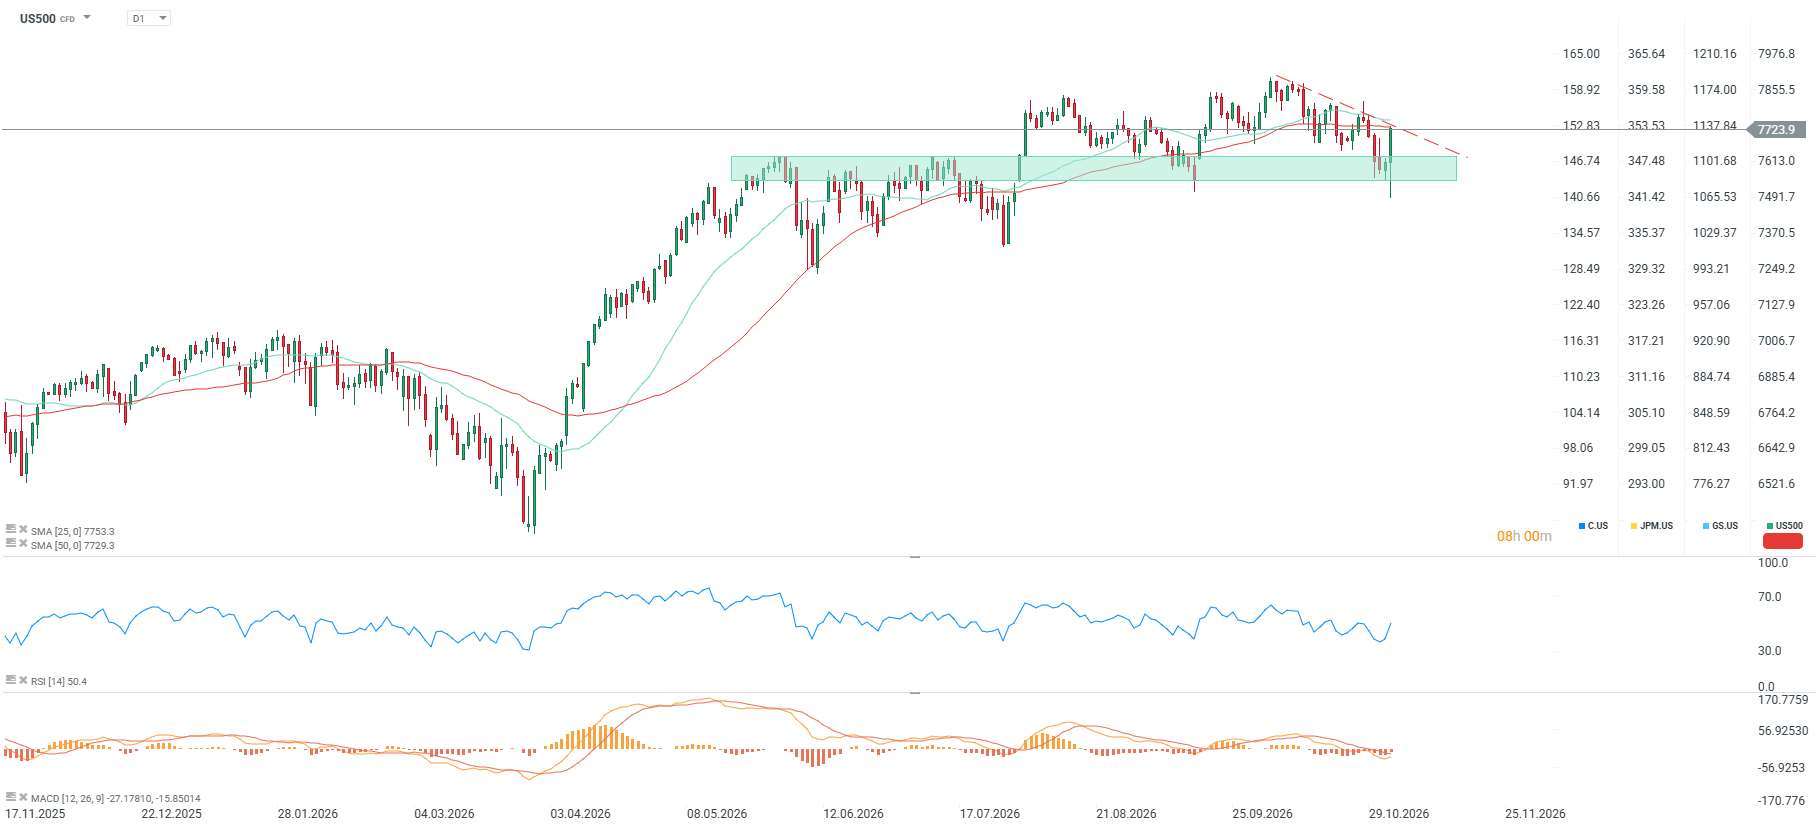
- Bullish Scenario (Continuation): Holding above the 7,700 pts zone and a stable breakout above 7,800 pts will confirm entry into traditionally strong post-election appreciation in November and December, driven by short covering.
- Bearish Scenario (Invalidation): A fall back below 7,650 pts will neutralize buying momentum and push the index toward 7,550 pts, confirming Bank of America analysts' concerns over potential downward corporate earnings revisions under the threat of tax hikes.
Key Corporate News
- Elon Musk's assets under heavy political pressure: Tesla (TSLA.US) falls 3.88%, while privately traded SpaceX slides over 6%. Investors fear that the Democratic Congress takeover will hurt the business standing of the key Republican donor and lead to tighter scrutiny over the billionaire's federal contracts.
- Slump in data center back-end providers: CoreWeave (CRWV.US) drops 6.50% (Deutsche Bank cut its price target from $150 to $125), and Vertiv Holdings (VRT.US) slides 6.60%. The sell-off is driven by Gina Hinojosa's election as Texas governor and her promised moratorium on new computing campuses, putting the pace of AI infrastructure expansion in the state into question.
- HCA Healthcare (HCA.US) gains 5.90% (peaking at 6.5%), leading the healthcare sector upward on expectations of expanded federal health subsidies following the Democratic win.
- Advanced Micro Devices (AMD.US) climbs 4.79%. Investors rewarded an upgraded sales forecast for data center processors (revenue in this segment nearly doubled YoY), offsetting Bank of America's price target trim from $720 to $650.
- Amazon (AMZN.US) advances 7.33%, ranking among top mega-cap tech gainers following strong capital inflows into cloud platforms and e-commerce after recent weeks of selling.
- Apple (AAPL.US) rises 5.64%, effectively shrugging off a downgrade by DZ Bank analysts to "Sell" (with a target price of $300), supported by the broader mega-cap rally.
- Datadog (DDOG.US) plunges 12.08%. Despite beating expectations and raising full-year adjusted EPS guidance, the cloud monitoring software provider's modest revision pace proved insufficient for demanding SaaS valuations.
- Block (XYZ.US) jumps 10.50% following solid Q3 results that topped earnings and revenue consensus, alongside optimistic operational guidance and settlement terms disclosure with the DOJ.
- Arista Networks (ANET.US) rises 7.10% after issuing a Q4 revenue forecast well above Wall Street estimates, confirming sustained demand for advanced networking hardware.
- Amdocs (DOX.US) plummets 38.00% following a drastic cut to its Q1 financial outlook, a direct result of an escalating commercial dispute with T-Mobile.
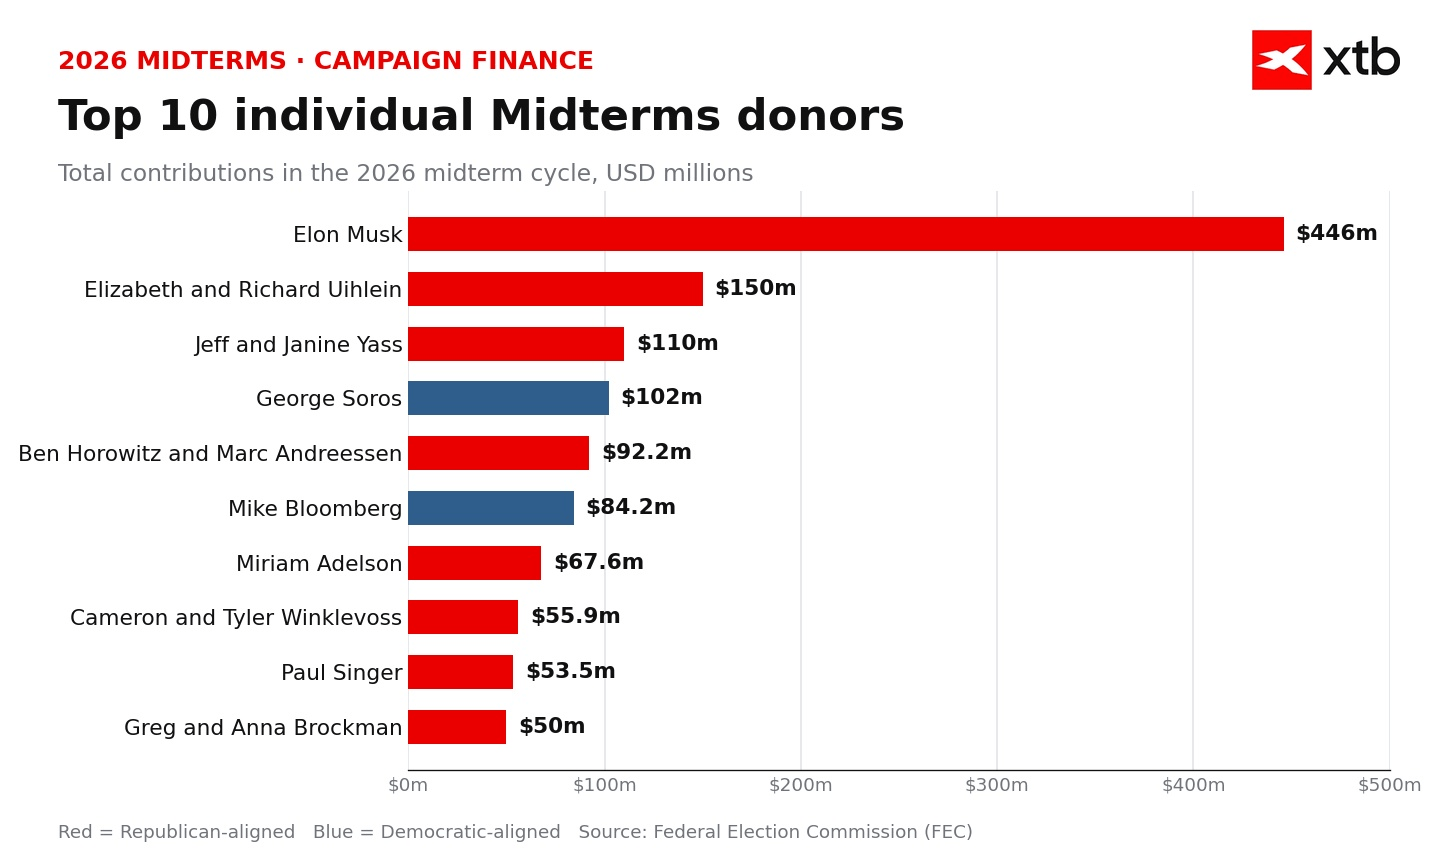 Elon Musk was the largest individual donor in the election campaign. This means he strongly preferred that Democrats did not take power. Source: XTB
Retail Investor Buzz
- Historic Dethroning of Intel: On r/stocks and r/stockstobuytoday forums, the hottest topic is that AMD's quarterly revenue forecast surpassed Intel's for the first time in history, celebrated by retail traders as the definitive end of the Santa Clara giant's long-standing dominance.
- Euphoria After Wall Street Futures Surge: The r/wallstreetbets community was flooded with screenshots of massive gains on S&P 500 (SPY) options, with retail post-election bounce bets yielding tens of thousands in profit and triggering forced short covering.
- Skepticism Over Goldman Sachs Post-Election Portfolio: Retail threads are heavily analyzing a viral 9-trade basket prepared by Goldman Sachs in the event of a Democratic win; skepticism prevails against blindly copying institutional moves, especially given high volatility in defense stocks.
- Uncertainty Surrounding AI Infrastructure: Retail investors face growing uncertainty over technical patterns in AI stocks (with emerging "death cross" warnings), while reports of a Texas data center moratorium clash with optimism around SpaceX's deal with Qualcomm for satellite connectivity.
Calendar
- November 19, 2026: Nvidia Q3 earnings release – a key inflection point for the global AI trade.



BREAKING: Democrats take both chambers of Congress🗽


Daily Summary: Chips lift Wall Street on Election Day, oil drops amid progress in negotiations (03.11.2026)

US Open: Lower oil prices boost indices, markets await Midterms results (03.11.2026)

Chart of the Day: Brent crude falls despite Trump's words about no desire to negotiate
This content has been created by XTB S.A. This service is provided by XTB S.A., with its registered office in Warsaw, at Prosta 67, 00-838 Warsaw, Poland, entered in the register of entrepreneurs of the National Court Register (Krajowy Rejestr Sądowy) conducted by District Court for the Capital City of Warsaw, XII Commercial Division of the National Court Register under KRS number 0000217580, REGON number 015803782 and Tax Identification Number (NIP) 527-24-43-955, with the fully paid up share capital in the amount of PLN 5.869.181,75. XTB S.A. conducts brokerage activities on the basis of the license granted by Polish Securities and Exchange Commission on 8th November 2005 No. DDM-M-4021-57-1/2005 and is supervised by Polish Supervision Authority.