


Wall Street opens the week with further declines in the technology sector. Nasdaq 100 futures are down about 1.2%, S&P 500 futures are down about 0.4%, and the Dow Jones is close to flat. The S&P 500 is on track for a third consecutive losing session. The gap between the indices shows this is not a selloff across the whole market. Investors are reducing exposure to AI and semiconductor stocks.
The biggest shadow hangs over Nvidia. The company has just had its worst week since April 2025, and tomorrow after the close it reports results for the third quarter of its fiscal year. It will be the first report since Jensen Huang stepped down as CEO and left the board (November 12), amid an investigation by the board of directors. CFO Colette Kress is leading the company on an interim basis. The market will not focus only on revenue (guidance is about $108 billion). It will also look at the new leadership, the strategy, and the impact of export restrictions on the most advanced chips going to China. There are also questions about whether the restrictions were circumvented in sales to Chinese companies. The market is also following reports of a possible return of Huang, which the Financial Times has covered among others. His allies reportedly set up a “war room,” and two major investors (Altimeter and Atreides) urged the board to consider all options. This adds uncertainty right before the report. A moment after the US market opened, Donald Trump said that Huang did not endanger US national security. The president has publicly defended the former CEO from the start. Nvidia’s board has also said it has no reason to believe that national security or company secrets were compromised. Such words may weaken the regulatory-risk angle and fuel speculation about Huang’s return, although the FBI investigation into the matter is still ongoing.
The second key event is Anthropic’s debut on the Nasdaq (ticker ANT). The IPO is due to be priced on Wednesday, and trading starts on Thursday. The range is $70-78 per share, which implies a valuation of up to about $1.4 trillion on a fully diluted basis. Interest is high, as orders have exceeded the offering about sixfold. With Nvidia weakened, the debut matters more. Dan Ives of Yorkville Ives sees it as a “big near-term win” for the whole sector that could restore confidence in the AI growth thesis. The market will also ask about the profitability of the business model, because this will be a test of the industry’s maturity.
Thursday will also bring the first meeting of Trump, Xi and Putin, in Shenzhen. The agenda is meant to include nuclear non-proliferation, the war in the Middle East, and trade. The US side does not expect an agreement, but the market will be alert to any signals on tariffs and chip export controls. In the background there is pressure in the debt market: the 10-year yield remains above 5%, and the market is pricing in a 25 bp rate hike in December. Today at 18:00 (Warsaw time), Fed Chair Kevin Warsh will speak. His address concerns the impact of AI on the economy and productivity, so no guidance on rates should be expected. Weakness is also visible in cryptocurrencies, as Bitcoin extends its decline and falls below $65,000.
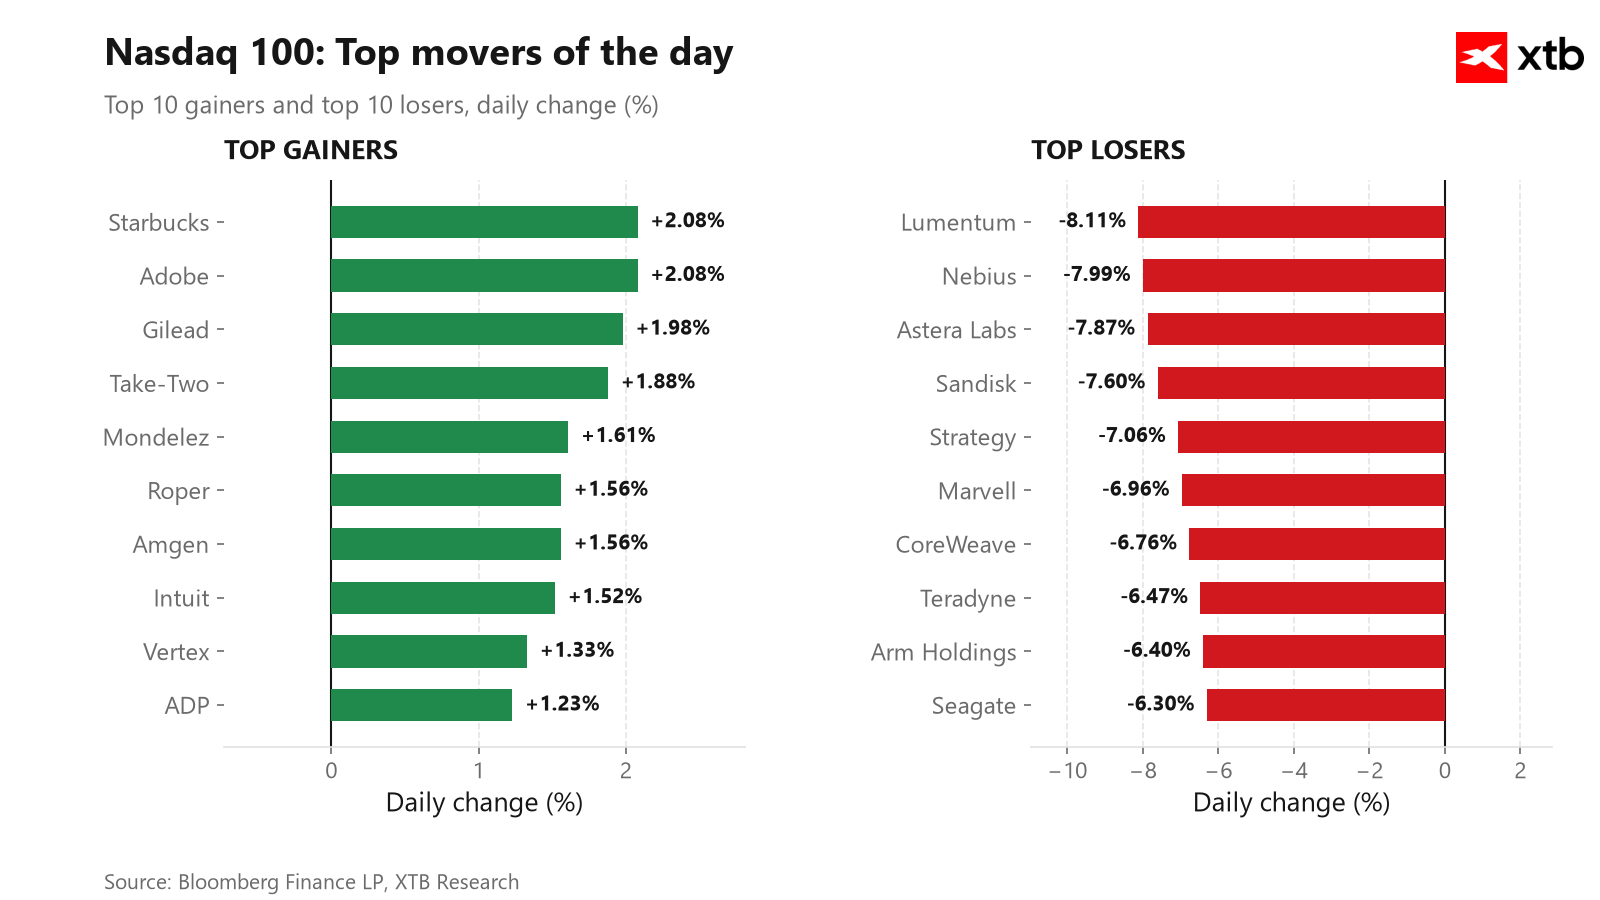
Chart 1 shows the biggest moves among companies in the Nasdaq index.
Company news
- Nvidia (NVDA.US): The shares are falling ahead of tomorrow’s report. Investors are focused on the uncertainty around the leadership and the effect of export restrictions on sales to China. Nvidia is the weakest of the Magnificent Seven, and the pressure is spreading to the whole sector. Broadcom (AVGO.US) and Intel (INTC.US) are also falling. (down about 2%)
- Nebius (NBIS.US): The company delivered strong third-quarter results (revenue of about $981 million, up about 571% y/y and above consensus), but the market focused on the weaker outlook. (down about 6%)
- Summit Therapeutics (SMMT.US): The US regulator rejected the lung cancer treatment the company is developing with Akeso. This hits the key product on which the valuation was based. (down about 12%)
- Aramark (ARMK.US): Fourth-quarter results disappointed, as adjusted earnings per share and revenue were below expectations. The 2027 guidance was also slightly weaker than consensus. (down about 4%)
- Blackstone Digital Infrastructure Trust (BXDC.US): The trust signed an agreement to buy a 75% stake in two data-center joint ventures with Amazon Web Services. The deal is worth about $5 billion. (up about 4%)
- Centene (CNC.US): Managed-care insurers are gaining after a CMS decision allowing states to delay Medicaid work requirements by six months. This reduces the risk of a drop in the number of insured people. (up about 3%)
- Take-Two Interactive (TTWO.US): Jefferies points to strong pre-orders ahead of Thursday’s launch of Grand Theft Auto VI. (up about 2%)
Technical analysis of US100 (D1)
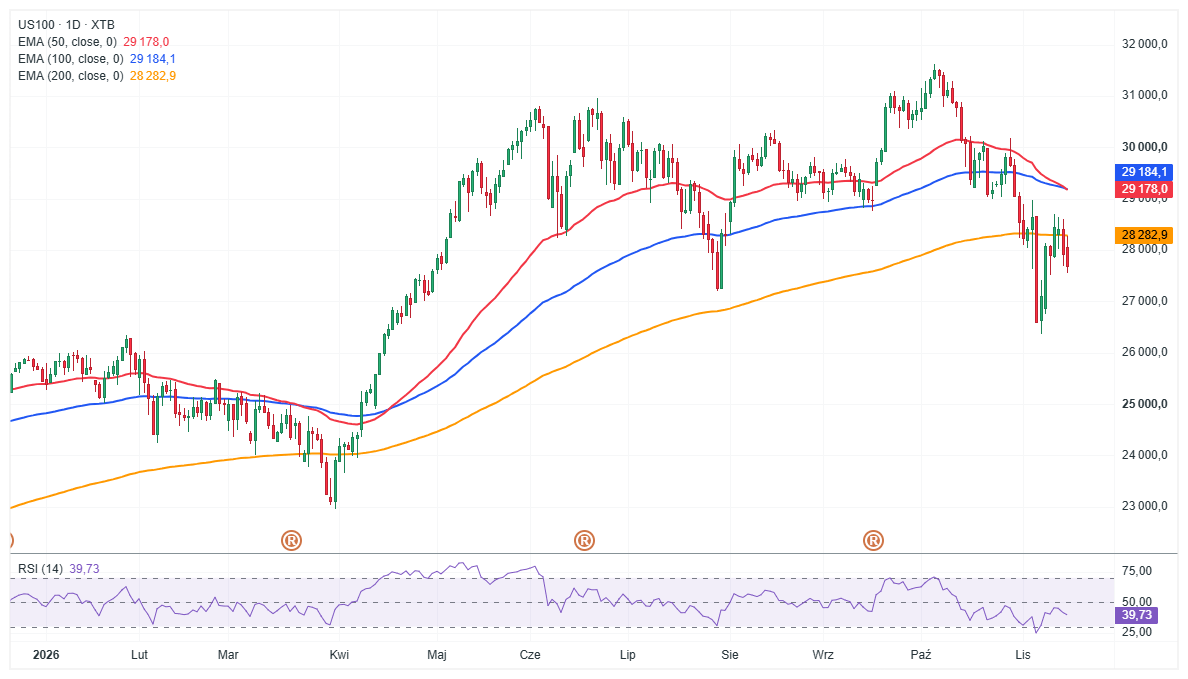
After bouncing from the November lows around 26,400 points, US100 has come under selling pressure again. The price is still below the 200 EMA (about 28,300 points), and the recent attempt to reclaim it ended in rejection. The 50 EMA has fallen below the 100 EMA around 29,200 points, which worsens the medium-term picture. The RSI around 40 points stays below the neutral level, so sellers have the upper hand. Unless buyers defend the 27,500-point zone, the risk of a retest of the recent lows is rising. A return above the 200 EMA would be the first sign of improvement. Source: xStation5
Calendar for the rest of the session
- 18:00 - Speech by Kevin Warsh (Fed) on the impact of AI on the economy



Daily Summary: PPI Inflation slows down, but EURUSD approaches 1.10



Three Markets to Watch Next Week (13.11.2026)

Morning Wrap: Nvidia sell-off weighs on indices - how many more Huang's affairs must the market price-in? (12.11.2026)


📊Daily Summary: Tech sector drives Wall Street rebound, DAX leads in Europe
This content has been created by XTB S.A. This service is provided by XTB S.A., with its registered office in Warsaw, at Prosta 67, 00-838 Warsaw, Poland, entered in the register of entrepreneurs of the National Court Register (Krajowy Rejestr Sądowy) conducted by District Court for the Capital City of Warsaw, XII Commercial Division of the National Court Register under KRS number 0000217580, REGON number 015803782 and Tax Identification Number (NIP) 527-24-43-955, with the fully paid up share capital in the amount of PLN 5.869.181,75. XTB S.A. conducts brokerage activities on the basis of the license granted by Polish Securities and Exchange Commission on 8th November 2005 No. DDM-M-4021-57-1/2005 and is supervised by Polish Supervision Authority.