


Following Wednesday’s strong session, driven by the Democrats’ victory in the congressional elections, caution is returning to Wall Street. Yesterday’s optimism is giving way to efforts to assess how the new balance of power in Washington could affect economic policy and individual market sectors. The Nasdaq is down nearly 2%, the S&P 500 is losing around 0.8%, while the Dow Jones is the only major index holding in positive territory, gaining more than 0.2%.
Democrats have secured control of both chambers of Congress, limiting the Trump administration’s ability to push forward its political agenda. However, this does not automatically mean a radical shift in economic policy. The President retains veto power, while disagreements between the White House and Congress could make it harder to pass new legislation. Investors will now focus on which campaign promises translate into concrete policy measures and which remain part of the political debate.
The technology sector faces the greatest uncertainty. The Democrats’ victory has once again raised concerns about potentially tighter oversight of AI and data center expansion. The risks are not limited to regulation itself, but also include local opposition to new infrastructure investments. Potential delays in data center construction could weigh on chipmakers, hardware suppliers and energy companies involved in supporting the sector.
However, this does not mean that all major technology companies will face the same degree of pressure. Slower infrastructure expansion could pose a challenge for semiconductor manufacturers and data center operators, while the impact on major cloud service providers may be more complex. Thursday’s trading highlights this divergence: weakness is concentrated primarily in chipmakers and AI infrastructure stocks, while some of the largest technology companies are still posting gains.
Following yesterday’s rally, Wall Street is shifting its focus from the election results themselves to their potential consequences. The market now faces two years in which relations between the administration and Congress could play a significant role in shaping regulation, public spending and policy towards major technology companies. For now, the Dow Jones remains relatively resilient, while the S&P 500 and Nasdaq are feeling the impact of changing sentiment towards AI-related stocks. Yesterday’s optimism has therefore failed to translate into a sustained rally across the broader market.
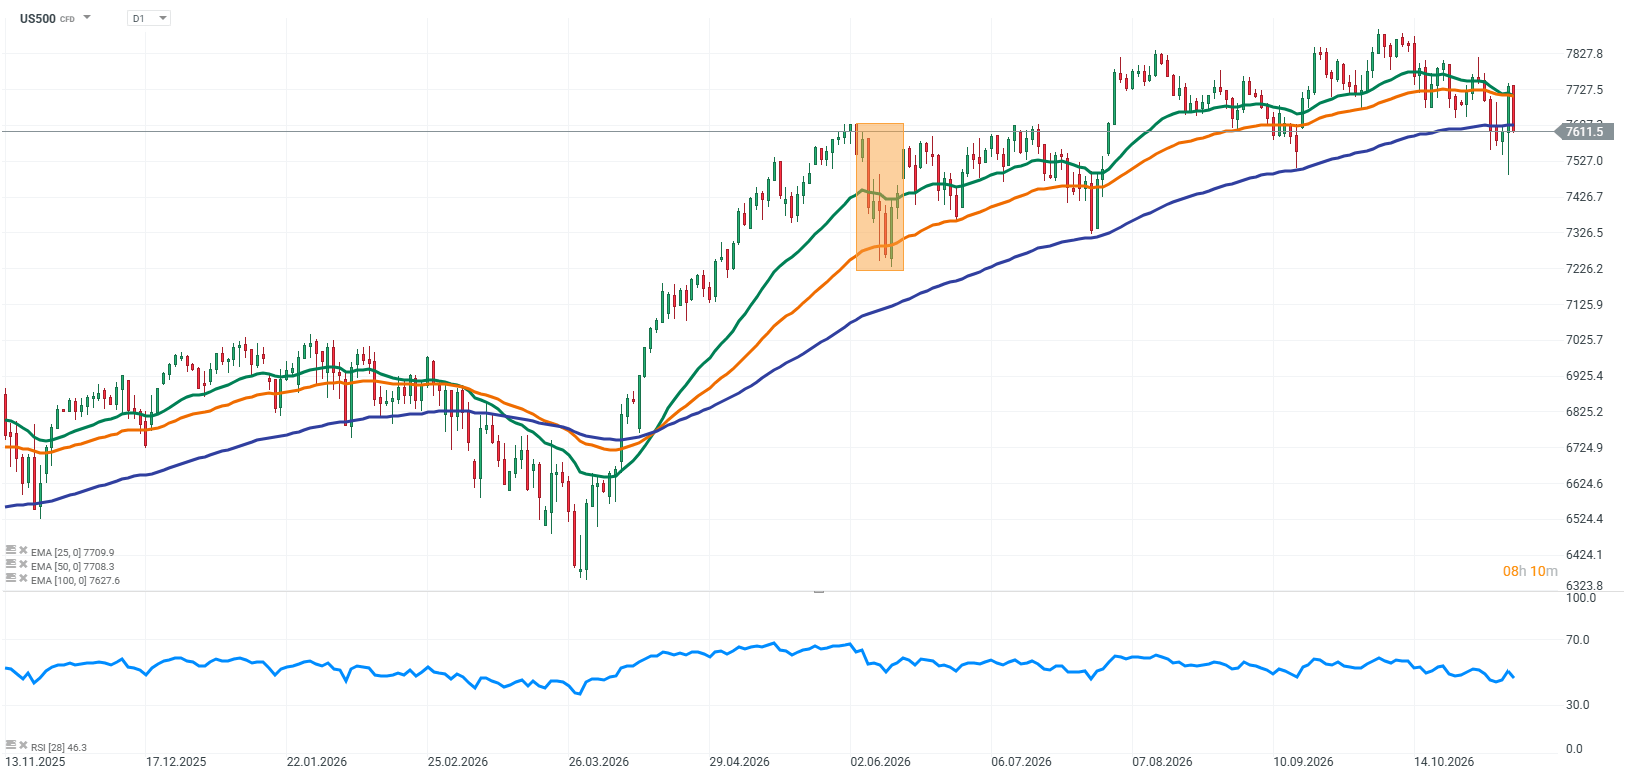
S&P 500 futures (US500) are falling sharply in Thursday’s trading, giving back some of the gains made during Wednesday’s post-election rally on Wall Street. Technology stocks are facing the strongest pressure as investors grow increasingly concerned that the Democrats’ victory could lead to measures restricting or temporarily blocking the construction of new data centers.*
Source: XTB Research
Corporate News
Micron (MU.US) is currently down around 7% during Thursday’s Wall Street session, extending its losses following Wednesday’s sell-off. The memory chipmaker is facing significant selling pressure as investors worry that the Democrats’ political victory could lead to restrictions and slower data center construction, potentially weakening future demand for memory chips.
SpaceX (SPCX.US) is facing local opposition to its planned massive AI data center project in Arizona. Residents are primarily concerned about high water consumption, energy demand and the potential environmental impact. The project could require as much as 6 GW of power, while protests and permitting challenges could delay its development.
Microsoft (MSFT.US) has reportedly decided against a multibillion-dollar expansion of its planned partnership with UK-based Nscale involving a data center in Texas. The decision means Microsoft will not exercise an option to increase its reserved computing capacity, although the existing agreement remains unchanged. This is another indication that even the largest technology players are becoming more selective about AI infrastructure spending and are assessing future demand more carefully.
Qualcomm (QCOM.US) came under pressure following the release of its fourth-quarter fiscal results and mixed guidance for the coming period. Revenue from smartphone chips weakened significantly, reflecting challenging conditions in the mobile device market, although the automotive segment recorded strong growth. Investors are assessing whether expansion into new business areas, including AI-related solutions, can offset weakness in the company’s traditional business.


BOE review

Qualcomm Earnings: Smartphone Setback


Market Wrap: European Gas Rebounds as Rheinmetall Plunges
BREAKING: BoE raises interest rates by 25pbs to 4%⏰
This content has been created by XTB S.A. This service is provided by XTB S.A., with its registered office in Warsaw, at Prosta 67, 00-838 Warsaw, Poland, entered in the register of entrepreneurs of the National Court Register (Krajowy Rejestr Sądowy) conducted by District Court for the Capital City of Warsaw, XII Commercial Division of the National Court Register under KRS number 0000217580, REGON number 015803782 and Tax Identification Number (NIP) 527-24-43-955, with the fully paid up share capital in the amount of PLN 5.869.181,75. XTB S.A. conducts brokerage activities on the basis of the license granted by Polish Securities and Exchange Commission on 8th November 2005 No. DDM-M-4021-57-1/2005 and is supervised by Polish Supervision Authority.