

- Nvidia raises the bar once again and impresses with forecasts, but morning enthusiasm quickly faded, and the company's valuation is experiencing a slight cooling.
- Major New York indices remain under clear supply pressure, with a particular focus on traditional industrial companies.
- A bright spot of the session remains Take-Two Interactive, soaring thanks to enthusiastic reviews of the upcoming release of "Grand Theft Auto VI".
- Today at 20:00 FOMC minutes will be released from the meeting held at the end of October

- Nvidia raises the bar once again and impresses with forecasts, but morning enthusiasm quickly faded, and the company's valuation is experiencing a slight cooling.
- Major New York indices remain under clear supply pressure, with a particular focus on traditional industrial companies.
- A bright spot of the session remains Take-Two Interactive, soaring thanks to enthusiastic reviews of the upcoming release of "Grand Theft Auto VI".
- Today at 20:00 FOMC minutes will be released from the meeting held at the end of October
Wednesday's start to the US market session brought a classic collision of market optimism with harsh macroeconomic reality. Although the release of Nvidia's results was supposed to be a major celebration and an impulse for another wave of growth in the artificial intelligence sector, initial gains in futures evaporated into thin air shortly after the opening bell. Today's sentiment is dominated by caution and flight from risk, with investors anxiously watching rising Treasury yields and anticipating a hawkish tone in the evening FOMC "minutes". Capital is flowing heavily into defensive sectors, while market participants listen closely to scheduled speeches from Federal Reserve officials and analyze recent comments (an extremely hawkish Waller suggesting a 50 basis point hike). Adding fuel to the fire are mixed signals from the retail sector, reminding markets of consumer vulnerabilities.
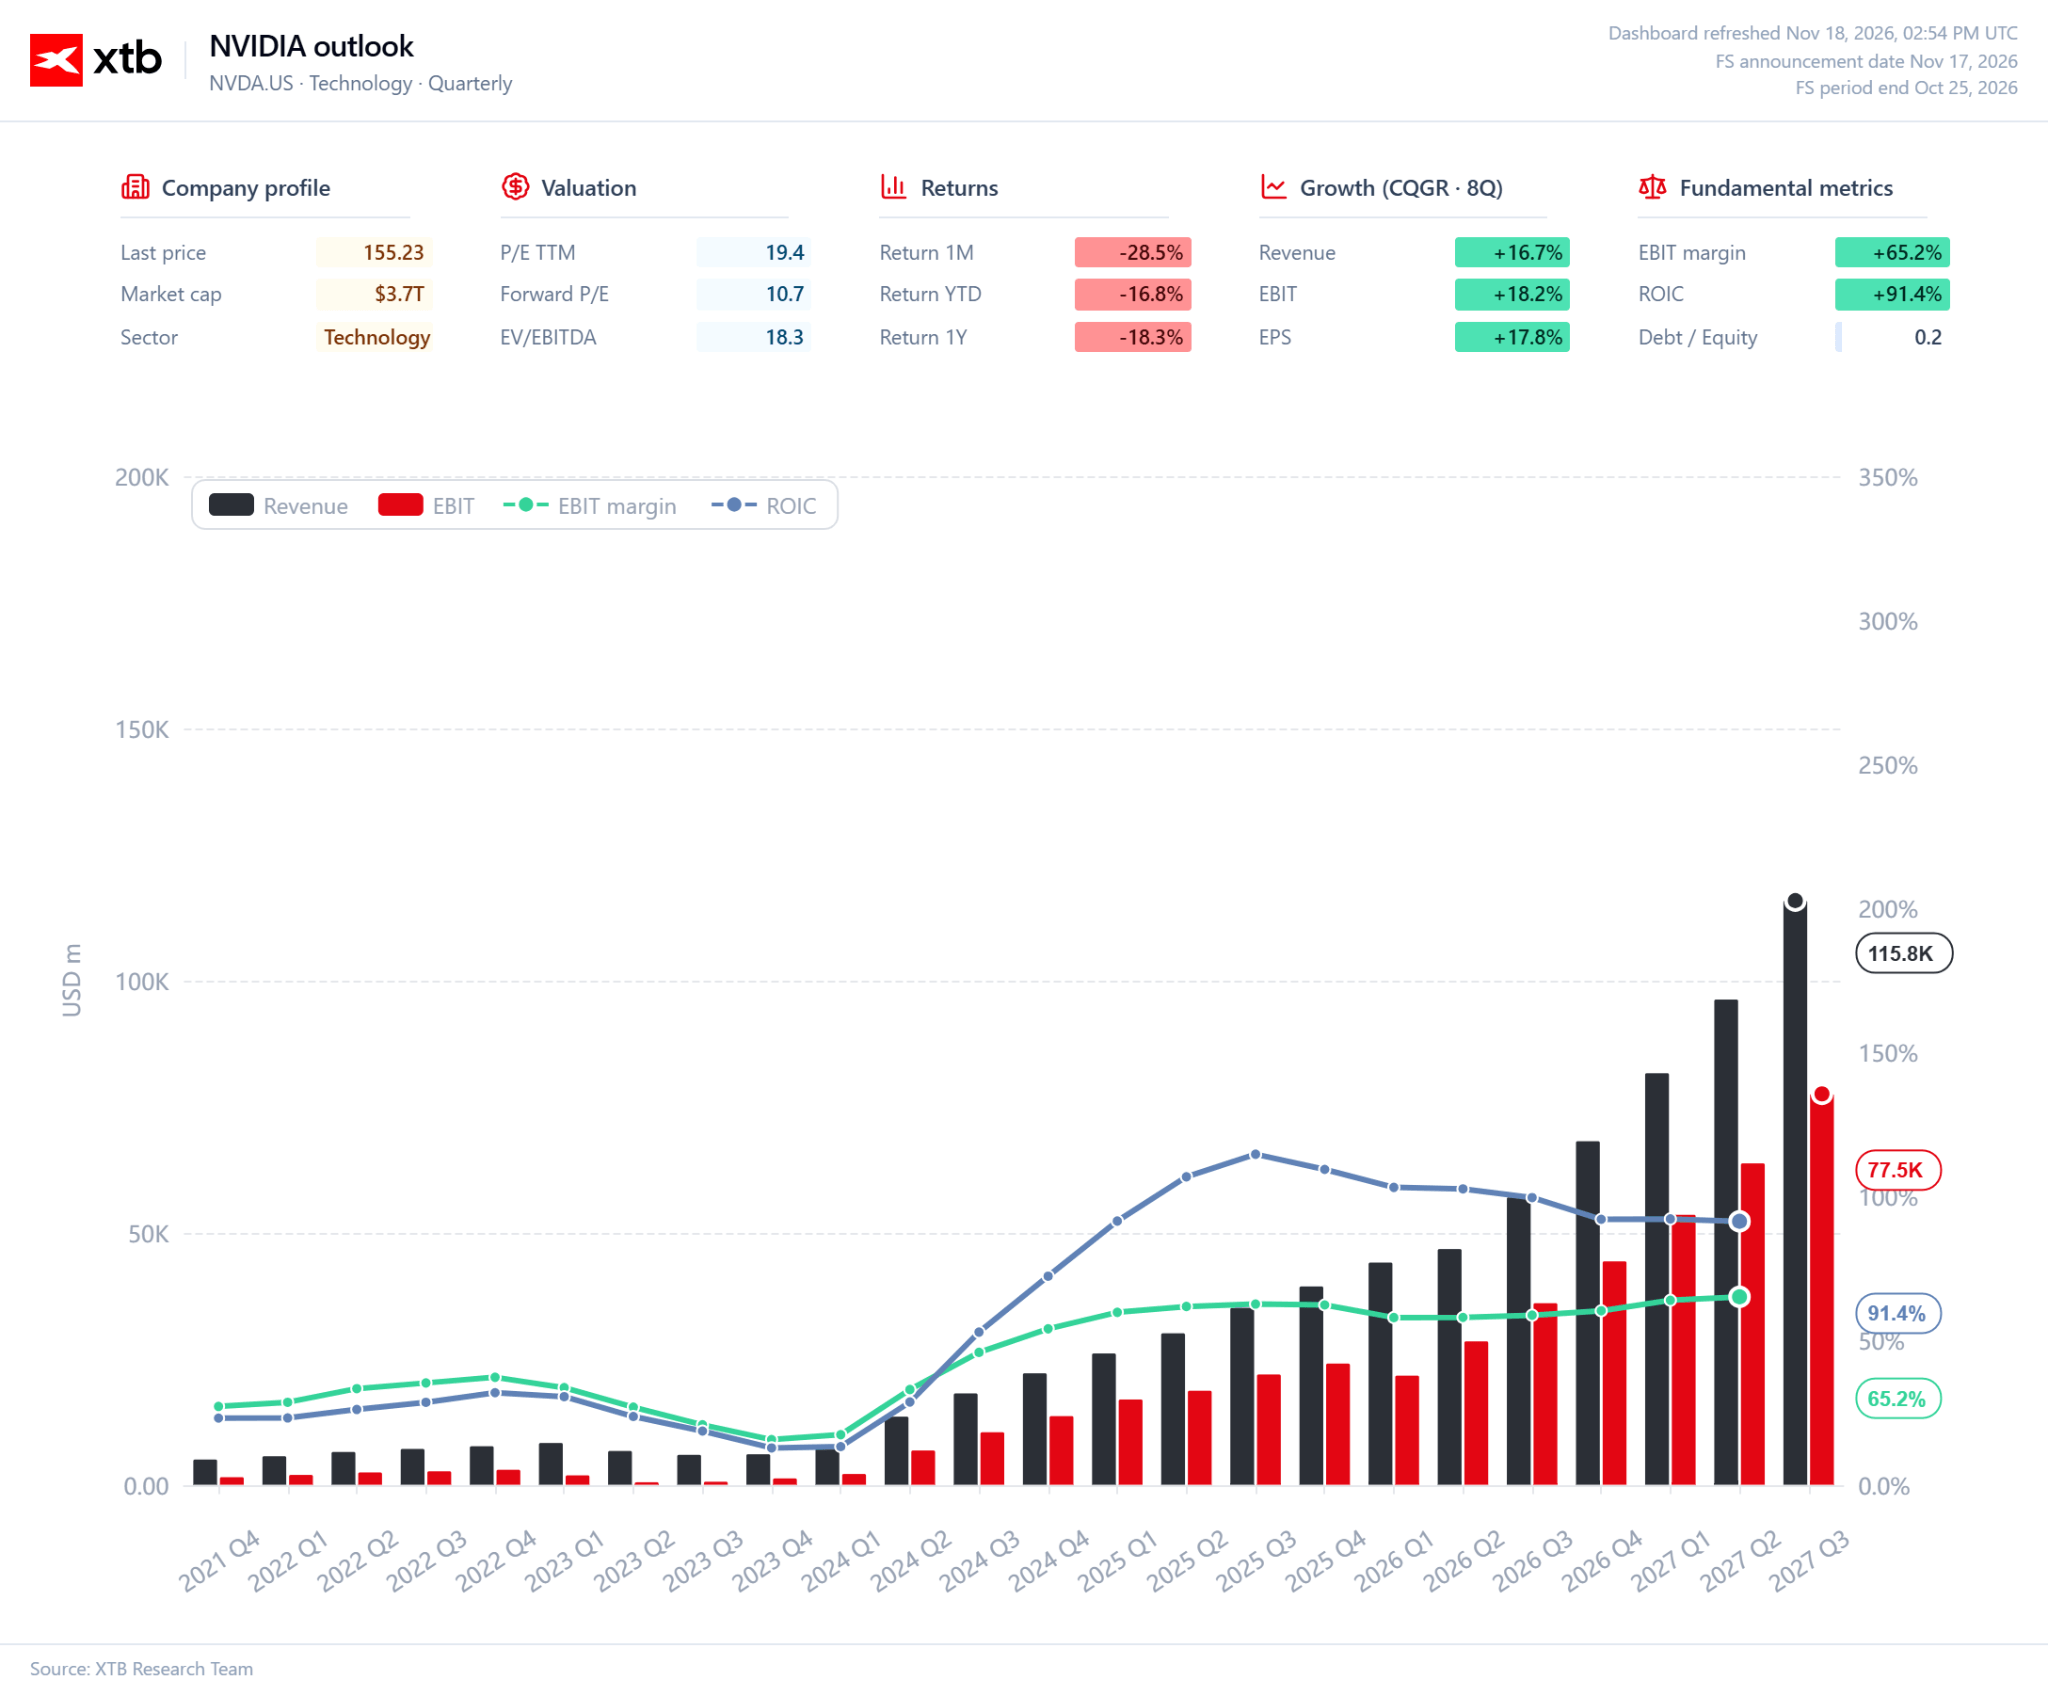 Behind us are "astronomical" Nvidia results, which were unable to improve market sentiment. Source: XTB
Collision of AI narrative with a hawkish Fed
Wall Street has reached a point where even excellent tech fundamentals are no longer enough to pull the market higher when support from the central bank is missing. The fact that global microchip trade has surpassed oil and gas turnover in value vividly illustrates where the heart of the economy beats today. Yet the prospect of a tougher monetary stance from the Fed raises anxiety, and the market is with increasing confidence pricing in a continuation of hawkish policy in upcoming meetings.
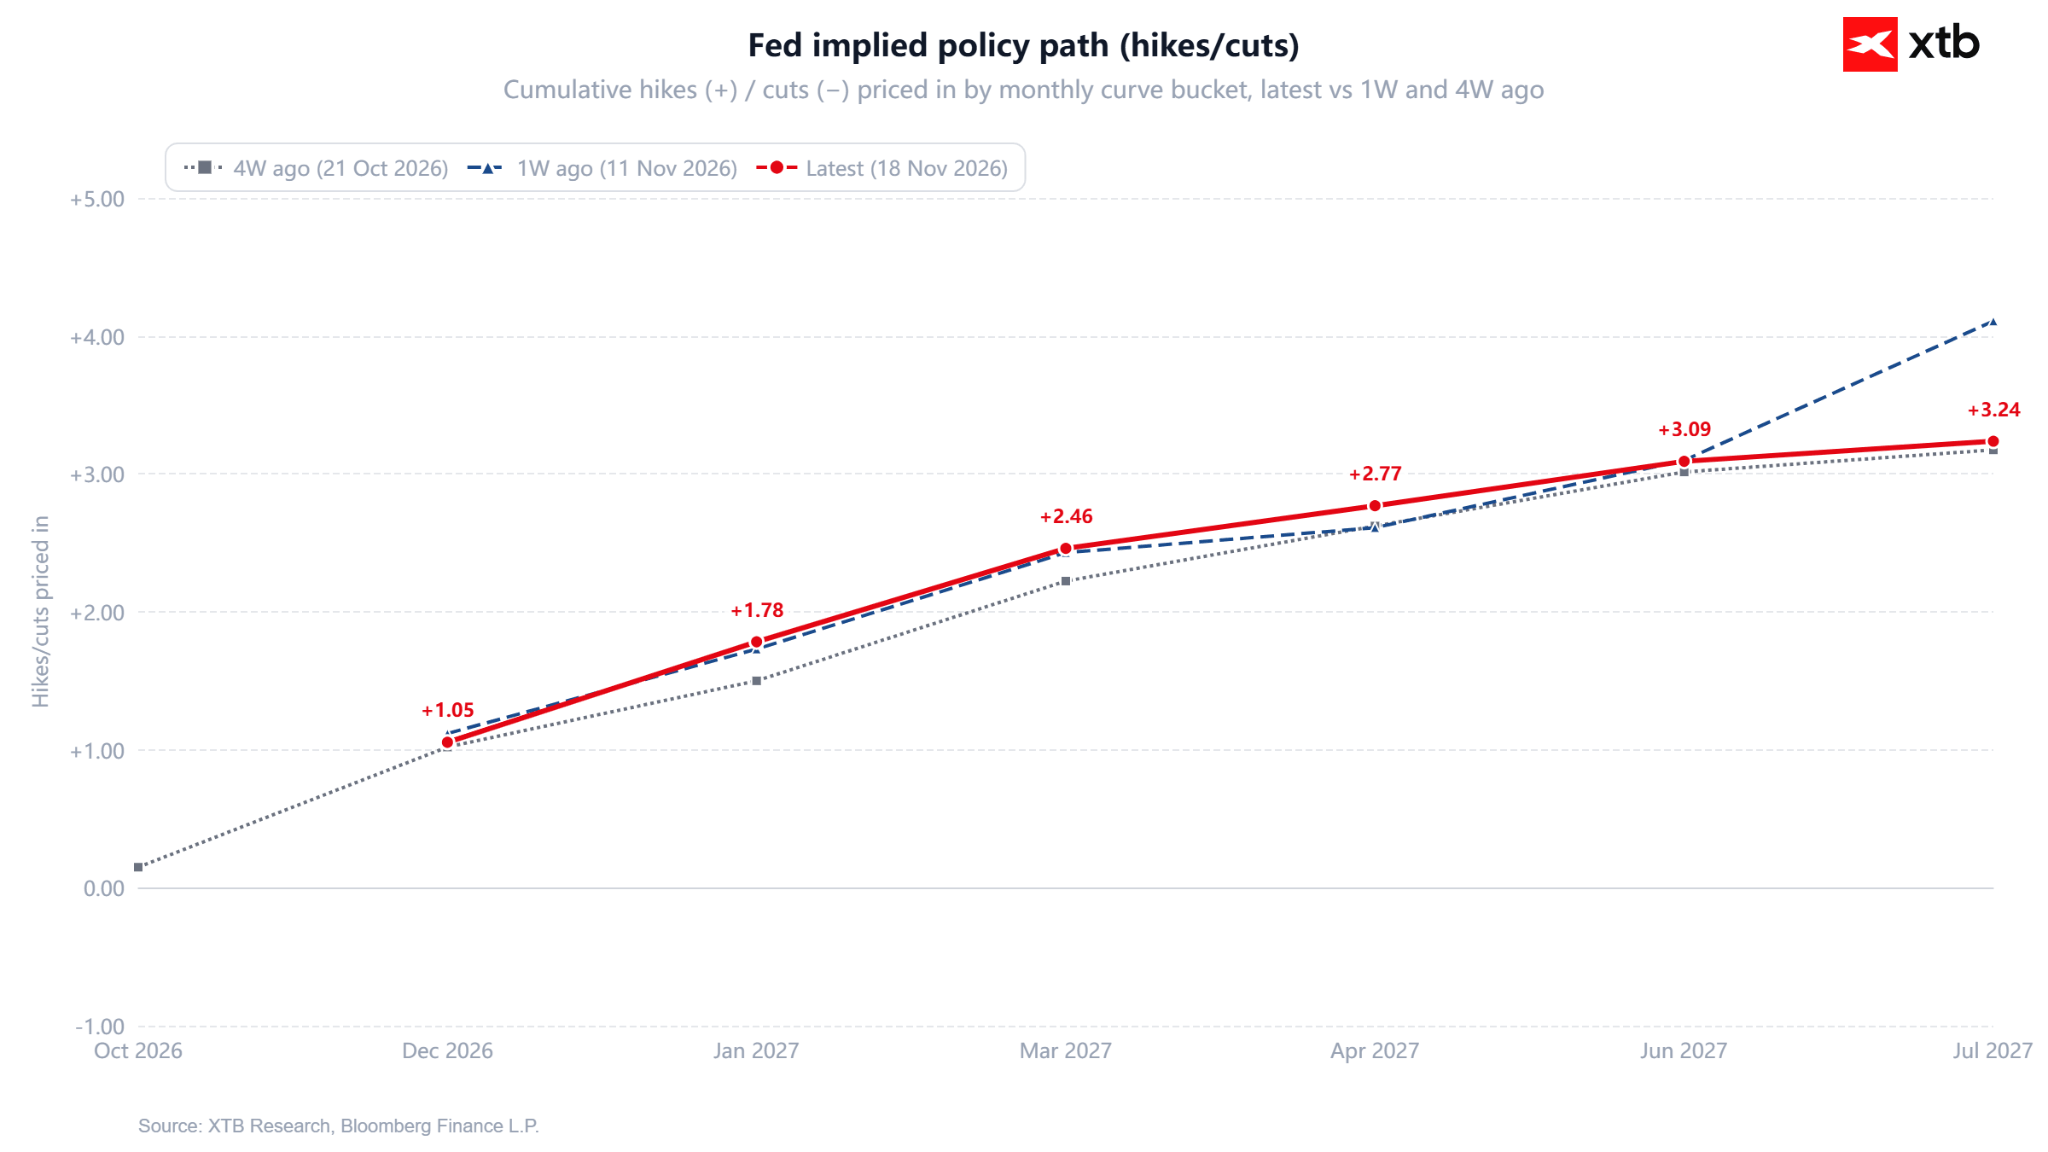
Rising yields on US debt are effectively dampening investor enthusiasm and sapping momentum from highly valued growth companies. Interestingly, long-term bonds have stopped acting as a safe haven during moments of market turbulence, reversing long-established relationships with the VIX index.
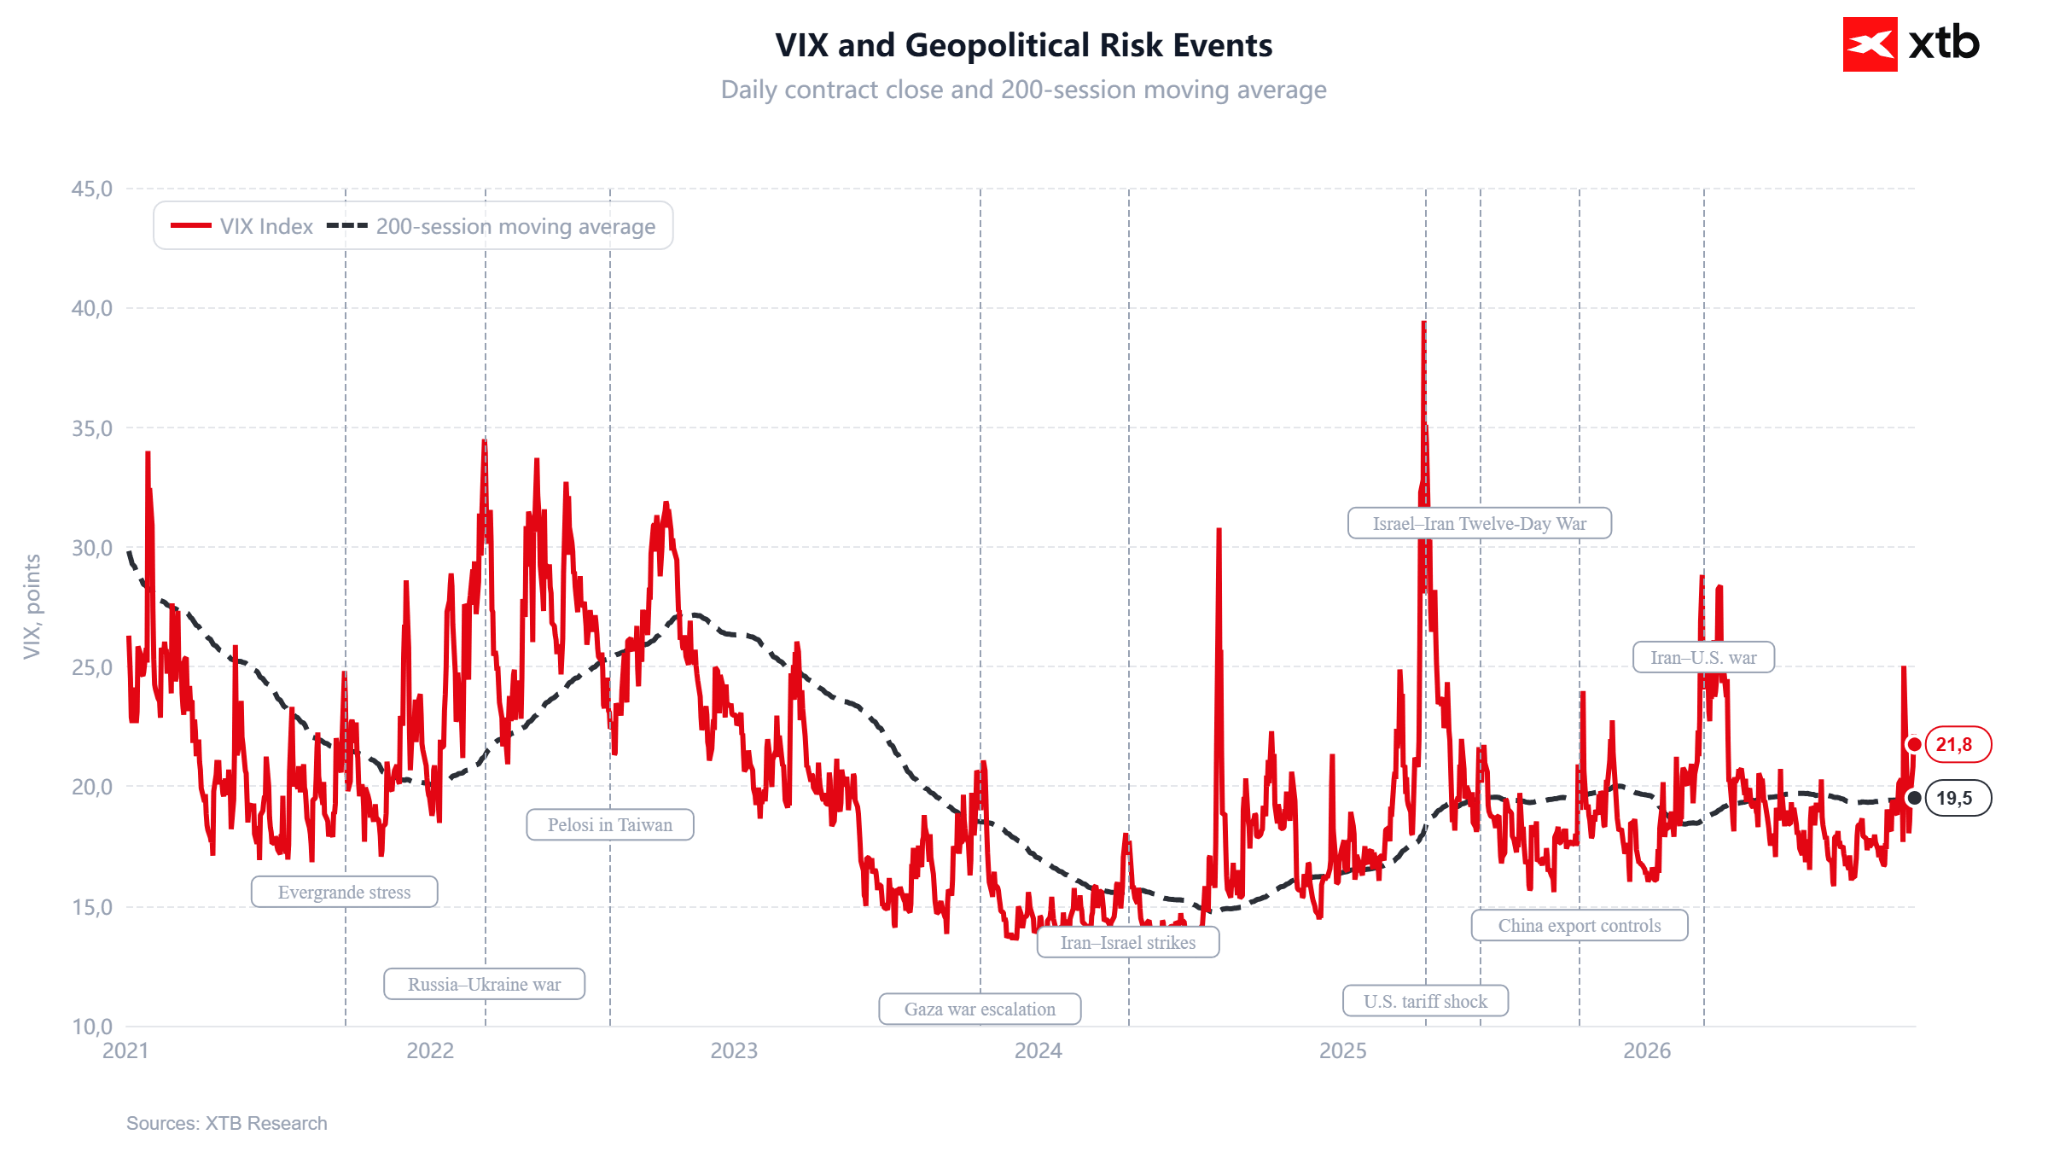
Commodity and currency markets are also living in the shadow of geopolitical tensions in the Middle East. In this environment, the evening FOMC meeting protocol will be a major test for markets—it will reveal the extent to which committee members fear that multi-billion dollar investments in AI infrastructure could sustain inflationary pressures and make it harder to bring inflation down to target. Expectations regarding the Fed policy path currently indicate priced-in cumulative rate hikes/cuts of +1.05 in December 2026 and +1.78 in January 2027, with a further increase to +3.24 in July 2027.
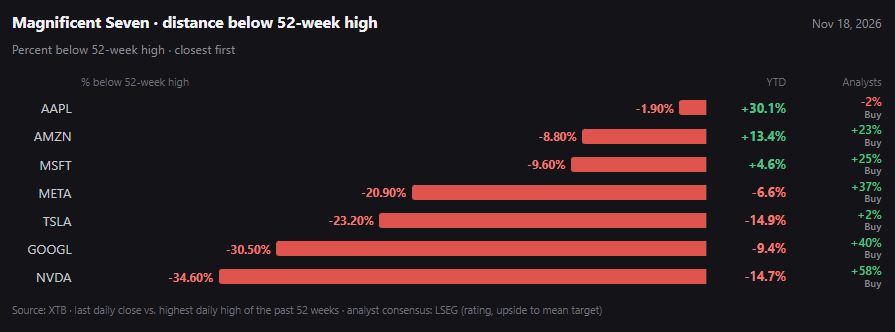 The old Mag7 is performing rather poorly. Only 3 out of 7 companies are in the green this year, and each is also far from historical highs. Apple is doing best, but analysts currently see no upside potential. Source: XTB, LSEG
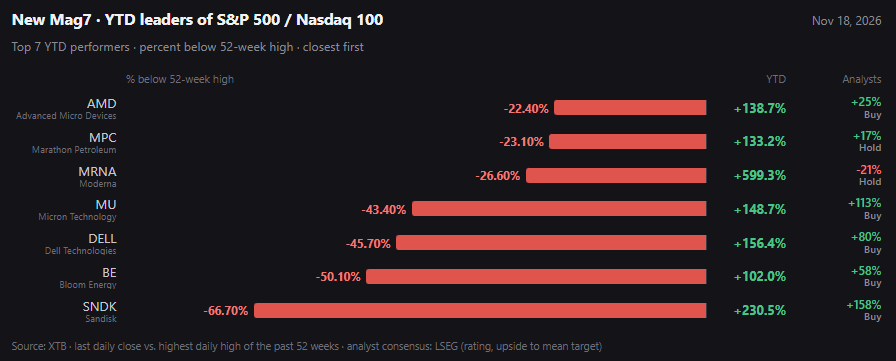 The "New Mag7" has also seen huge drops from peaks, but year-to-date returns are phenomenal, and targets for most companies remain distant. Source: XTB, LSEG
Technical Analysis of US500
From a technical perspective, the US500 index has entered a necessary breather phase after reaching earlier peaks. After nervous initial minutes, demand is trying to build solid ground underfoot. Key support areas are defined by local lows and significant retracement levels of the upward wave. However, for market bears to yield initiative, bulls must successfully break local resistance levels. It is worth noting that warning signs appeared earlier when the options market and volatility contracts showed initial symptoms of rising nervousness.
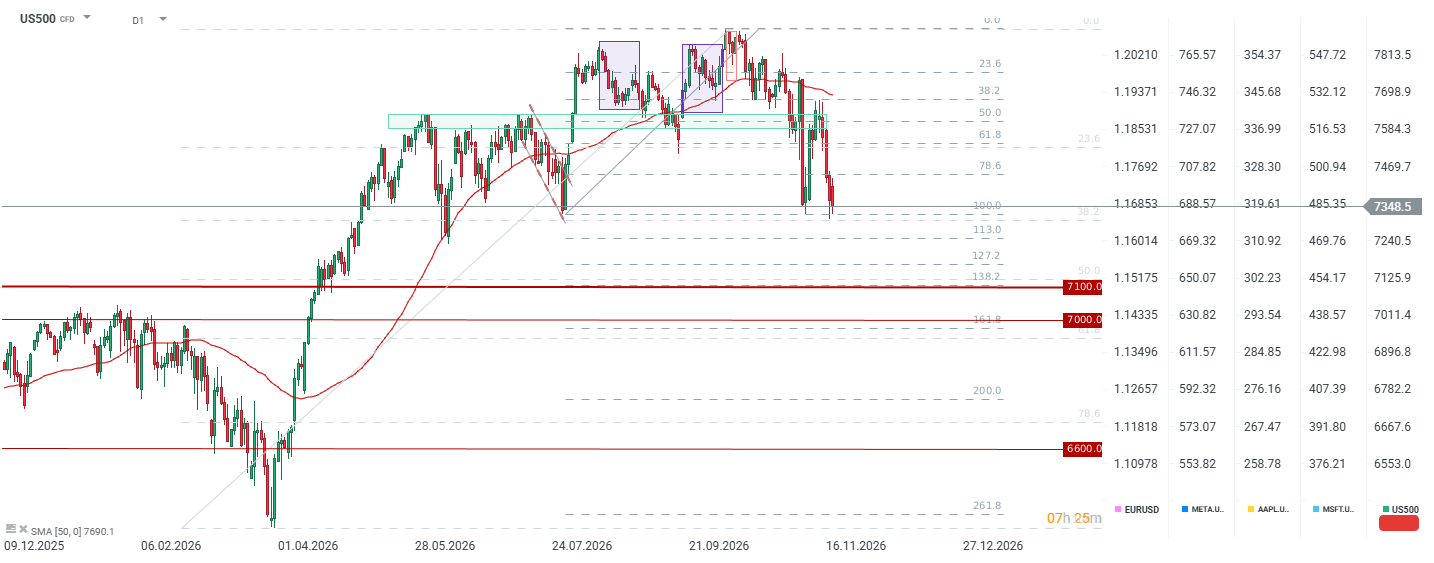
After recovery attempts in the first minutes of trading, US500 returned to declines. Breaking the 7300-7325 point zone could lead to deeper falls toward the 7100 point area. On the other hand, holding current support could mean an attempt to push toward 7400-7480. What are the scenarios for today's event?
- Bullish Scenario (dovish Fed "minutes"): If the evening FOMC meeting minutes at 20:00 signal greater Committee sensitivity to economic cooling than concern over AI investment inflation pressure, supply-side pressure will quickly neutralize. A drop in bond yields will give demand an impulse to break local resistance and return toward recent peaks. On the other hand, it is worth remembering there were 2 votes for a hike, and Warsh appeared hawkish at the last press conference.
- Bearish Scenario (hawkish tone at 20:00): If the protocol confirms a hawkish stance and fears that AI infrastructure spending will prevent inflation from rapidly reaching its target, bond yields will rise. Breaking key lower barriers will confirm a local top formation and could trigger stop-loss orders, pushing US500 to significantly lower support levels.

US OPEN: Nvidia Isn’t Enough as Wall Street Slips Back Into the Red



Market Wrap: Stocks under pressure, Iceye reaches for Avio


DAX Pulls Back for a Second Day from All-Time Highs



Daily Summary: Tech Stock Selloff Weighs on Markets, Fed Outlines AI Scenarios
This content has been created by XTB S.A. This service is provided by XTB S.A., with its registered office in Warsaw, at Prosta 67, 00-838 Warsaw, Poland, entered in the register of entrepreneurs of the National Court Register (Krajowy Rejestr Sądowy) conducted by District Court for the Capital City of Warsaw, XII Commercial Division of the National Court Register under KRS number 0000217580, REGON number 015803782 and Tax Identification Number (NIP) 527-24-43-955, with the fully paid up share capital in the amount of PLN 5.869.181,75. XTB S.A. conducts brokerage activities on the basis of the license granted by Polish Securities and Exchange Commission on 8th November 2005 No. DDM-M-4021-57-1/2005 and is supervised by Polish Supervision Authority.