


Around three hours before the U.S. market close, the S&P 500 and Nasdaq 100 are up 0.5%, despite Treasury yields climbing to levels not seen in 20 years. The European session ended on a relatively positive note, with the DAX and Euro Stoxx 50 gaining 0.5%.
- U.S. durable goods orders were unchanged, while the market had expected a 0.3% decline. The previous reading stood at 1.1%, pointing to a clear slowdown in order momentum.
- Core durable goods orders rose 0.3%, well below the 0.6% forecast and slightly weaker than the previous 0.4% increase. The data therefore point to a moderate weakening in investment demand after excluding the most volatile categories.
- Final University of Michigan data were mixed but overall slightly better than expected: consumer sentiment rose to 48.1 points, the expectations index to 46.3 points, and the current conditions index came in at 50.9 points. One-year inflation expectations stood at 4.6%, while five-year expectations remained at 3.4%.
- Iran stressed that the Strait of Hormuz will remain closed and nuclear talks with the U.S. will not resume until Tehran’s conditions are met. Despite the tough rhetoric, oil prices are retreating toward $96 per barrel from levels above $100.
- Oil is being pressured by reports that technical experts have joined the talks, which may signal a shift toward more detailed negotiations. The atmosphere is said to be becoming more constructive, although there is still no breakthrough or final agreement at this stage.
- U.S. Treasury yields have risen to their highest levels in nearly two decades. The 10-year yield is above 5.2%, while the 5-year Treasury yield has moved above 5% for the first time since 2007.
- The rise in yields is being driven mainly by high energy prices and the risk of persistent inflation, stronger-than-expected U.S. economic data, and growing expectations that the Fed may continue tightening monetary policy.
- Additional pressure came from the latest weaker 5-year Treasury auction, suggesting investors are demanding a higher risk premium. As a result, rising yields are increasing financing costs across the economy and putting more pressure on the valuations of rate-sensitive assets.
- In the U.S. market, Synopsys is up around 2%, having already given back a significant part of its earlier gains after HSBC upgraded the stock from “Hold” to “Buy” and raised its price target from $490 to $700, the highest on Wall Street. The bank expects fiscal 2027 EPS of $20.01, around 13% above consensus, based on faster earnings growth supported by a greater share of royalty revenue and rising demand for AI-related EDA tools.
- Recent results support the more optimistic outlook: in fiscal Q3, the company beat expectations on both EPS and revenue and later raised its full-year guidance. Positive calls have also come from Baird, Morgan Stanley and Benchmark, although the elevated valuation means further gains will depend heavily on continued earnings improvement and successful integration of Ansys.
- During the European session, BASF fell more than 3.5% following reports that it had made a formal proposal for a major merger with Evonik. The potential transaction would aim to help consolidate Europe’s chemical sector, which is struggling with weak demand and margin pressure.
- Airbus fell 1% after a problem was identified with an anti-corrosion coating on hundreds of A321neo aircraft, while Konecranes gained nearly 7% after announcing a share buyback and raising its guidance. Nokia, ASML and UBS also performed well, rising by around 3.3%, 2.1% and 3%, respectively.
- Trump described his meeting with Xi Jinping as “a meeting of friendship, strength and success” and said further talks would take place in China in November. The U.S. president was also reported to have told Xi that Beijing should stop supporting Tehran in its confrontation with the United States.
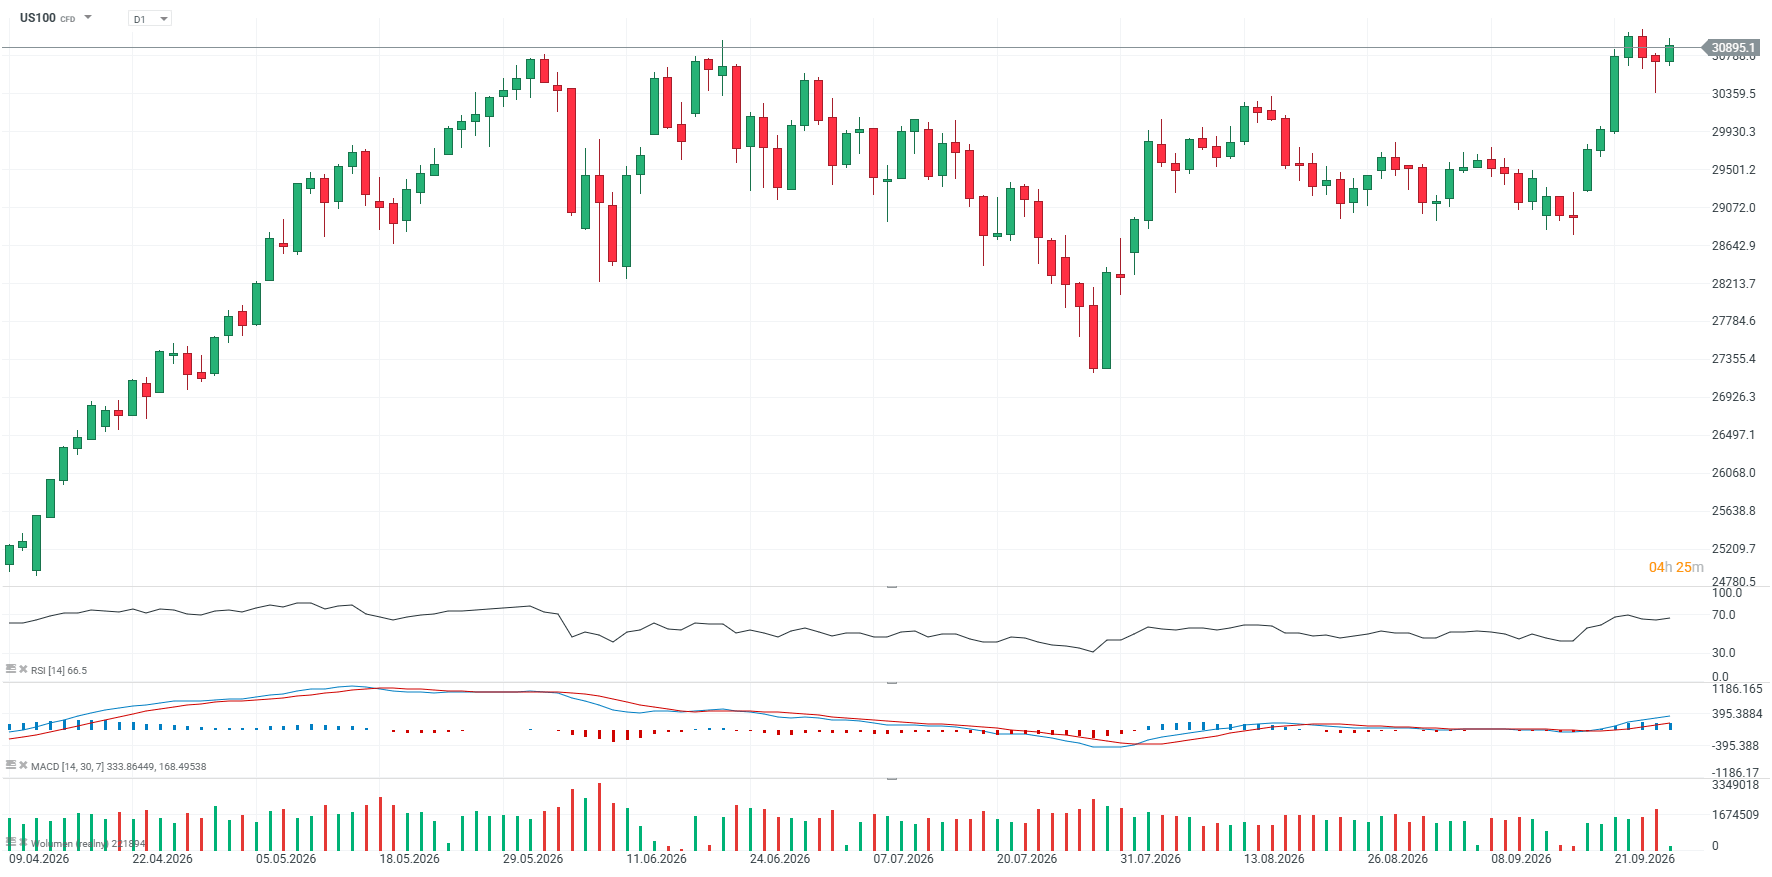
US100 chart, D1 interval
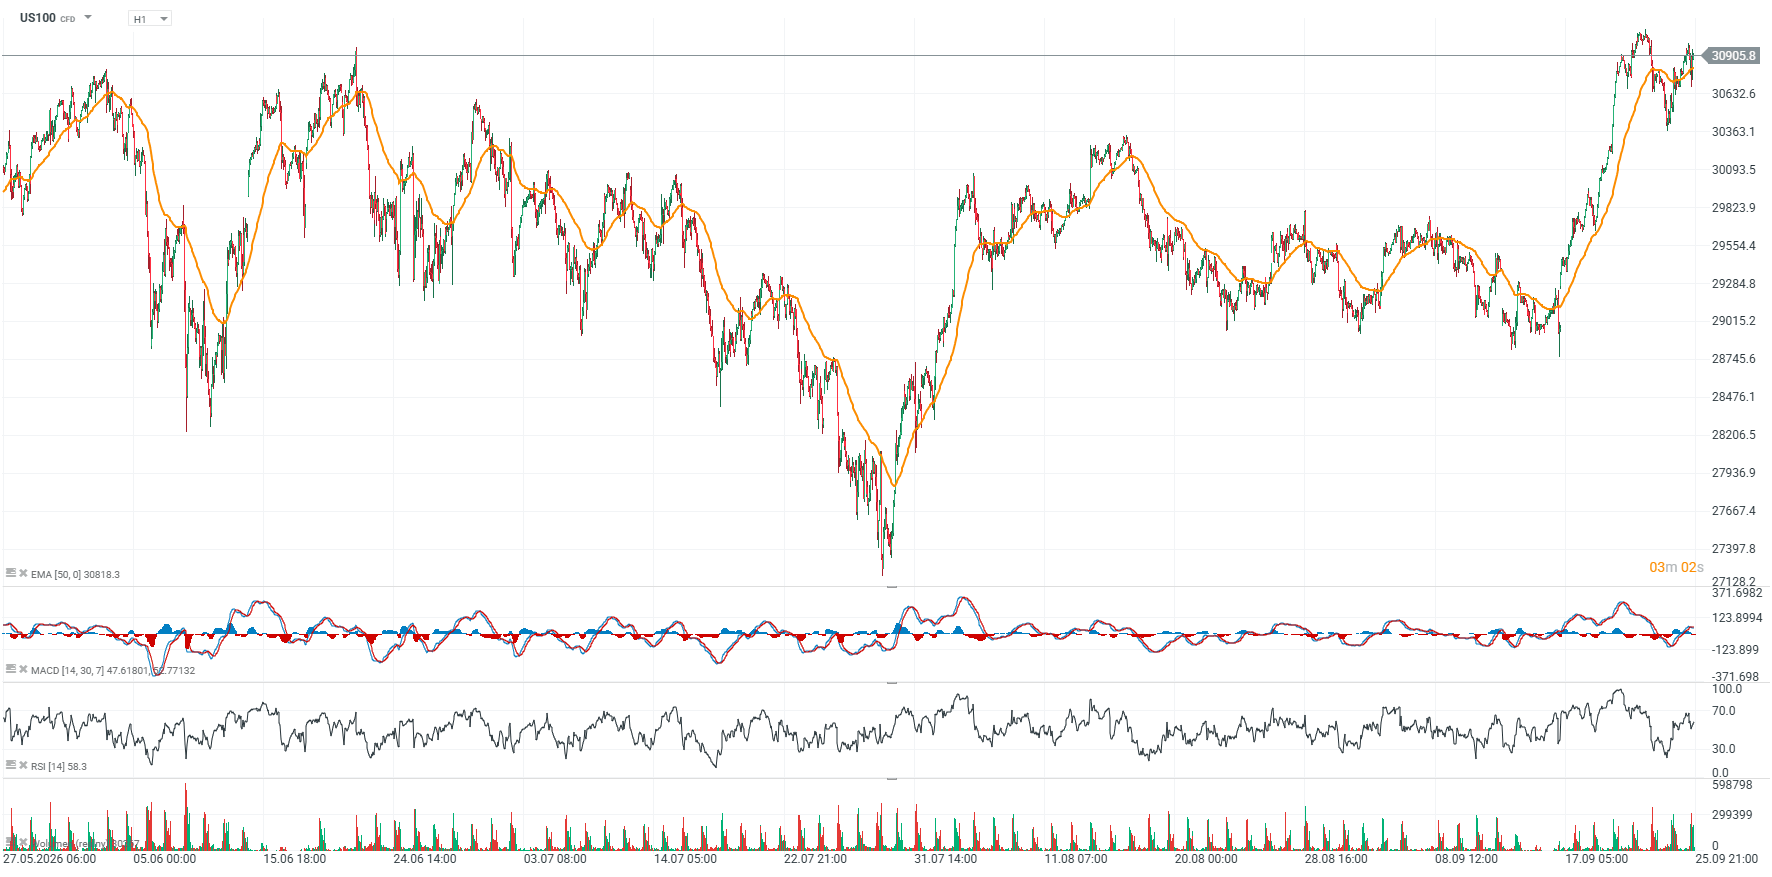
Nasdaq 100 futures are attempting to build fresh bullish momentum around two and a half weeks before the start of the U.S. earnings season. The RSI on the hourly timeframe remains close to relatively neutral levels, even though the index is trading near its all-time highs.
Source: xStation5
 Source: xStation5


3 markets to watch next week (25.09.2026)

Defense stocks after the correction 🚩 Opportunity or trap?

🚩 TNOTE falls to its lowest level since 2007


US Open: Wall Street moves higher as oil slides 🗽 Synopsys shares jump on HSBC upgrade