


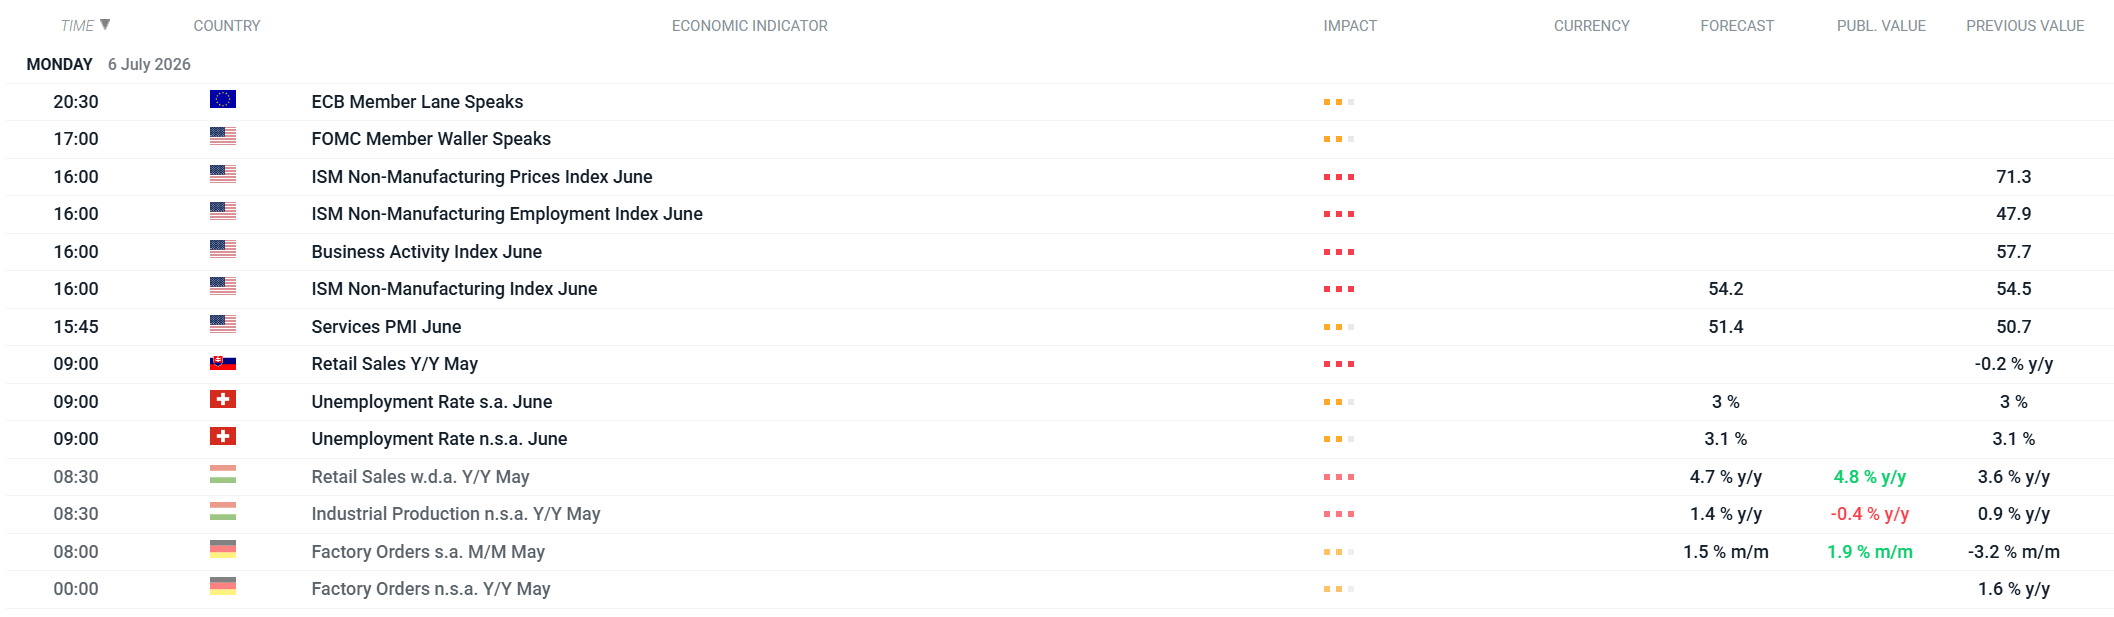
We’re kicking off a new week on the financial markets. This morning’s macroeconomic data has had a limited impact so far: Hungarian retail sales came in better than expected (4.8% y/y vs. 4.7% expected), but Hungarian industrial production came in below expectations (-0.4% y/y vs. 1.4% expected), while German factory orders exceeded forecasts (1.9% m/m vs. 1.5% expected).
This afternoon, market attention will shift to the U.S., where the PMI and ISM PMI data for the services sector for June will be released. The Services PMI (forecast: 51.4) will be released at 3:45 p.m., followed by the key ISM Non-Manufacturing Index (forecast: 54.2, previously 54.5) at 4:00 p.m., along with its components: Business Activity, Employment, and the Prices Index. In the evening, comments from central bank officials—Waller of the Fed (5:00 p.m.) and Lane of the ECB (8:30 p.m.)—are expected, which may influence expectations regarding the future path of interest rates.
Opening of European stock indices
At the start of the trading session, European stock markets are posting slight gains.
-
VSTOXX (volatility index) – +0.60%, signaling a slight increase in market nervousness
-
UK100 +0.23%, NED25 +0.13%, FRA40 +0.10%, SUI20 +0.09%, SPA35 +0.05%, ITA40 +0.04% – modest gains
-
The EU50 (-0.07%) and DE40 (-0.15%) are the only indices in negative territory, though the declines are marginal


Economic calendar: European earnings season in focus amid light macro calendar (11.11.2026)


Morning wrap: Equity indices extend rebound. CoreWeave outlook supports Nasdaq? (11.11.2026)



Daily summary: CPI reading hits markets, hawkish Fed and Wall Street selloff

Sharp retreat from gold. Higher US CPI opens the door to a 50 bps rate hike in the US