


Today’s key event on the economic calendar will be the September US labor market report, due at 12:30 PM GMT. Consensus expects nonfarm payrolls to rise by around 90,000, compared with 162,000 in the previous month, while the unemployment rate is expected to remain unchanged at 4.1%. For markets, the headline NFP figure will not be the only focus. Wage growth and labor force participation will also matter, as they could have a significant impact on expectations for the Fed’s next moves. A stronger report could push Treasury yields and the US dollar higher again, while weaker data could create more room for a dovish repricing of monetary policy.
Economic calendar
- 6:00 AM GMT – Norway: NSA unemployment rate – forecast: n/a, previous: 2.1%.
- 8:00 AM GMT – Italy: retail sales m/m – forecast: n/a, previous: -0.40%.
- 8:00 AM GMT – Italy: NSA retail sales y/y – forecast: n/a, previous: 0.80%.
- 9:00 AM GMT – Eurozone: preliminary CPI y/y – forecast: 3.7%, previous: 3.2%.
- 9:00 AM GMT – Eurozone: preliminary CPI m/m – forecast: 0.5%, previous: 0.4%.
- 9:00 AM GMT – Eurozone: preliminary core CPI y/y – forecast: 2.5%, previous: 2.4%.
- 12:30 PM GMT – US: nonfarm payrolls (NFP) – forecast: +90k, previous: +162k.
- 12:30 PM GMT – US: unemployment rate – forecast: 4.1%, previous: 4.1%.
- 12:30 PM GMT – US: average hourly earnings y/y – forecast: 3.1%, previous: 3.1%.
- 12:30 PM GMT – US: average weekly hours – forecast: 34.3, previous: 34.4.
- 12:30 PM GMT – US: average hourly earnings m/m – forecast: 0.3%, previous: 0.3%.
- 12:30 PM GMT – US: labor force participation rate – forecast: 61.6%, previous: 61.6%.
- 12:30 PM GMT – US: private payrolls – forecast: +81k, previous: +127k.
- 12:30 PM GMT – US: government payrolls – previous: +35k.
- 12:30 PM GMT – US: manufacturing payrolls – forecast: +10k, previous: +16k.
- 2:00 PM GMT – US: factory orders m/m – forecast: 0.2%, previous: 0.9%.
- 2:00 PM GMT – US: revised durable goods orders – forecast: 0.3%, previous: 0.3%.
- 2:00 PM GMT – US: revised core durable goods orders – forecast: 0.0%, previous: 0.0%.
Central bank speakers
- 7:00 AM GMT – Eurozone: ECB’s Moulin speaks.
- 7:30 AM GMT – Eurozone: ECB’s Piero Cipollone speaks.
- 11:30 AM GMT – Eurozone: ECB’s Boris Vujčić speaks.
- 2:00 PM GMT – US: Fed’s Lorie Logan speaks.
The Fed’s implied policy path shows that markets have clearly scaled back expectations for further rate hikes over the past week, although they still price in additional tightening over the coming quarters. The market is now pricing in roughly one 25 bp hike by December, around two hikes by March 2027, and just over three by July. Compared with one week ago, the entire curve has shifted lower, suggesting investors have become more cautious about an aggressive Fed tightening scenario. At the same time, the longer end of the path remains clearly more hawkish than it was four weeks ago, indicating that markets still expect persistent inflationary pressure and relatively high interest rates for longer. Today’s NFP report could therefore determine whether markets move back toward pricing in more hikes or continue reducing expectations for the scale of further tightening.
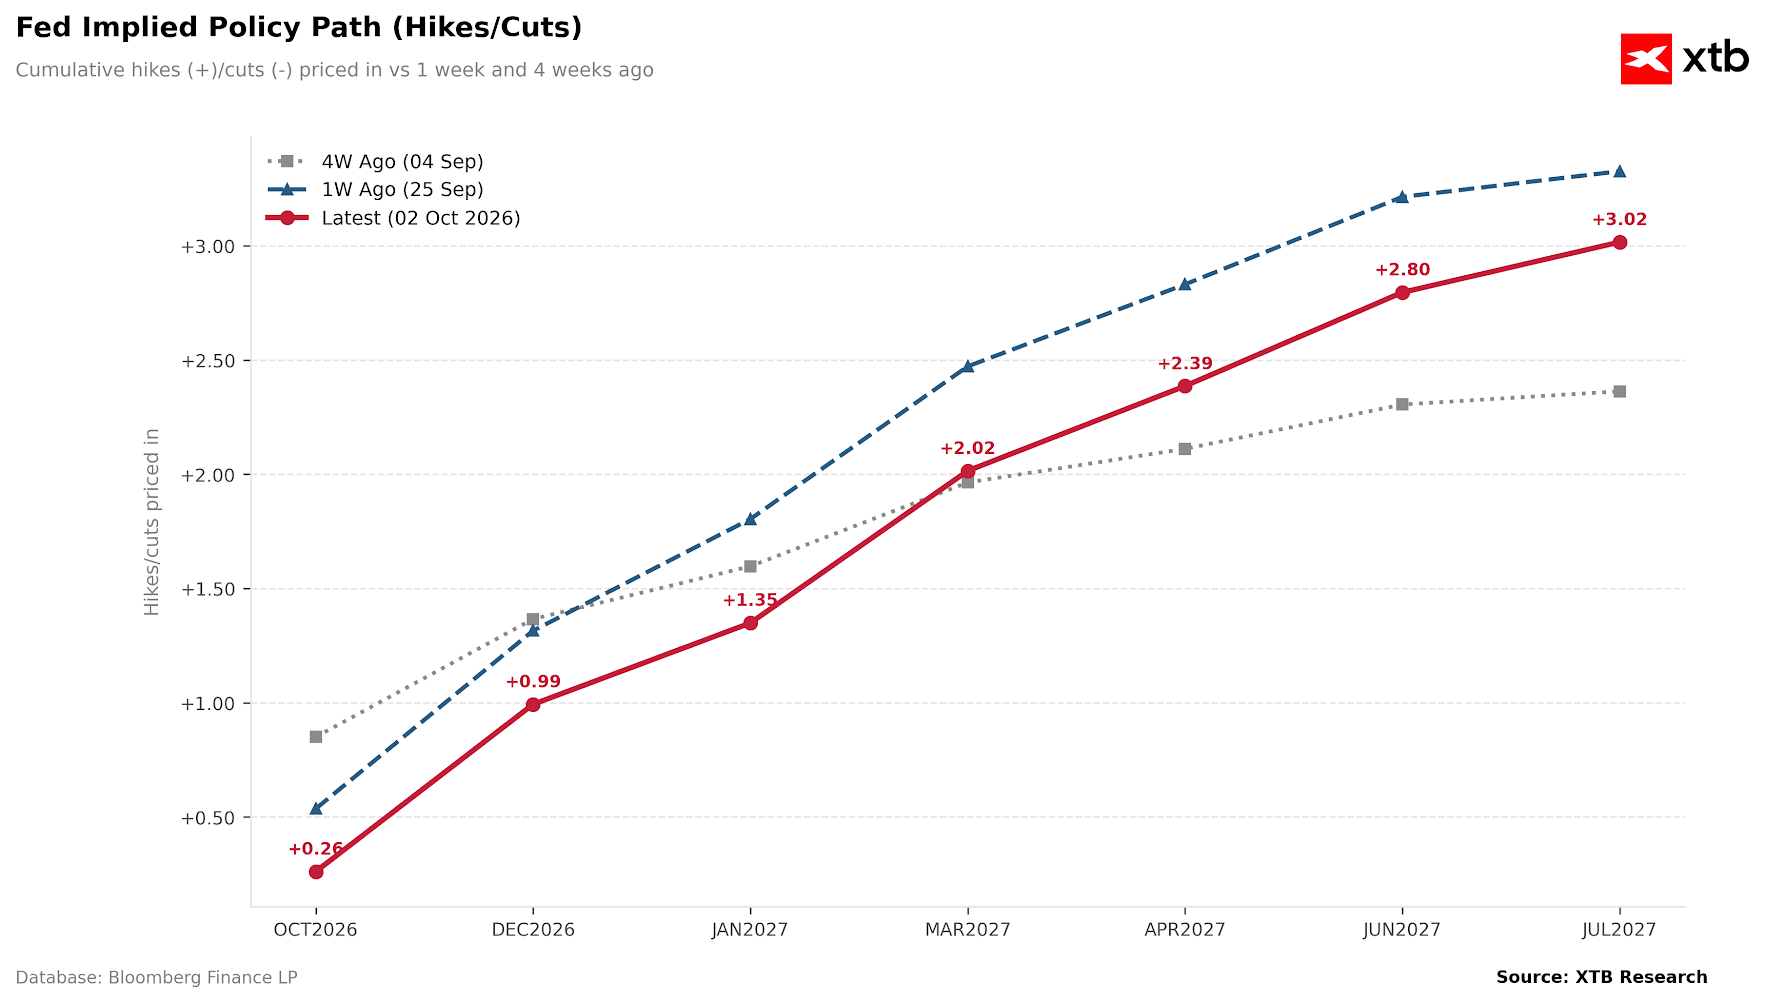 Source: Bloomberg Finance LP


Eurozone Manufacturing Shows Slightly Better Final PMI Data 💡

📉 NATGAS falls 1.2%. What about winter?

Economic Calendar - Global series of manufacturing PMI indicators and a marathon of central bankers' speeches


Morning Wrap: Tech Rally in Asia Following Micron Results and Weakening Yen Despite Hawkish BoJ