


-
US stock market indices finished yesterday's trading lower. S&P 500 dropped 1.08%, Dow Jones moved 0.81% lower and Nasdaq declined 0.73%. Russell 2000 dropped 1.49%
-
Stocks in Asia also traded lower today, although with few exceptions. S&P/ASX 200 dropped 1.20%, Kospi slipped 0.5% and indices from China traded up to 1.6% lower. Nikkei was outperformer, gaining 0.1%
-
DAX futures point to a lower opening of the European cash trading session
-
Chinese authorities put some neighborhoods in Shanghai back into lockdown following a spike in local Covid-19 cases. Mass testing will also be conducted
-
White House press secretary Karine Jean-Pierre said that administration expects tomorrow's inflation data to be elevated
-
RBNZ plans to start selling government bonds purchased as part of its QE programme in July 2022. Balance sheet will be reduced at pace of NZ$5 billion per year until holdings are reduced to zero within around 5 years
-
Chinese exports increased 16.9% YoY in May in USD terms (exp. +8.0% YoY). Imports were 4.1% YoY higher (exp. +2.0% YoY)
-
Cryptocurrencies are trading lower but the scale of decline is not major. Ethereum drops 0.4% while Bitcoin trades flat
-
Brent and WTI trade around 0.1% lower on the day
-
Platinum pulls back, gold trade flat while palladium and silver advance
-
CHF and JPY are the best performing major currencies while AUD and CAD lag the most
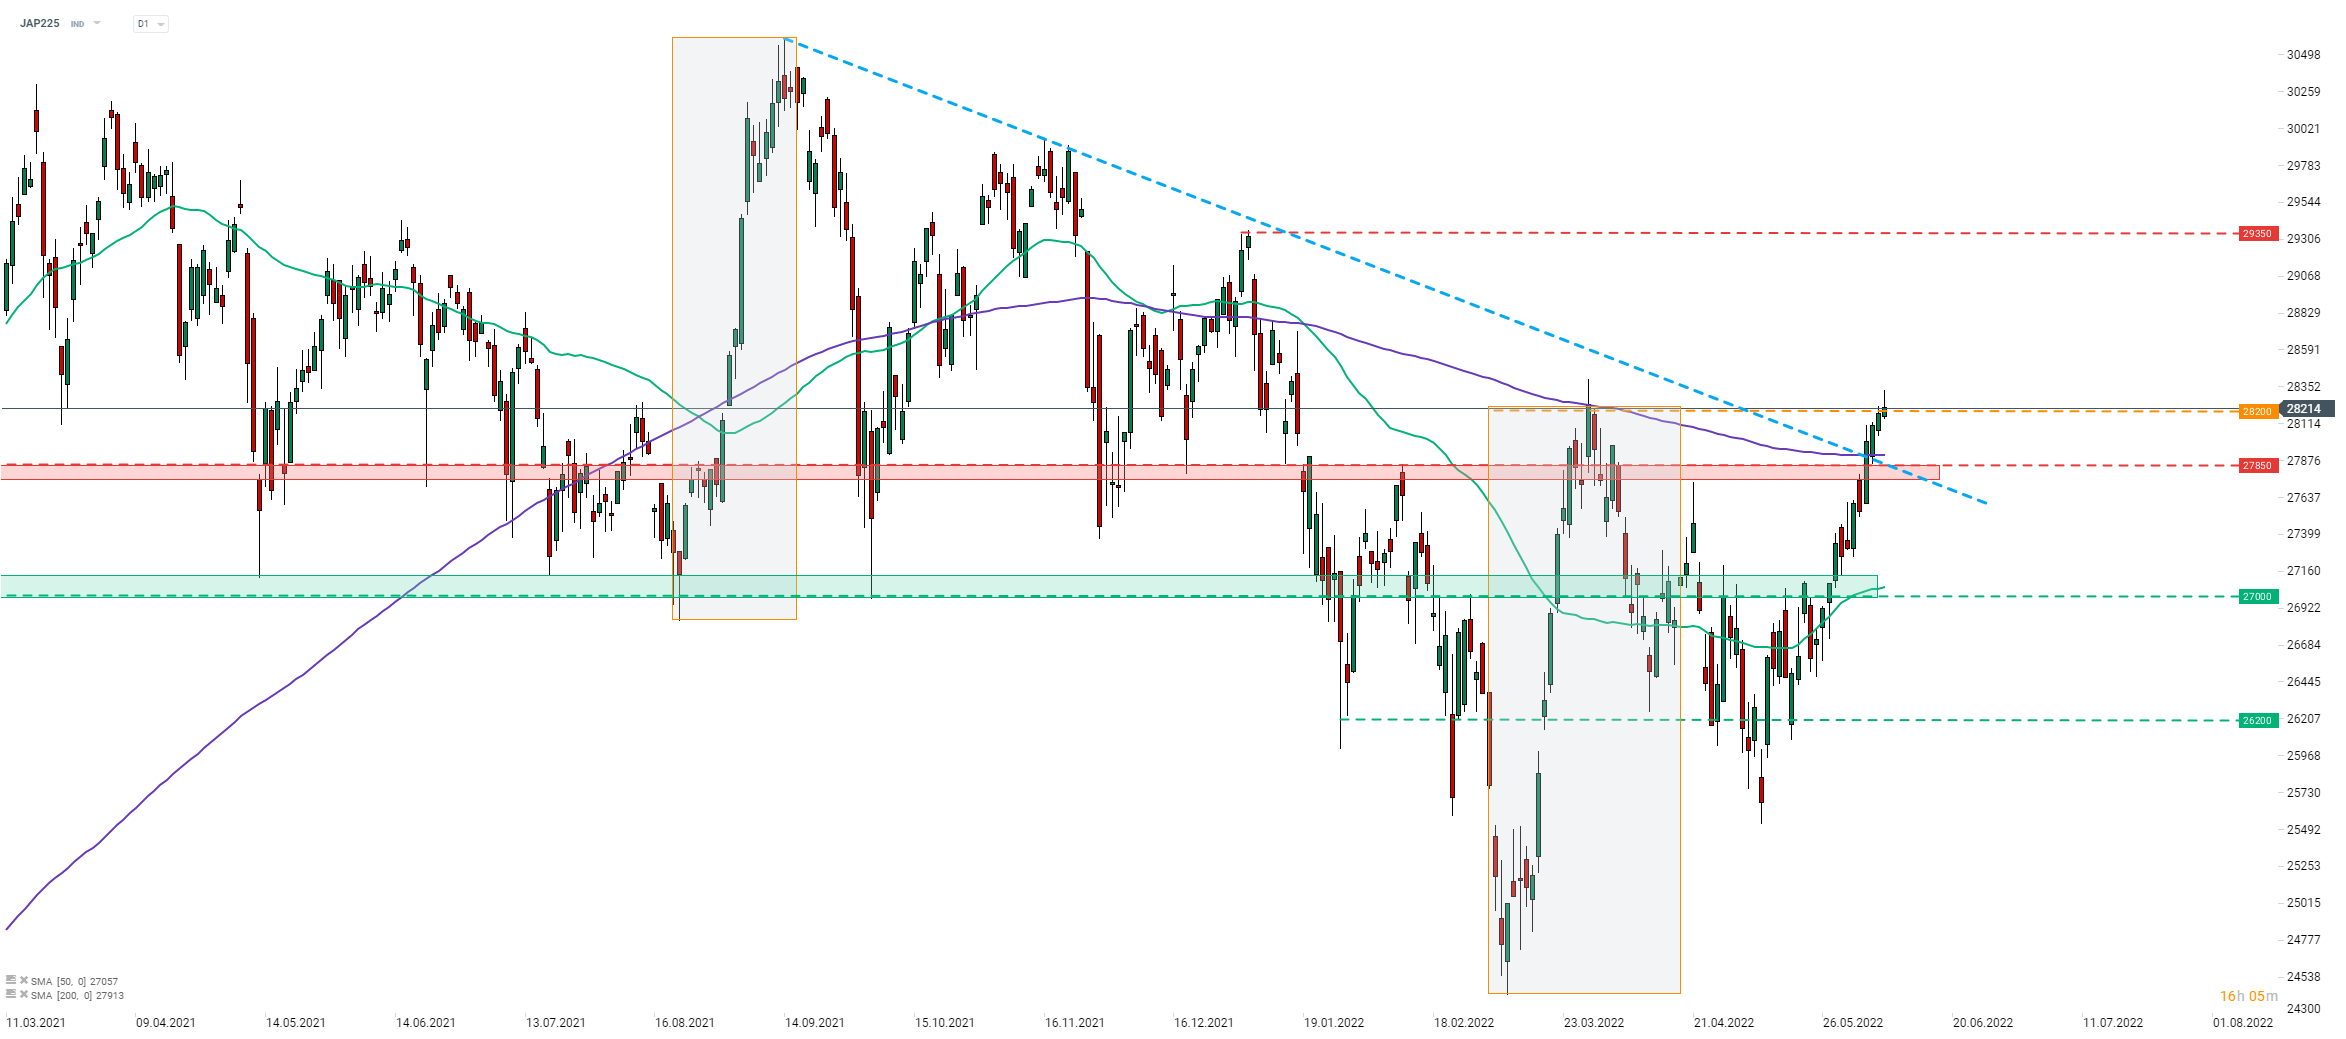 Unlike other indices from the Asia-Pacific region, Nikkei (JAP225) managed to post small gains today. The index is testing the upper limit of the Overbalance structure and a break above would hint at a trend reversal. Source: xStation5



📊Daily Summary - Hawkish Fed raises rates and signals more. Dollar gains while gold falls


Hawkish move from the Fed! Warsh takes no prisoners in the fight against inflation. US500 at its lowest since August 3, and gold already below $4,300.


US OPEN: Wall Street seeks rebound ahead of Fed decision
What does Wall Street expect from the S&P 500 next quarter? 🗽 Key sectors to watch