


Wall Street index futures are gaining between 0.2% and 0.3%, while investors’ attention today will focus primarily on the September US labor market report: NFP, the unemployment rate and wage growth, which could have the strongest impact on expectations for the Fed. In Europe, attention will turn to the preliminary euro area CPI reading, particularly core inflation, as a stronger print could limit the ECB’s room to ease monetary policy.
- Despite the cautious gains in US equities, demand for safe-haven assets continues to dominate global bond markets. Yields are falling in the US, Japan, Australia and New Zealand, while US Treasuries are holding most of Thursday’s price gains. The defensive tone reflects a combination of risks, including tensions in credit markets, elevated commodity prices, persistent inflationary pressure, and political and fiscal uncertainty.
- Europe remains the weaker link. Concerns over France’s fiscal and political outlook continue to support a higher risk premium on French debt, while German bonds remain relatively stable. Asian indices are also down around 0.6%, with Chinese Hang Seng Index falling almost 3%.
- Sentiment across equity markets is clearly weaker. Asian indices are heading for their worst week since July, while European equities are on track for their weakest week since April. Pressure is also visible in the UK, where long-dated gilt yields briefly climbed above 6%, highlighting the scale of stress in the bond market.
- The US Dollar Index remains strong and is heading for a third consecutive weekly gain, supported by the relative resilience of the US economy. Brent crude has paused its advance and is trading near $102 after two consecutive positive sessions, while copper is heading for its biggest weekly decline since May.
- For today’s US NFP report at 14:30 CET, consensus expects nonfarm payrolls to rise by around 90,000, while the unemployment rate is seen holding at 4.1%. Geopolitics also remains an important risk factor, particularly amid tensions between Washington and Tehran, which continue to sustain uncertainty around inflation and energy prices.
- Donald Trump said that, based on the information available so far, Iran may have been behind the attempted terrorist attack in Israel.
US500 chart (H1 interval)
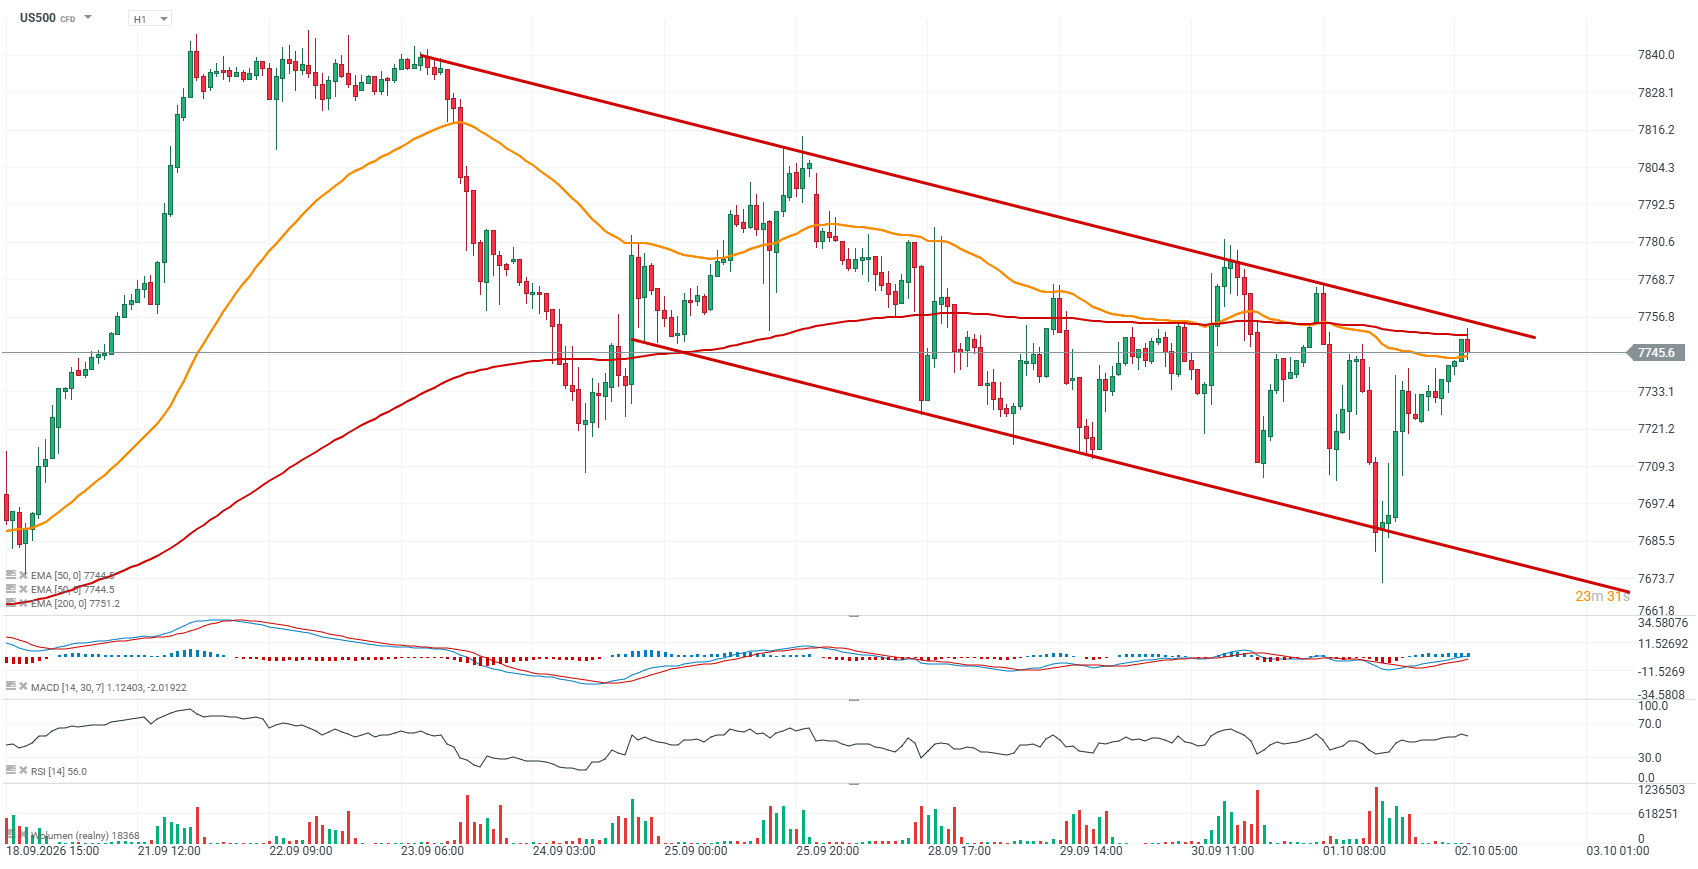 Source: XTB



Daily Summary: Wall Street Recovers as Micron Shines and Oil Prices Rise Again

Stock of the Week: Micron. The Memory Cycle in the Age of Artificial Intelligence


US Open: Micron restores faith in the never-ending AI boom

⛩️Chart of the Day: JP225, Nikkei Plays Its Own Tune (01.10.2026)