

- Asian manufacturing PMIs show stable expansion, led by China at 52.0 pts and Japan at 53.3 pts.
- US manufacturing ISM report and producer price pressures dictate the short-term direction for the US dollar.
- Geopolitical tension in the Persian Gulf increases the geopolitical risk premium for crude oil markets.
- Apple and Palantir earnings reports release after the market close to influence Wall Street sentiment.
- Brent crude trades around 105.80 USD per barrel while testing key support near the 100.00 USD level.

- Asian manufacturing PMIs show stable expansion, led by China at 52.0 pts and Japan at 53.3 pts.
- US manufacturing ISM report and producer price pressures dictate the short-term direction for the US dollar.
- Geopolitical tension in the Persian Gulf increases the geopolitical risk premium for crude oil markets.
- Apple and Palantir earnings reports release after the market close to influence Wall Street sentiment.
- Brent crude trades around 105.80 USD per barrel while testing key support near the 100.00 USD level.
The start of the week is marked by the release of industrial sentiment indicators from around the world. The Asian session brought moderately positive signals – the Chinese PMI index remained in expansion territory at 52.0 pts (in line with consensus), while Japanese industry maintained a stable growth pace (PMI at 53.3 pts).
From Australia came data showing increased inflationary pressure (the MI inflation gauge accelerated to 0.5% m/m) and a clear rebound in building approvals (5.1% m/m vs forecast 1.8%). Meanwhile, annual commodity price growth slowed to 12.5% y/y.
Later in the day, market attention will shift to Europe and the United States, where the key reference point will be the US manufacturing ISM report and its prices sub-index, which will indicate the scale of current cost pressures faced by producers. On the geopolitical front, investors are monitoring an incident in the Persian Gulf, where a tanker was hit by missiles off the coast of Saudi Arabia, as well as a diplomatic and technological offensive in the Middle East in the field of artificial intelligence. In the evening, financial reports from Wall Street giants, including Apple and Palantir, could shake the markets.
Key Releases from the Asian Session
- Australia: Melbourne Institute (MI) Inflation Gauge came in at 0.5% m/m (previously 0.3% m/m), signaling persistent price pressure down under.
- Australia: Building approvals rose 5.1% m/m, significantly beating market consensus (1.8% m/m) after a previous drop of 5.2% m/m, indicating a strong recovery in the construction sector.
- Japan: Final Manufacturing PMI came in at 53.3 pts (in line with consensus and flash reading), confirming stable expansion in the Japanese manufacturing sector.
- China: Manufacturing PMI stood at 52.0 pts (consensus: 52.0 pts; previous: 52.1 pts), pointing to a continuation of moderate recovery in the Chinese economy.
- Australia: Commodity Index slowed to 12.5% y/y from 15.9% y/y recorded in the previous period.
Macroeconomic Calendar
- 08:00 Germany - Retail Sales m/m. Consensus: 0.4%. Previous: 1.3%.
- 08:30 Switzerland - Retail Sales y/y. Consensus: 3.0%. Previous: 3.2%.
- 09:15 Spain - Manufacturing PMI. Consensus: 50.4. Previous: 51.0.
- 09:30 Switzerland - Manufacturing PMI. Consensus: 55.3. Previous: 55.3.
- 09:45 Italy - Manufacturing PMI. Consensus: 49.9. Previous: 50.4.
- 09:50 France - Final Manufacturing PMI. Consensus: 49.3. Previous: 49.3.
- 09:55 Germany - Final Manufacturing PMI. Consensus: 54.2. Previous: 54.2.
- 10:00 Eurozone - Final Manufacturing PMI. Consensus: 52.4. Previous: 52.4.
- 10:30 United Kingdom - Final Manufacturing PMI. Consensus: 52.8. Previous: 52.8.
- 13:00 Eurozone - Speech by Bundesbank President Joachim Nagel
- 15:30 Canada - Manufacturing PMI. Consensus: N/A. Previous: 51.5.
- 15:45 USA - Final Manufacturing PMI. Consensus: 56.0. Previous: 56.0.
- 16:00 USA - Manufacturing ISM. Consensus: 54.5. Previous: 54.5.
- 16:00 USA - Construction Spending m/m. Consensus: 0.4%. Previous: 0.9%.
- 16:00 USA - ISM Manufacturing Prices Paid. Consensus: 77.2. Previous: 77.9.
- 22:45 New Zealand - Building Consents m/m. Consensus: N/A. Previous: 5.6%.
Corporate Earnings Results
- Apple Inc. (AAPL) – after market close, EPS forecast: $1.98. The world's largest tech company, a key barometer of global consumer electronics demand and sales health in the Chinese market.
- Palantir Technologies Inc. (PLTR) – after market close, EPS forecast: $0.33. A major player in data analytics and artificial intelligence, an indicator of the commercialization rate of AI technology in government and corporate sectors.
- Vertex Pharmaceuticals Incorporated (VRTX) – after market close, EPS forecast: $4.36. A leading biotech representative, crucial for assessing margins and revenues from innovative drug therapies.
- Marriott International (MAR) – before market open, EPS forecast: $2.87. Global hospitality leader, a key indicator of consumer demand strength in the tourism and business travel segments.
- Williams Companies, Inc. (WMB) – after market close, EPS forecast: $0.55. A significant component of the US natural gas transportation infrastructure.
- Diamondback Energy, Inc. (FANG) – after market close, EPS forecast: $4.92. A prominent shale oil producer in the US, serving as a barometer for the profitability of the US extraction sector.
- Realty Income Corporation (O) – after market close, EPS forecast: $1.11. A leading REIT reflecting the health of the commercial real estate market under current interest rate conditions.
- Estée Lauder Companies, Inc. (EL) – before market open, EPS forecast: $0.52. A gauge for luxury goods spending and a direct indicator of consumption recovery in Asia.
- Other companies reporting results: Entergy Corporation, IDEXX Laboratories, Public Service Enterprise Group, ON Semiconductor, Ryanair Holdings, Fox Corporation, Roku, Loews Corporation, Tower Semiconductor, Pershing Square, SBA Communications, Viper Energy, POSCO Holdings, Corebridge Financial, Check Point Software Technologies, and Equitable Holdings.
Markets to Watch
- USD/PLN and EUR/USD: The US ISM index reading and prices paid component at 16:00 will determine the short-term direction for the US dollar; a higher inflation component reading could limit room for Fed easing, strengthening the dollar.
- Crude Oil (Brent / WTI): The incident involving a tanker hit by two missiles in the Persian Gulf near Saudi Arabia increases the geopolitical risk premium in a key energy transit hub.
- Nasdaq 100: The US tech index will be influenced by the release of US economic activity indicators, and will react directly to Apple and Palantir earnings after the closing bell.
Technical Outlook on Oil
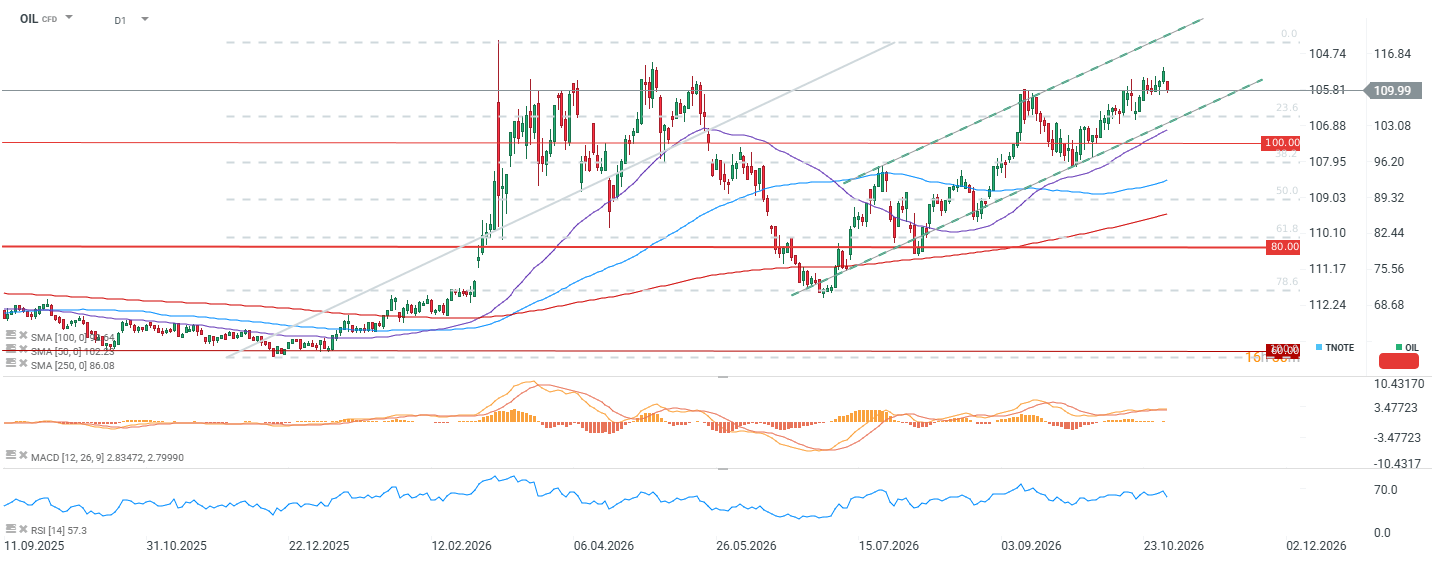
- Brent Crude is trading around $105.8 per barrel, correcting from recent highs in the $112–$113 range that resulted from escalating Middle East tensions and attacks in the Strait of Hormuz.
- The price is currently heading toward the lower boundary of an ascending trend channel and the 23.6% Fibonacci retracement level, making this area a key test for buyers.
- The moving average structure remains bullish: the price is above the 50 SMA (approx. $102.2) and significantly above the 250 SMA (approx. $86.1), confirming the intact long-term uptrend initiated in September 2025.
- The RSI at 57.3 remains in neutral territory with a slight demand bias, while the MACD histogram (2.83 vs signal line 2.80) is flattening noticeably, signaling a clear loss of momentum after the dynamic upward move.
- Immediate support is marked around the round level of $100, aligning with a psychological barrier and former resistance from the first half of the year. A break below this level would open the path toward the 50% retracement level (approx. $96), and subsequently toward the $89–$90 zone.
- On the resistance side, the recent high zone around $112–$113 remains key. Overcoming it and holding above that threshold would open up space for a continuation of the uptrend toward $115, leading to a breakout of current contract high levels.
Scenarios:
- Bullish scenario: Defending the upward trendline and the $100–$102 zone alongside an easing of geopolitical risks (de-escalation around Iran) could prompt buyers to launch another test of the highs around $112–$113, and ultimately target $116–$117.
- Bearish scenario: A sustained breakdown below the $100 support level, accompanied by diminishing supply fears (e.g., signs of de-escalation in the Middle East or weaker global demand), would open the way for a deeper correction toward the 50-day moving average and the $89–$96 zone.



📊Morning Wrap: Oil falls after Qatar talks. China injects liquidity, while the US prepares for elections.


💥Daily Summary: Tech Sector Crash on Wall Street and Historic Attack on Binance


🔴Three Markets to Watch Next Week: US500, BITCOIN, EURUSD (30.10.2026)
There is no good scenario for the euro today
This content has been created by XTB S.A. This service is provided by XTB S.A., with its registered office in Warsaw, at Prosta 67, 00-838 Warsaw, Poland, entered in the register of entrepreneurs of the National Court Register (Krajowy Rejestr Sądowy) conducted by District Court for the Capital City of Warsaw, XII Commercial Division of the National Court Register under KRS number 0000217580, REGON number 015803782 and Tax Identification Number (NIP) 527-24-43-955, with the fully paid up share capital in the amount of PLN 5.869.181,75. XTB S.A. conducts brokerage activities on the basis of the license granted by Polish Securities and Exchange Commission on 8th November 2005 No. DDM-M-4021-57-1/2005 and is supervised by Polish Supervision Authority.