

- Risk aversion dominates trading as the euro weakens against all G10 currencies.
- EURUSD drops below 1.12.
- French 10-year government bond yield spreads widen as fiscal deficit concerns grow.
- Crude oil prices advance toward 102 USD per barrel following tanker attacks in the Strait of Hormuz.
- European equity indices post losses led by semiconductor stocks, automakers, and banks.
Wednesday's trading session is dominated by rising risk aversion. The euro is weakening against all other G10 currencies, government bond yields are climbing higher once again, and surging crude oil prices are weighing on European stock indices, almost all of which are posting losses today.
EURUSD drops below 1.12
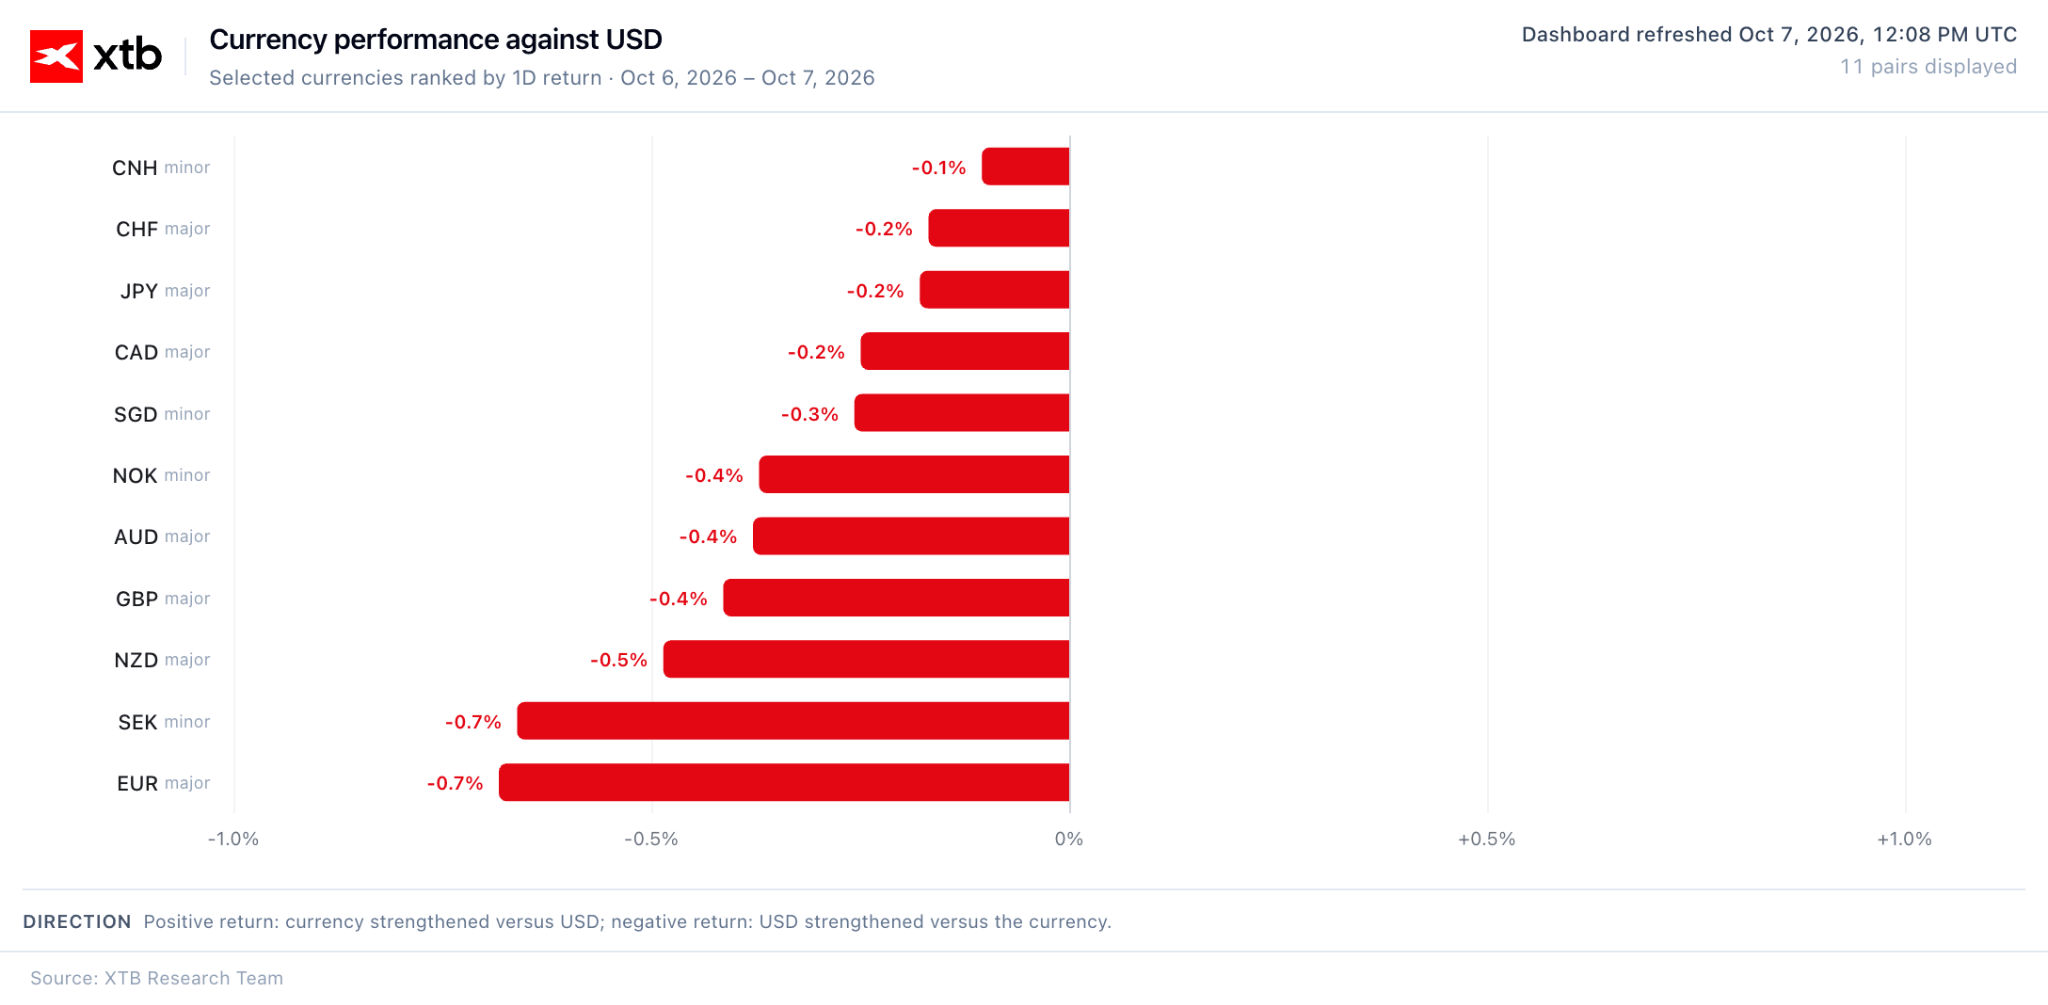
The EURUSD currency pair is down over 0.6% today, breaking below the 1.12 mark. A combination of factors is weighing on the single currency: US dollar strength, elevated crude oil prices, a global rise in sovereign bond yields, broader investor risk aversion, heightened fiscal and political risks in France, and the prospect of the ECB taking a less hawkish monetary policy path.
Figure 1: Performance of Major Currencies Against the US Dollar (07.10.2026)
 Source: XTB Research, 07.10.2026
France in the spotlight
The yield spread between French and German 10-year government bonds has widened further, approaching levels not seen since 2011. While the yield on French debt (around 4.9%) remains below that of US Treasuries (over 5.3%), the trajectory is causing concern among investors.
The primary source of anxiety is not the level of debt itself (just over 115% of GDP in 2025 and around 119% of GDP in 2026), but rather the absence of a credible stabilization trajectory. France's public sector deficit is projected to reach 5.4% of GDP in 2026, significantly above the original target of 4.6% of GDP. This is particularly problematic given that the domestic economy remains in stagnation, with GDP growth forecasts for the current year hovering around 0.5%.
Consequently, the minority government cannot rely on growing out of the problem and must begin pushing through politically unpopular budget cuts. On 1 October, it presented its draft budget for 2027. It targets a modest deficit reduction to 5% of GDP, primarily achieved through freezing nominal expenditure (excluding defense and a few other sectors). It is worth noting that the original target for 2026 was lower, at 4.6%.
Markets remain skeptical regarding the effectiveness of the planned tightening. Somewhat ambitious GDP growth assumptions (1%) are also raising concern. However, the key risk lies in the fact that the budget requires parliamentary approval, where the government lacks a majority. With presidential elections scheduled for 2027, the risk of political dilution of these spending cuts is further heightened.
Energy commodities
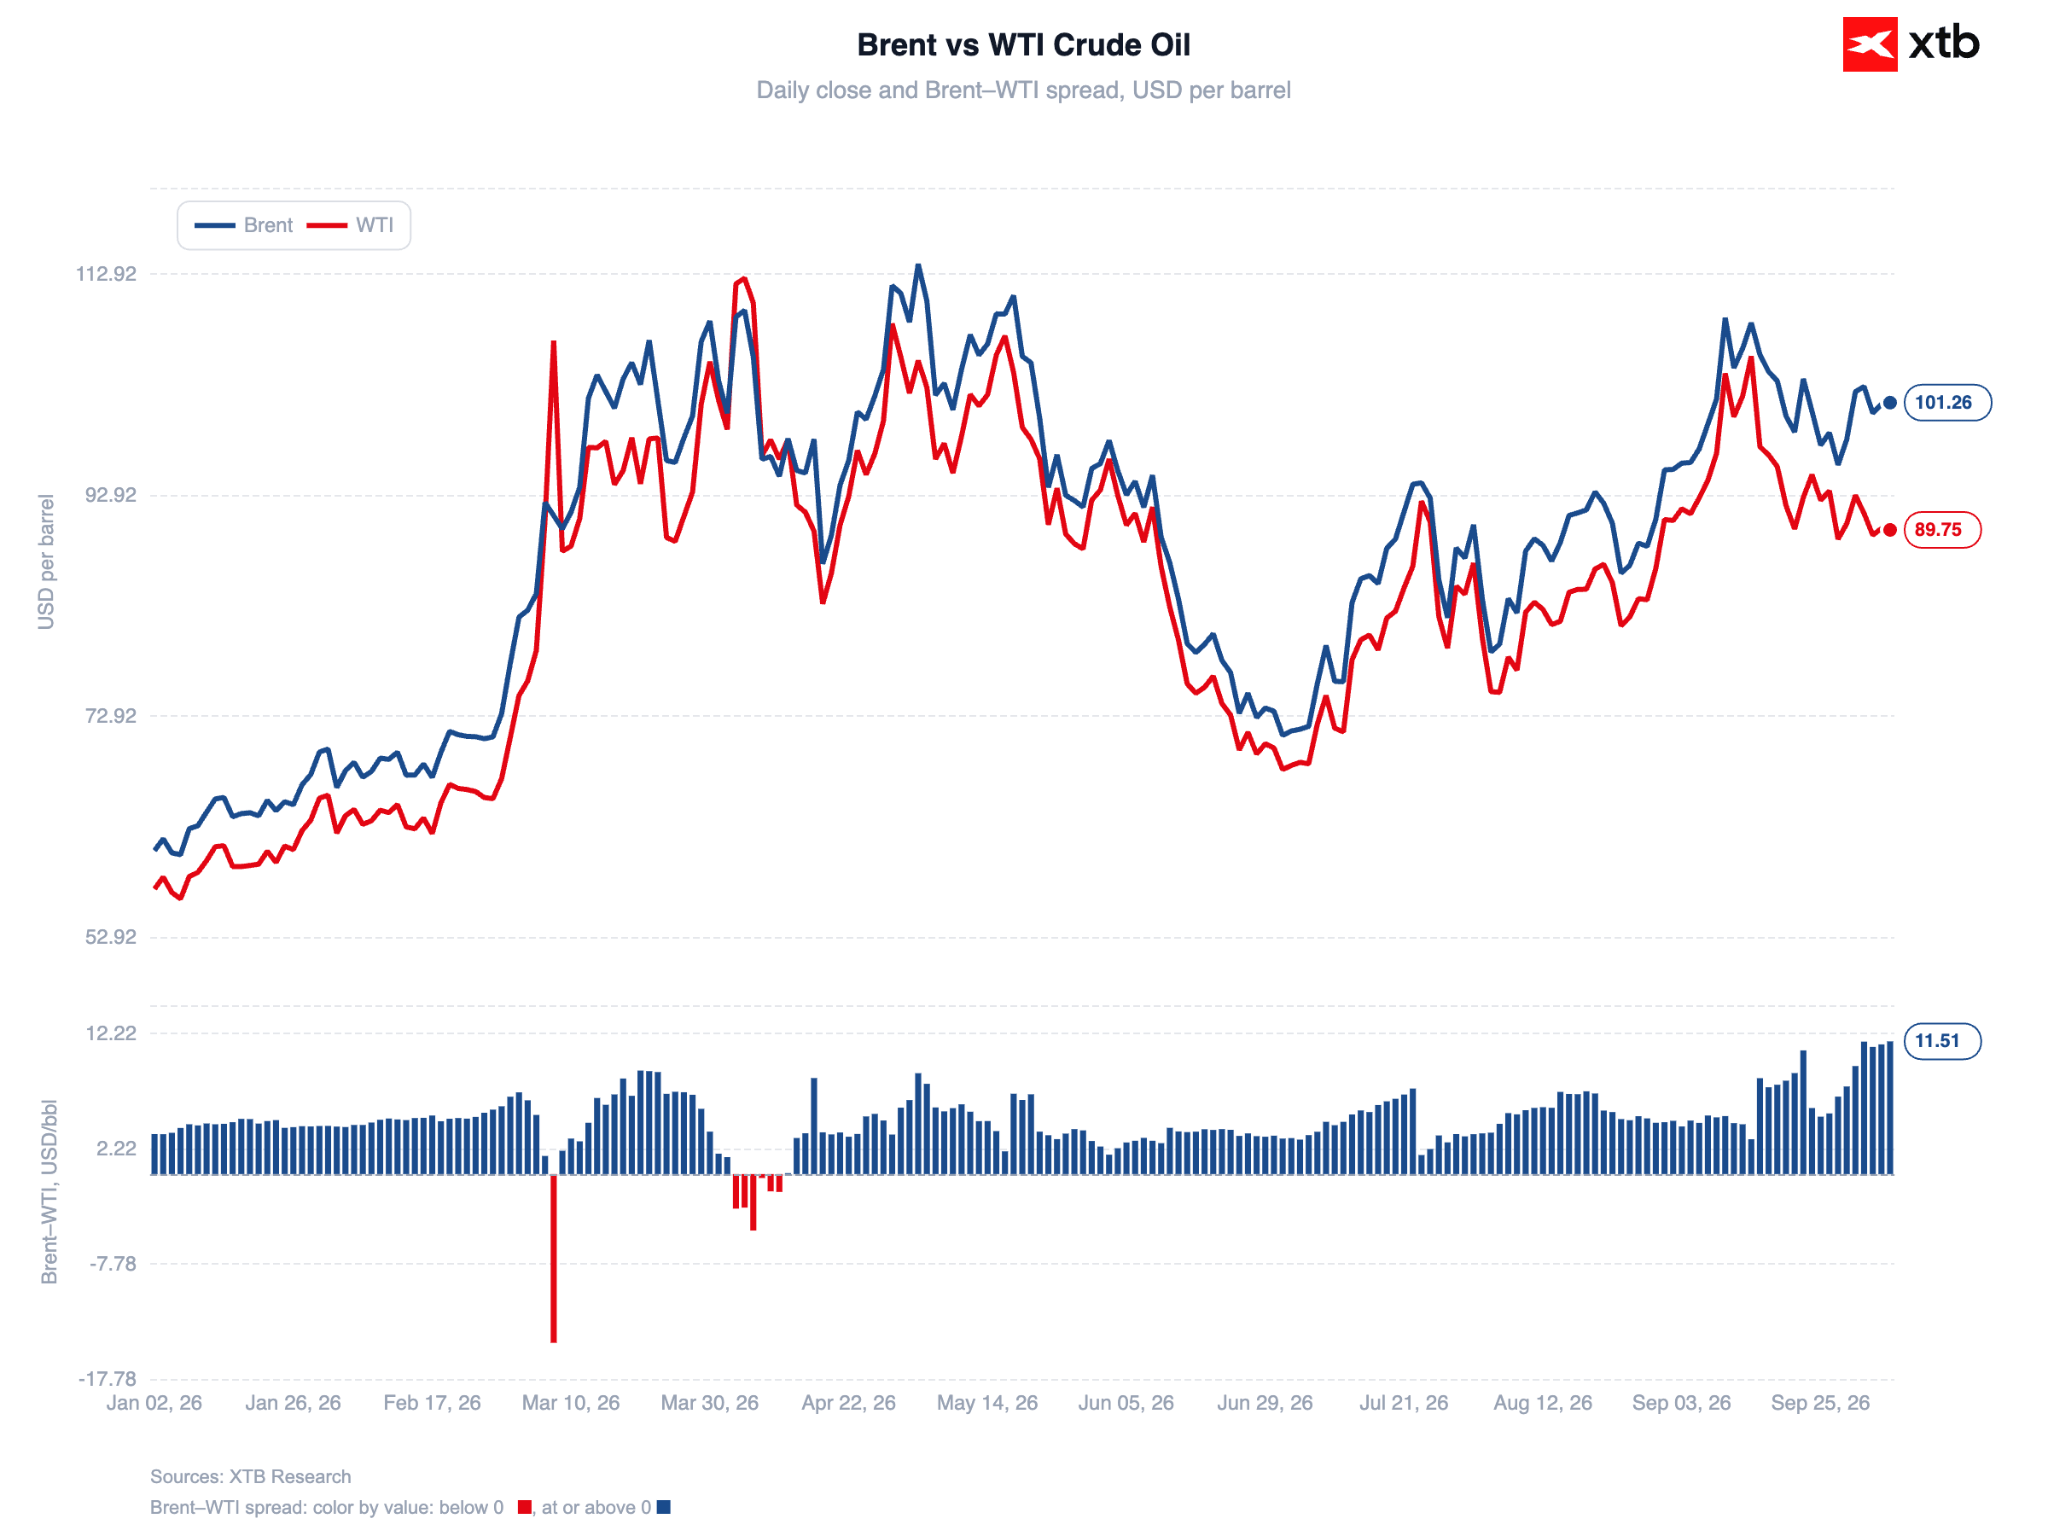
Crude oil prices are advancing in response to intensifying attacks on tankers in the Strait of Hormuz. Brent crude is up approximately 1.3% today, approaching $102 per barrel, while WTI has gained over half a percent to trade near $90. In October alone, nine attacks have already been recorded in the area, matching the total number seen across the entire Strait of Hormuz and Persian Gulf region throughout September. Oil flows from the region have recovered to roughly 80% of pre-conflict levels, though the situation regarding refined fuels remains significantly more constrained.
Figure 2: Brent and WTI Crude Oil (2026)
 Source: XTB Research, 07.10.2026
Equity markets
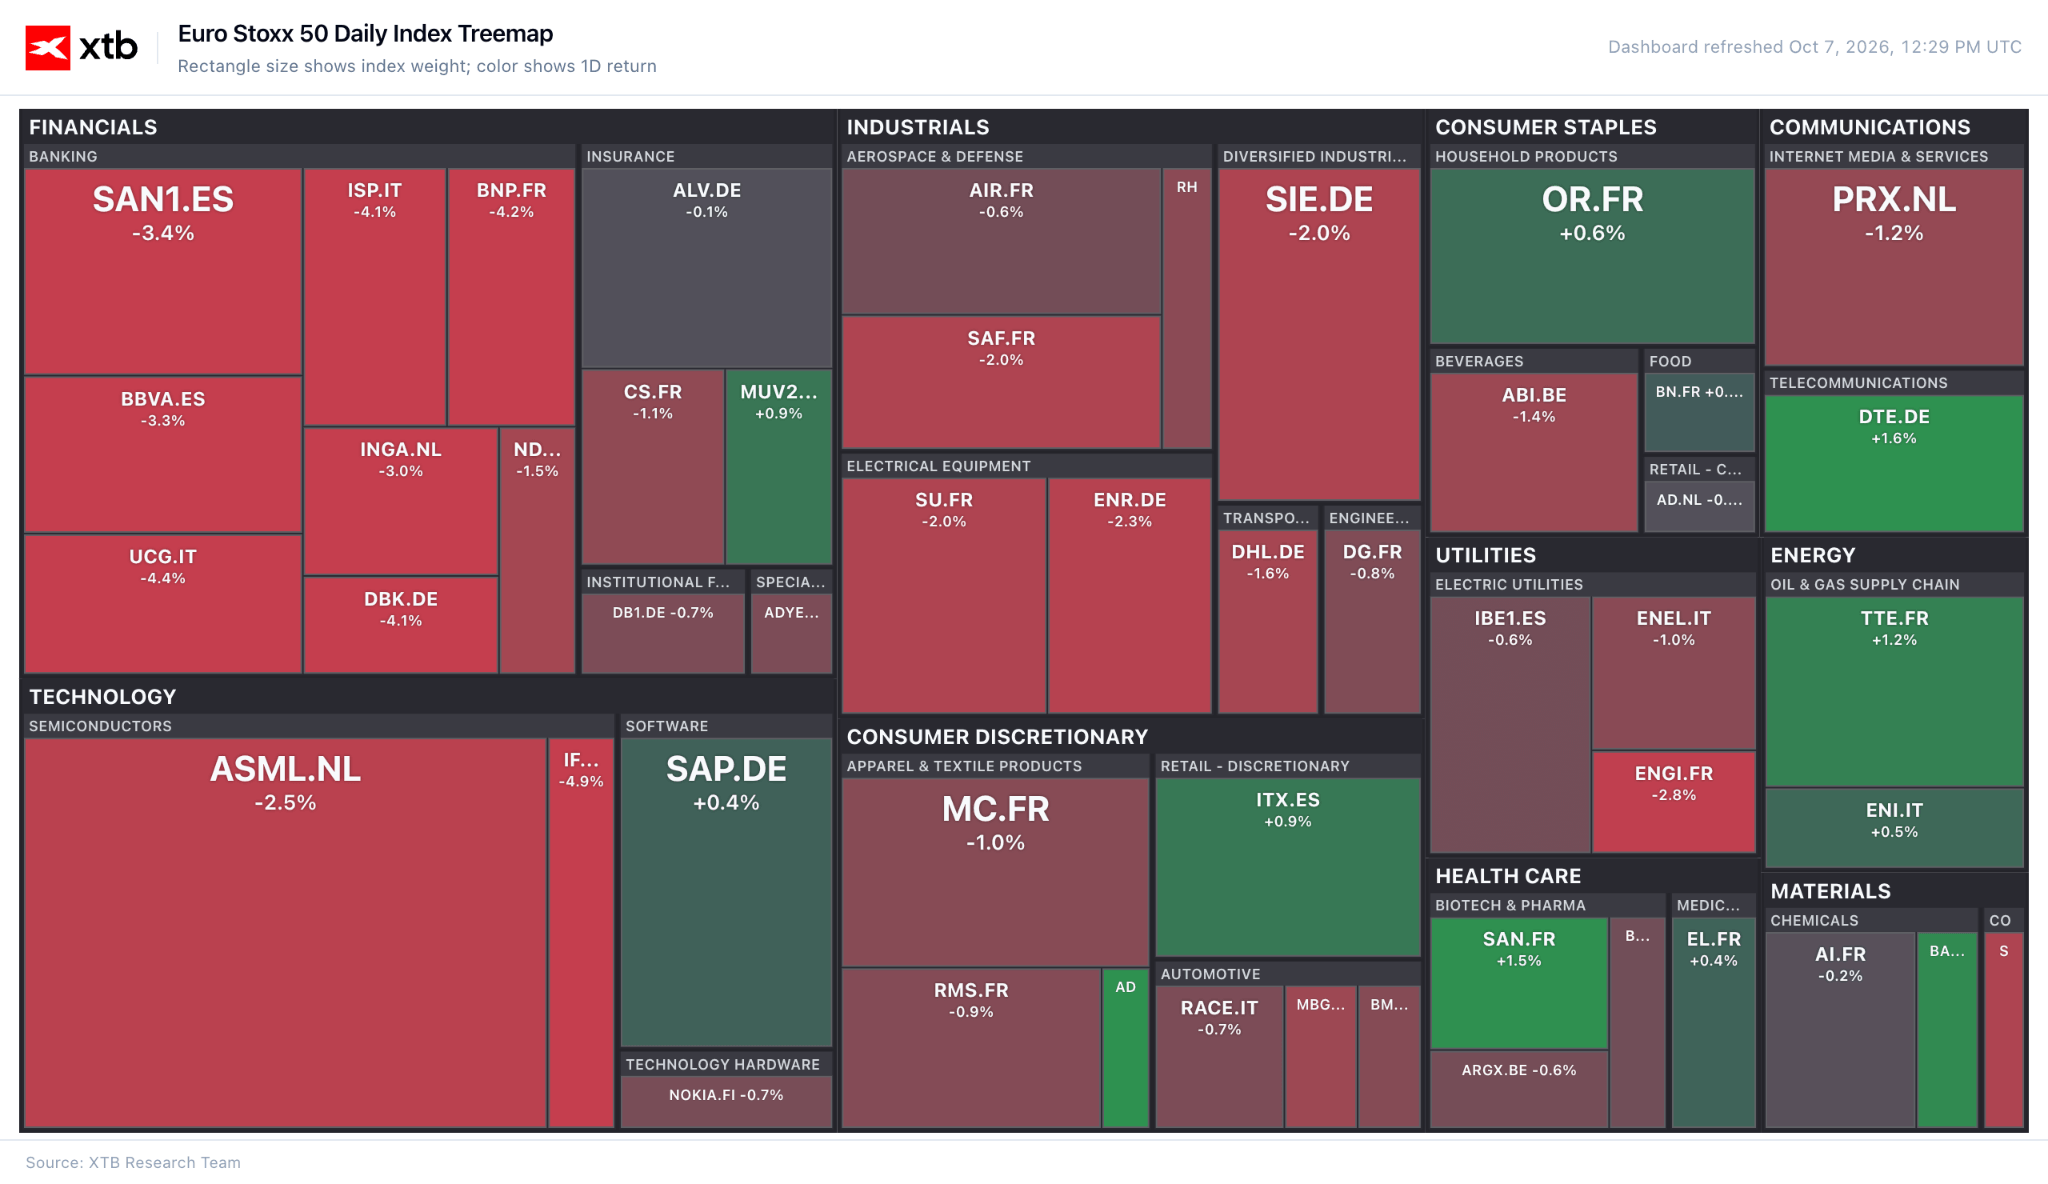
European equity markets are predominantly in the red today. The Italian FTSE MIB (-2.5%) and the pan-European Euro Stoxx 50 (-1.7%) are registering the steepest declines. The German DAX (-1.3%) and Spanish IBEX 35 (-1.8%) are also trading lower.
Figure 3: Euro Stoxx 50 Treemap (07.10.2026)
 Source: XTB Research, 07.10.2026
Within the Euro Stoxx 50, semiconductor stocks, premium German automakers, and banks are the weakest performers today, being the most sensitive to rising yields and pressure for a less hawkish ECB stance.
Infineon is down nearly 5%, mirroring broader weakness across the technology sector. Investors are taking a cautious approach ahead of earnings from Asian semiconductor giants (Samsung, SK Hynix), while UBS downgraded its recommendation on BE Semiconductor to "sell" (sending the stock down around 8%).
Mercedes-Benz (-1.5%) and BMW (-1%) are also notably lower, having posted modest early gains following reports that the EU is considering limiting imports of Chinese hybrid vehicles. The reversal suggests the market has begun weighing the risk of retaliation from Beijing, given that China remains a critical market for both manufacturers (Mercedes sales in China fell 31% year-on-year in Q3).
Precious metals and cryptocurrencies
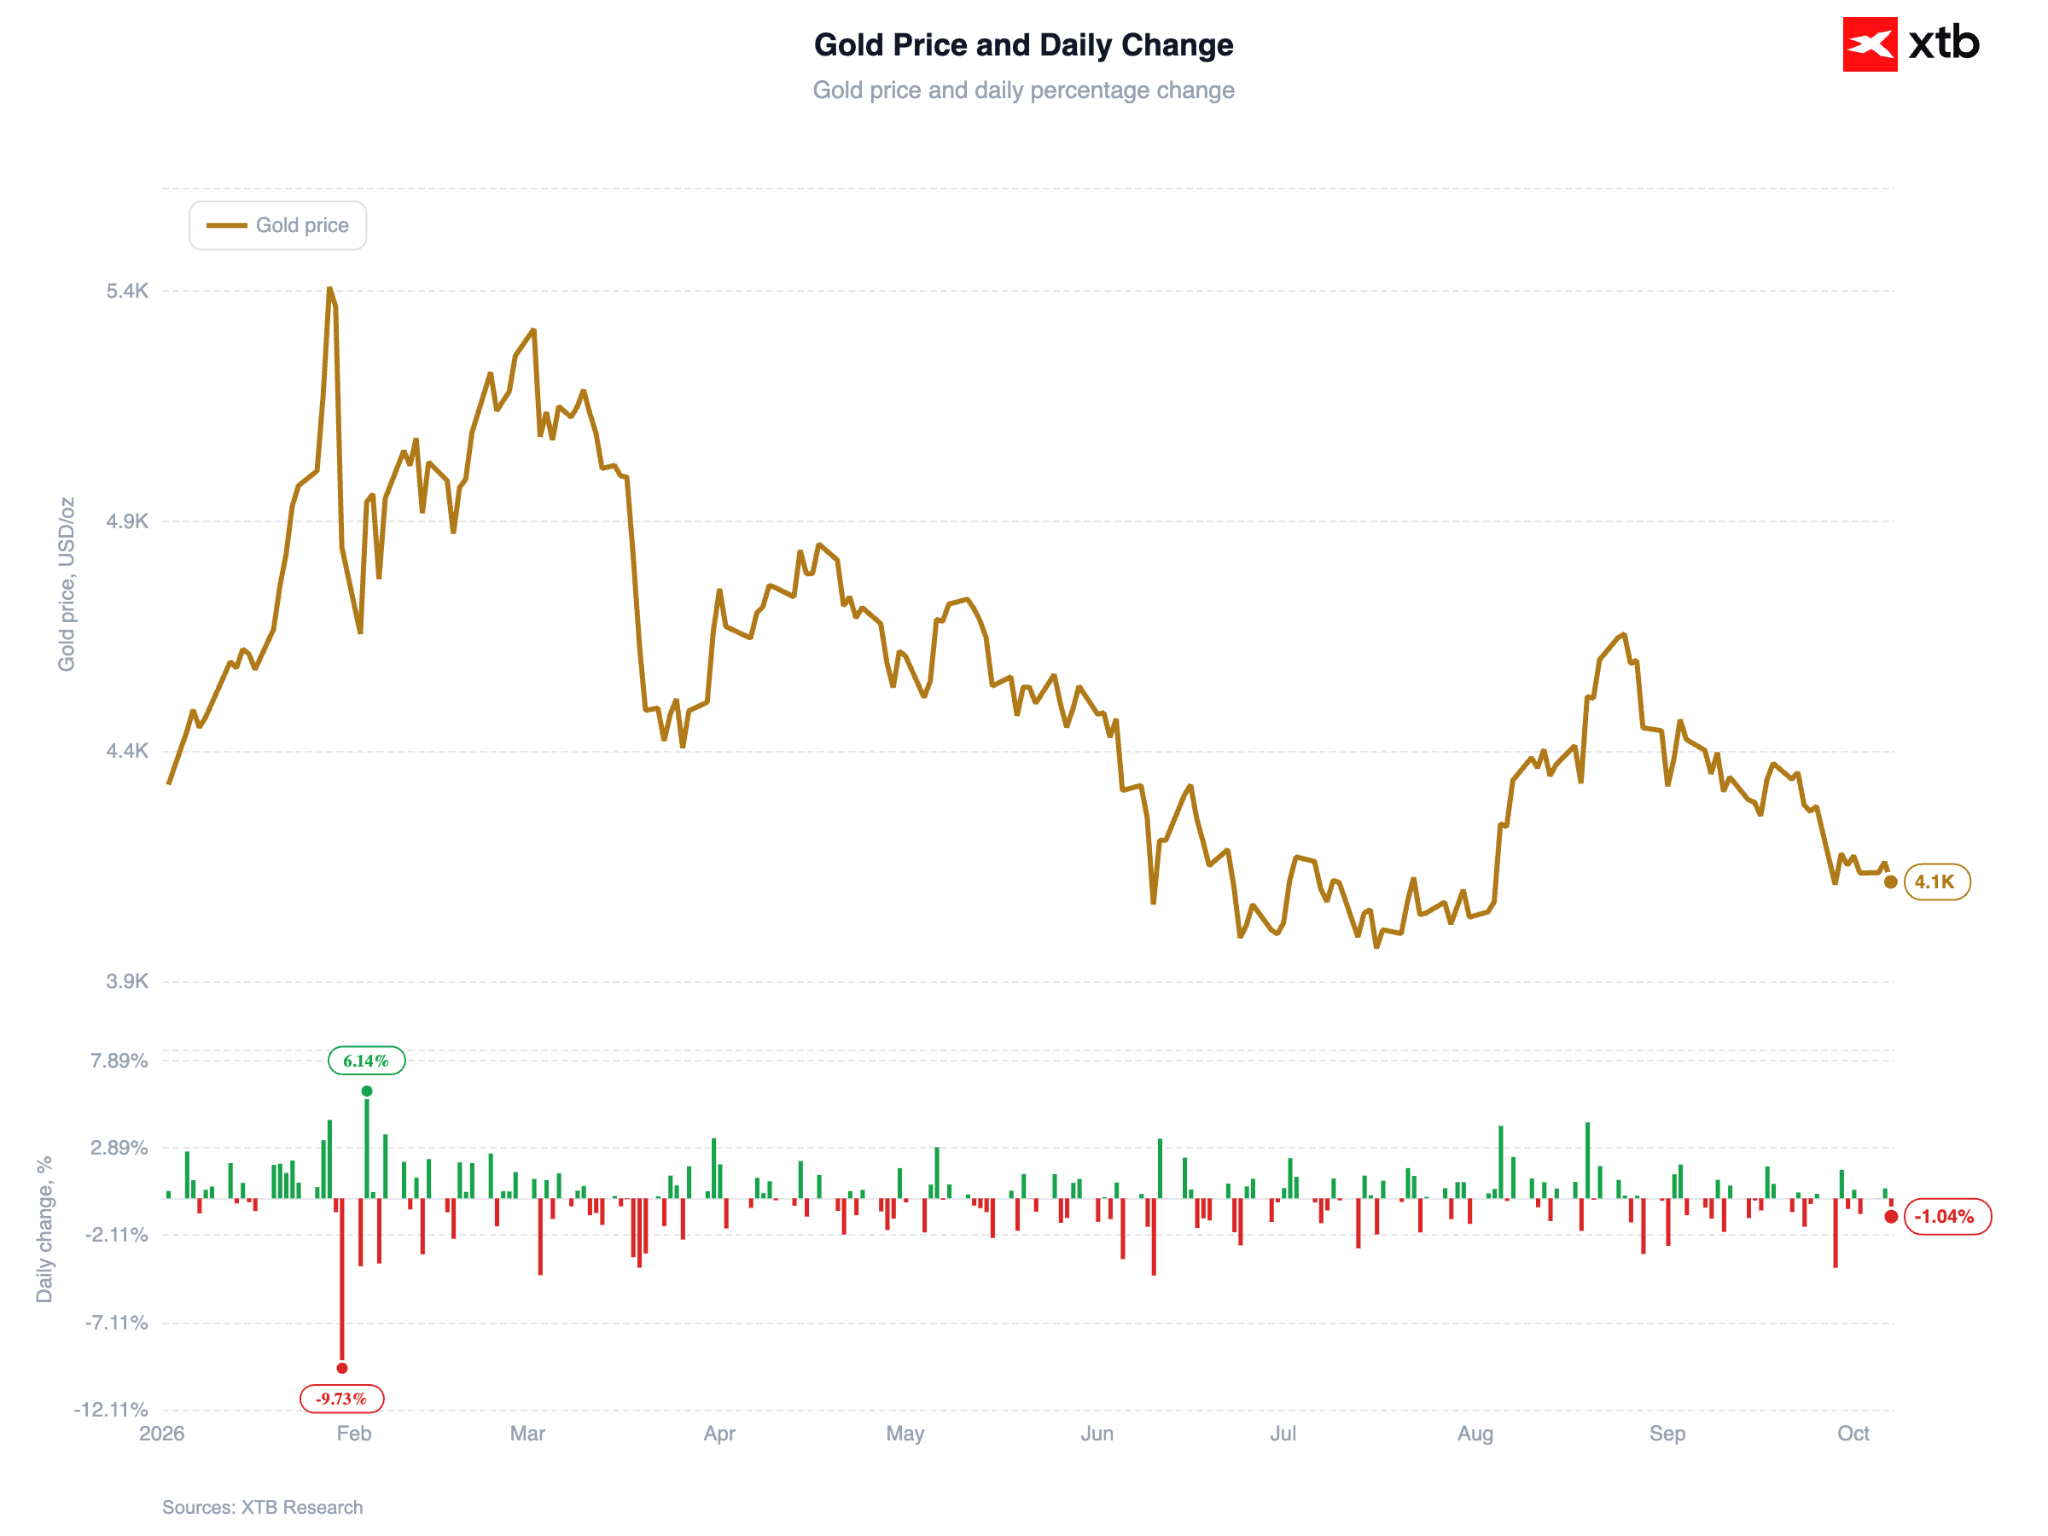
A firmer US dollar and rising yields are weighing on gold, which is down over 1% today, slipping below $4,120 per ounce. Silver is also posting losses of over 2%, while Bitcoin is trading down around 2%.
Figure 4: Gold (2026)
 Source: XTB Research, 07.10.2026
—
Michał Jóźwiak, Financial Markets Analyst at XTB



Oil falls below $100🚨


💶Chart of the Day: EURUSD at Lowest Since May 2025 Amid French Fiscal Crisis
Morning Briefing: Dollar gains, oil falls. EURUSD at multi-month lows


Morning Wrap: Tech Rally in Asia Following Micron Results and Weakening Yen Despite Hawkish BoJ
This content has been created by XTB S.A. This service is provided by XTB S.A., with its registered office in Warsaw, at Prosta 67, 00-838 Warsaw, Poland, entered in the register of entrepreneurs of the National Court Register (Krajowy Rejestr Sądowy) conducted by District Court for the Capital City of Warsaw, XII Commercial Division of the National Court Register under KRS number 0000217580, REGON number 015803782 and Tax Identification Number (NIP) 527-24-43-955, with the fully paid up share capital in the amount of PLN 5.869.181,75. XTB S.A. conducts brokerage activities on the basis of the license granted by Polish Securities and Exchange Commission on 8th November 2005 No. DDM-M-4021-57-1/2005 and is supervised by Polish Supervision Authority.