

- US inflation data release drives market direction and asset prices today.
- UK bond yields fall as central bank commentary sounds less aggressive.
- ASML shares rise after strong earnings and positive long term orders.

- US inflation data release drives market direction and asset prices today.
- UK bond yields fall as central bank commentary sounds less aggressive.
- ASML shares rise after strong earnings and positive long term orders.
The countdown is on for US inflation, which is scheduled for release later today. In the lead up, stock indices in Europe are rallying, the oil price is rising moderately, and Brent is trading above $106 a barrel.
UK Gilts outperform
The bond market is less skittish than it has been in recent weeks. UK yields are falling today and are outperforming their European and US peers. The 10-year yield is down by more than 5bps so far, on track for its best daily performance in 3 weeks.
Central bank speakers sound less hawkish
There have been a plethora of central bank speakers this morning at the IMF conference in Bangkok. Although some of the commentary from Andrew Bailey and Huw Pill, the chief economist at the BOE, has sounded hawkish in the near-term, bond traders are pouncing on Pill’s comments. Pill was skeptical that four rate hikes are needed for the UK in the next year, which is leading to a recalibration in UK interest rate swaps pricing.
In general, comments from the world’s most senior central bankers have been moderately dovish this week. Huw Pill and the ECB’s Christine Lagarde have both said that second round effects from the energy price spike are not a problem at this stage. This reduces the need for central banks to hike rates as aggressively as the market currently expects.
Can US inflation continue to calm the bond market?
It is worth noting that bonds have experienced large intraday swings in recent months and the longevity of today’s early recovery in UK Gilts may depend on the outcome of US inflation. The market is expecting a 0.6% monthly increase in headline US CPI, and a rise to 3.6% for the annual rate. This is due to energy price rises, which are expected to drive the bulk of price gains in US CPI.
The core CPI index is expected to inch up a notch to 2.5% from 2.4%, and rise 0.2% on a monthly basis. Headline inflation is expected to rise sharply, and this is priced in by the market, in our view. It will take a much larger upside surprise, say a 1% increase on the month to spook investors. In the absence of a large upside surprise, we think that stocks can continue to rally.
A 2-speed chip trade
Global stock volatility is tame so far on Wednesday. European indices are rising, and US futures are mixed. After a tricky start to the week, the Nasdaq is mostly flat as we lead up to the CPI data later today. Chip stocks have been in the firing line in recent days, but the sell off is slowing down.
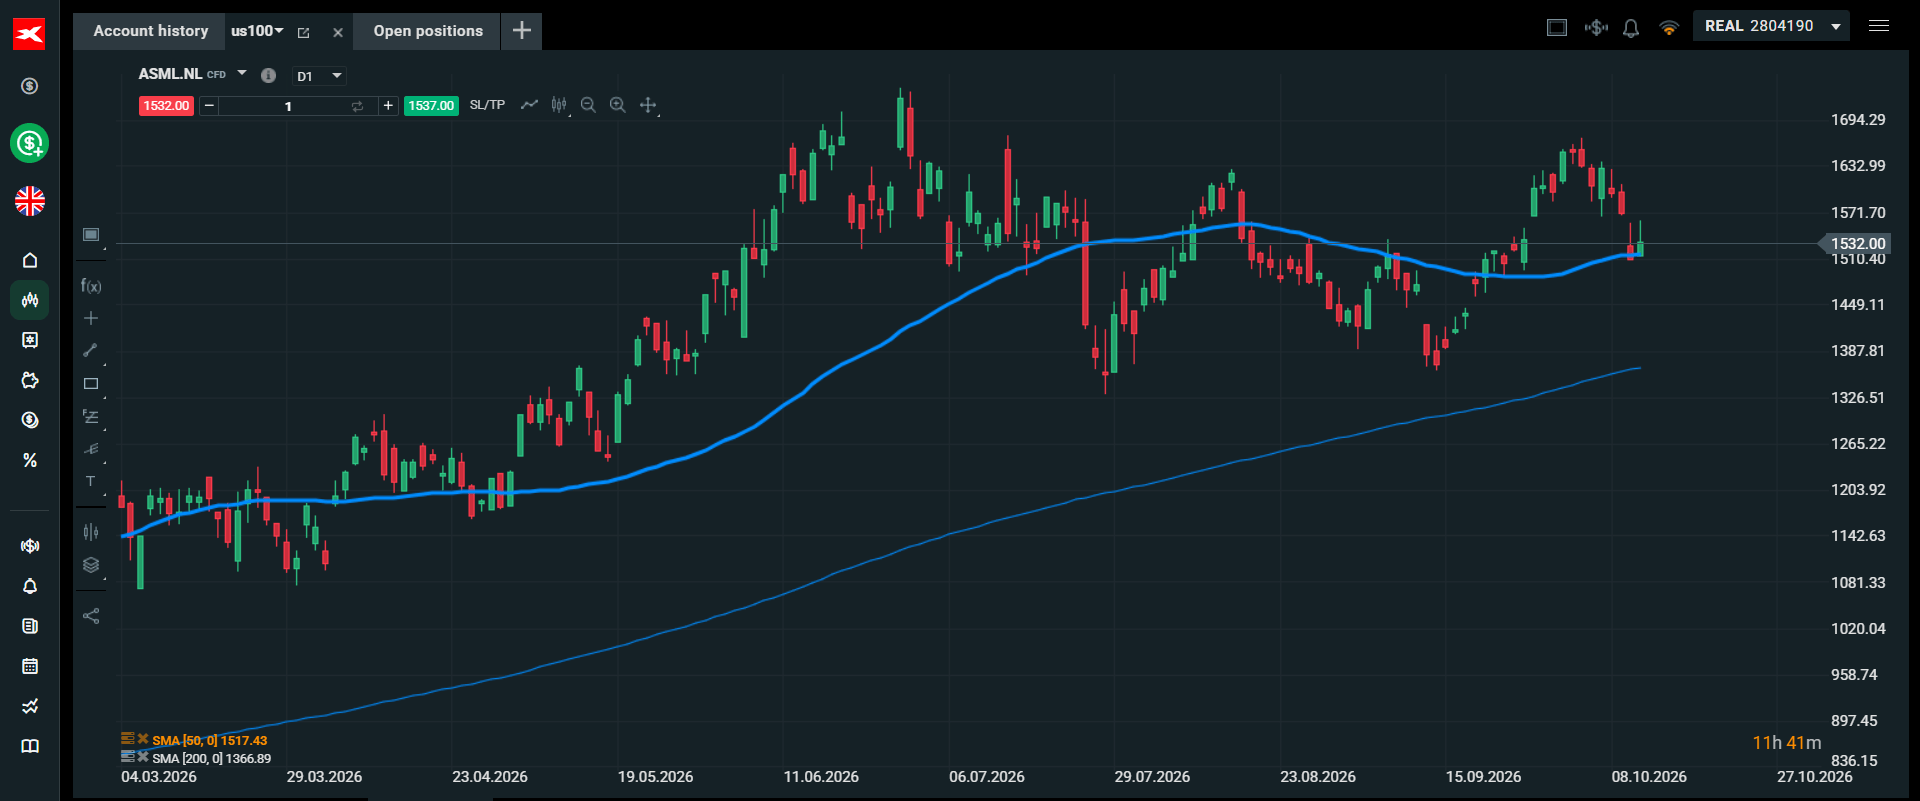
The Korean Kospi index has fallen by 12% in the past week, but only dropped by 0.4% on Wednesday. However, in the pre-market, US memory chip makers, such as SanDisk and Micron are still getting sold off. However, the sell off is not uniform. In Europe, ASML is rising today after posting strong earnings that smashed expectations and delivering an upbeat forecast, saying that order interest is now stretching out to 2030. Its share price is higher by nearly 2% so far this morning, and the stock has found good support at EUR 1517, the 50-day sma.
Nvidia is pointing to a higher opening, with the bulk of selling in US memory chip makers. This suggests that the threat of Chinese competition is the main driver for this sell off.
UK Budget fails to spook FX traders
The UK Budget is also in focus, after the IMF told the UK not to increase borrowing to fund defence spending. Treasury officials have said that capital gains taxes won’t be equalised to interest rates, so where will the money come from? As we get closer to Budget day, it seems less likely that Healey will lean on more tax hikes in 2 weeks’ time, and there seems to be growing consensus, even within the Labour Party, that spending needs to be restrained. Interestingly, GBP is mostly unchanged vs. the USD in the lead up to this budget, and FX option pricing does not suggest that the market is expecting excessive volatility in the UK currency during the budget.
Overall, the tone of price action for the rest of the day will be driven by the US CPI report. If the data suggests that second-round inflation effects are not yet creeping into the US economy, bond yields may fall further, stocks may rise and precious metals could also bounce back.
Chart 1: ASML, the chip trade has winners and losers this week
Source: XTB


Dollar in Limbo Ahead of CPI 🚨


Economic Calendar: US CPI Inflation Data in Focus (14.10.2026)
Chart of the Day 📈 EURUSD attempts to rebound ahead of US inflation data (14.10.2026)


ASML disappoints on revenue but delivers stronger profits and raises guidance 🍳 What’s next for the AI sector?
This content has been created by XTB S.A. This service is provided by XTB S.A., with its registered office in Warsaw, at Prosta 67, 00-838 Warsaw, Poland, entered in the register of entrepreneurs of the National Court Register (Krajowy Rejestr Sądowy) conducted by District Court for the Capital City of Warsaw, XII Commercial Division of the National Court Register under KRS number 0000217580, REGON number 015803782 and Tax Identification Number (NIP) 527-24-43-955, with the fully paid up share capital in the amount of PLN 5.869.181,75. XTB S.A. conducts brokerage activities on the basis of the license granted by Polish Securities and Exchange Commission on 8th November 2005 No. DDM-M-4021-57-1/2005 and is supervised by Polish Supervision Authority.