


Wall Street enters US midterm election day with a degree of optimism. S&P 500 is up by approximately 0.5%, while Nasdaq 100 gains around 0.9%, recovering a modest portion of yesterday's losses.
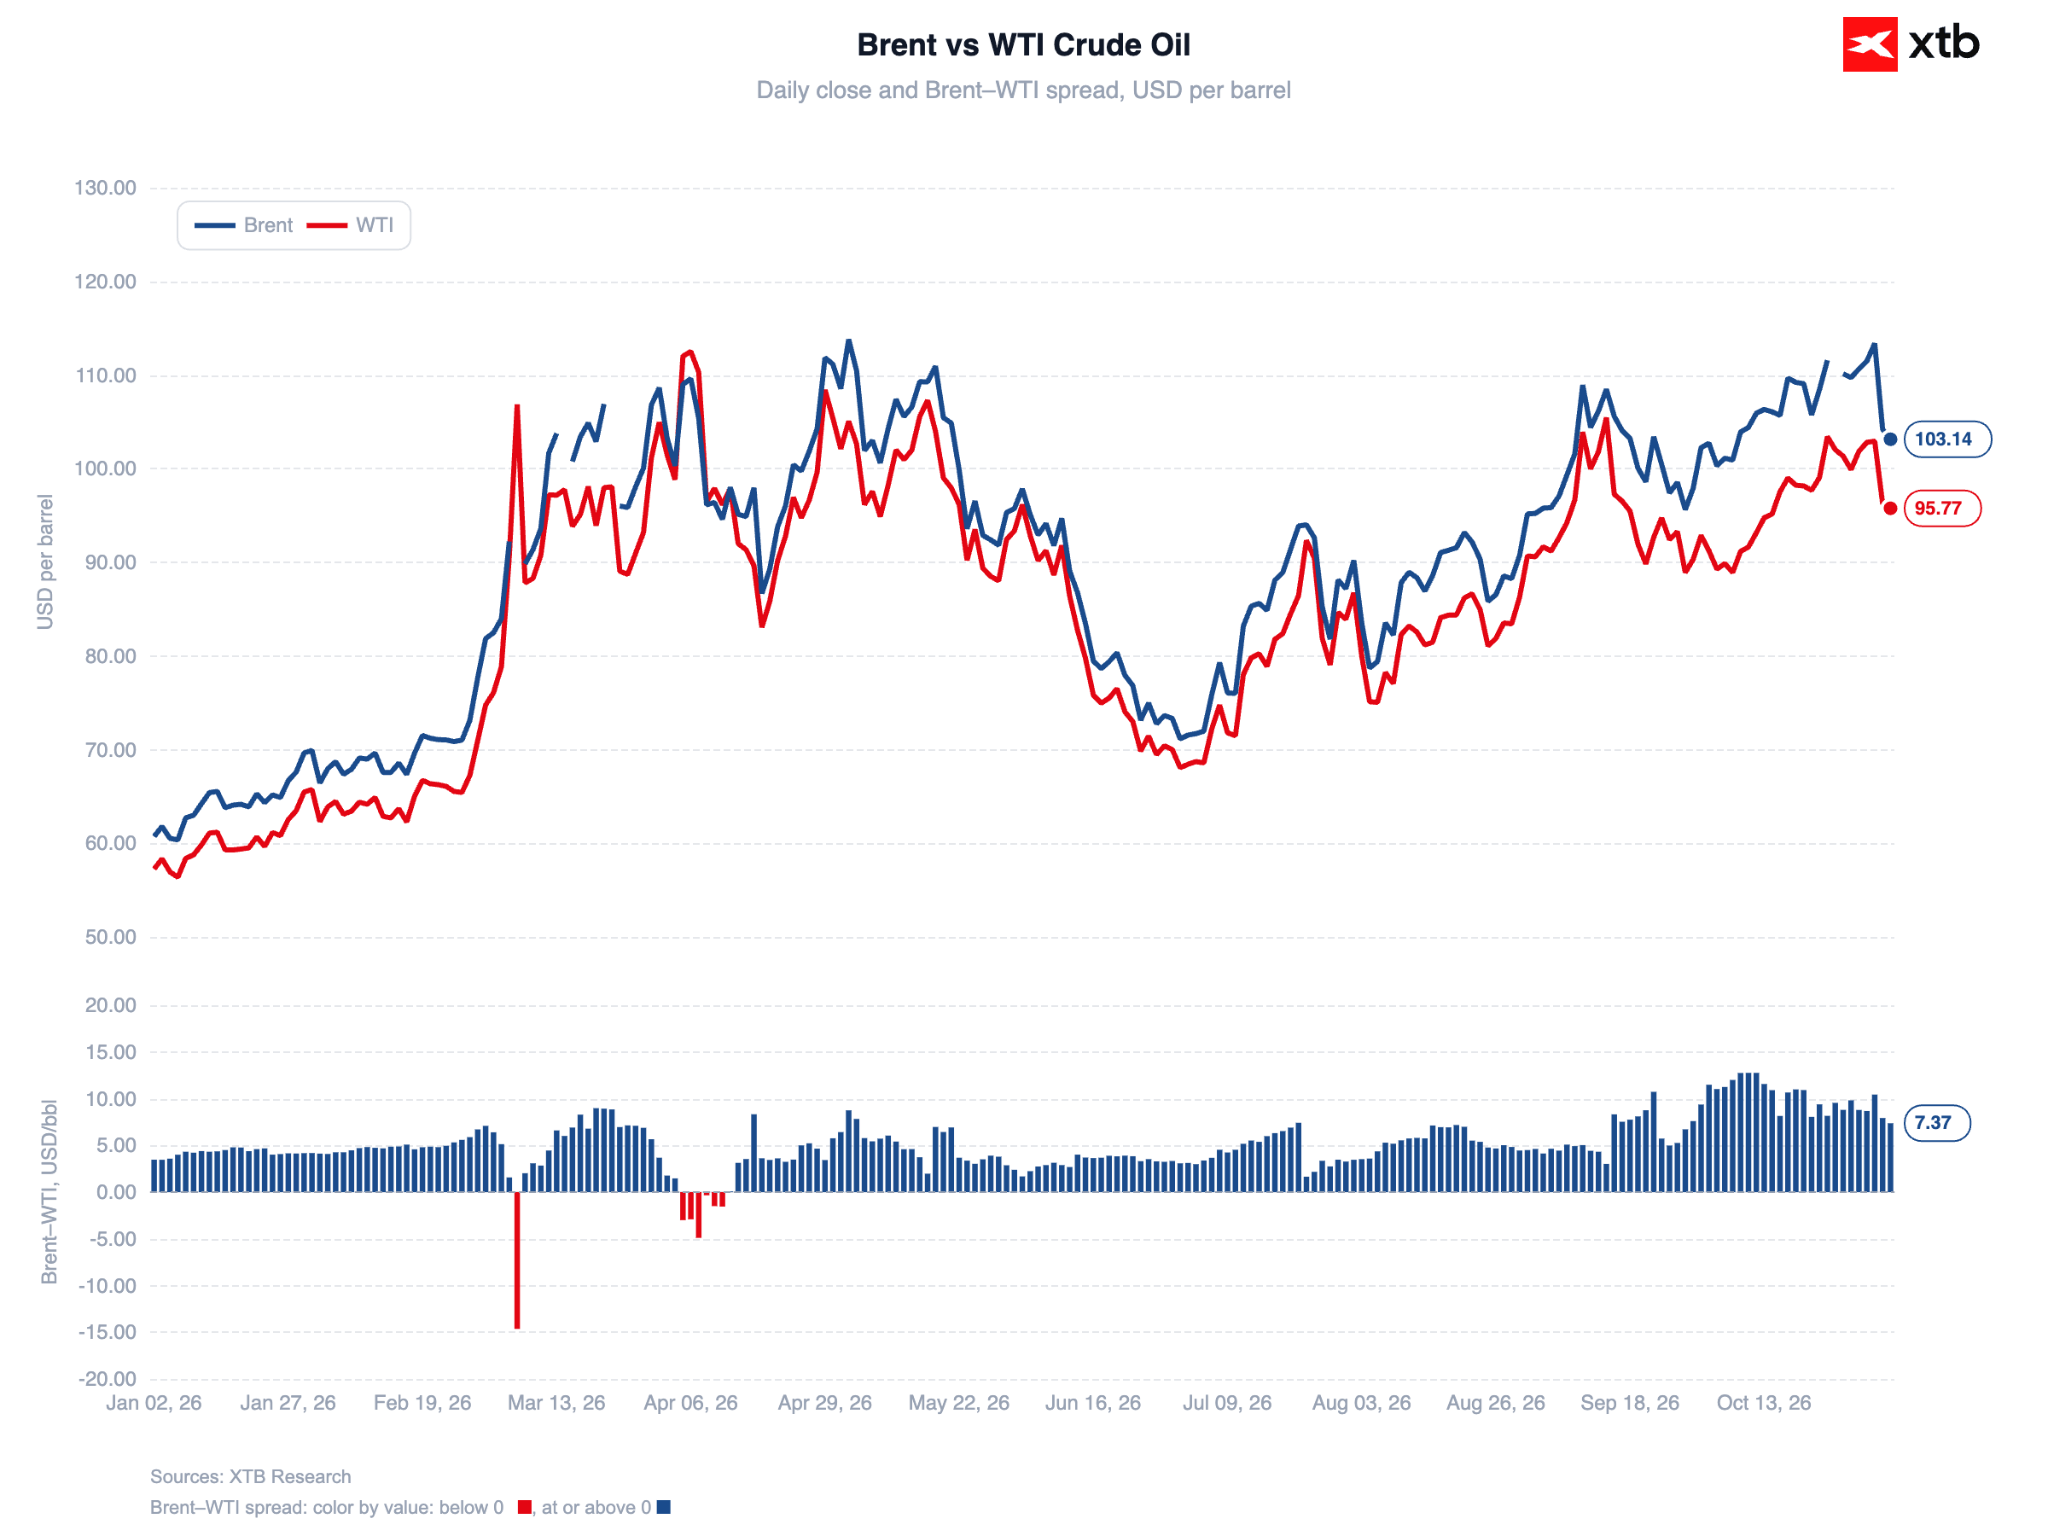
The primary catalyst for the improved market sentiment is softer crude oil prices. Brent crude, which traded near $107 per barrel during morning hours, pulled back towards $102 per barrel during the session. The decline was prompted by reports regarding a draft memorandum presented by Qatari mediators, sparking speculation of de-escalation.
Figure 1: Brent and WTI Crude Oil (2026)
 Source: XTB Research, 03.11.2026
Markets grow increasingly confident in Democrats victory
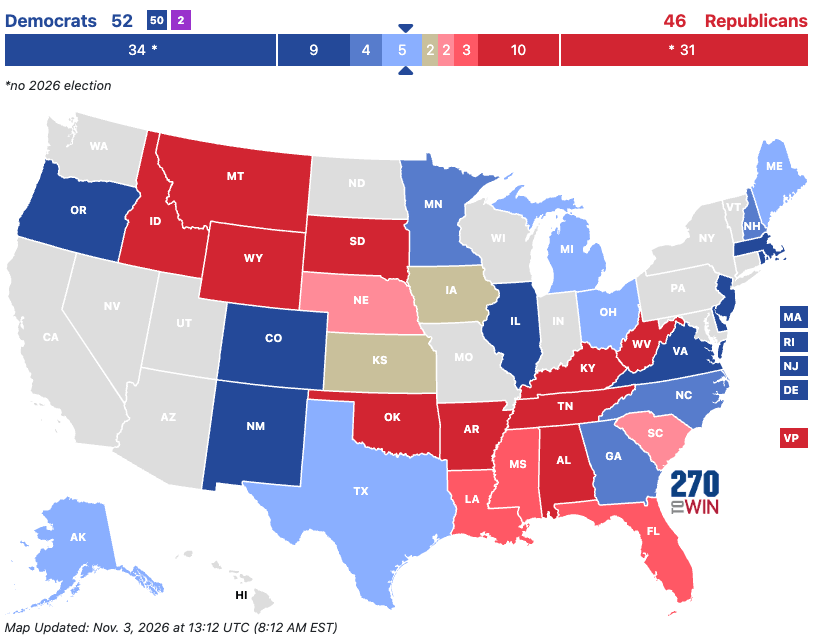
According to prediction market odds, the probability of the Democrats taking control of the House of Representatives stands at approximately 95%, while the chance of securing the Senate is around 75%. The loss of both houses of Congress by the Republicans represents the least favourable scenario for the broader equity market (and particularly for companies tied to the AI revolution).
Figure 2: Projected Senate Seat Distribution (270-to-win)
 Source: 270-to-win, 03.11.2026
It is worth noting, however, that across the last 19 election cycles, there has not been a single instance in which the S&P 500 index was in negative territory 120 trading days following the elections. The average return over this period stood at 13%.
Memorandum hopes pressure crude oil
US strikes on the Iranian island of Qeshm in the Strait of Hormuz and incidents involving the Iranian Islamic Revolutionary Guard Corps temporarily dampened sentiment in early trading. However, Qatar simultaneously delivered a draft memorandum to Iran, and the Iranian President signalled greater scope for government negotiations.
Oil prices appear poised to react sharply to any news emanating from Doha or Tehran. Trump suggested today that the US would not resume military action following the elections, though the market remains cautious towards this statement - recalling that the previous memorandum in June collapsed after roughly two weeks.
Tech stocks rebound following a 10% correction
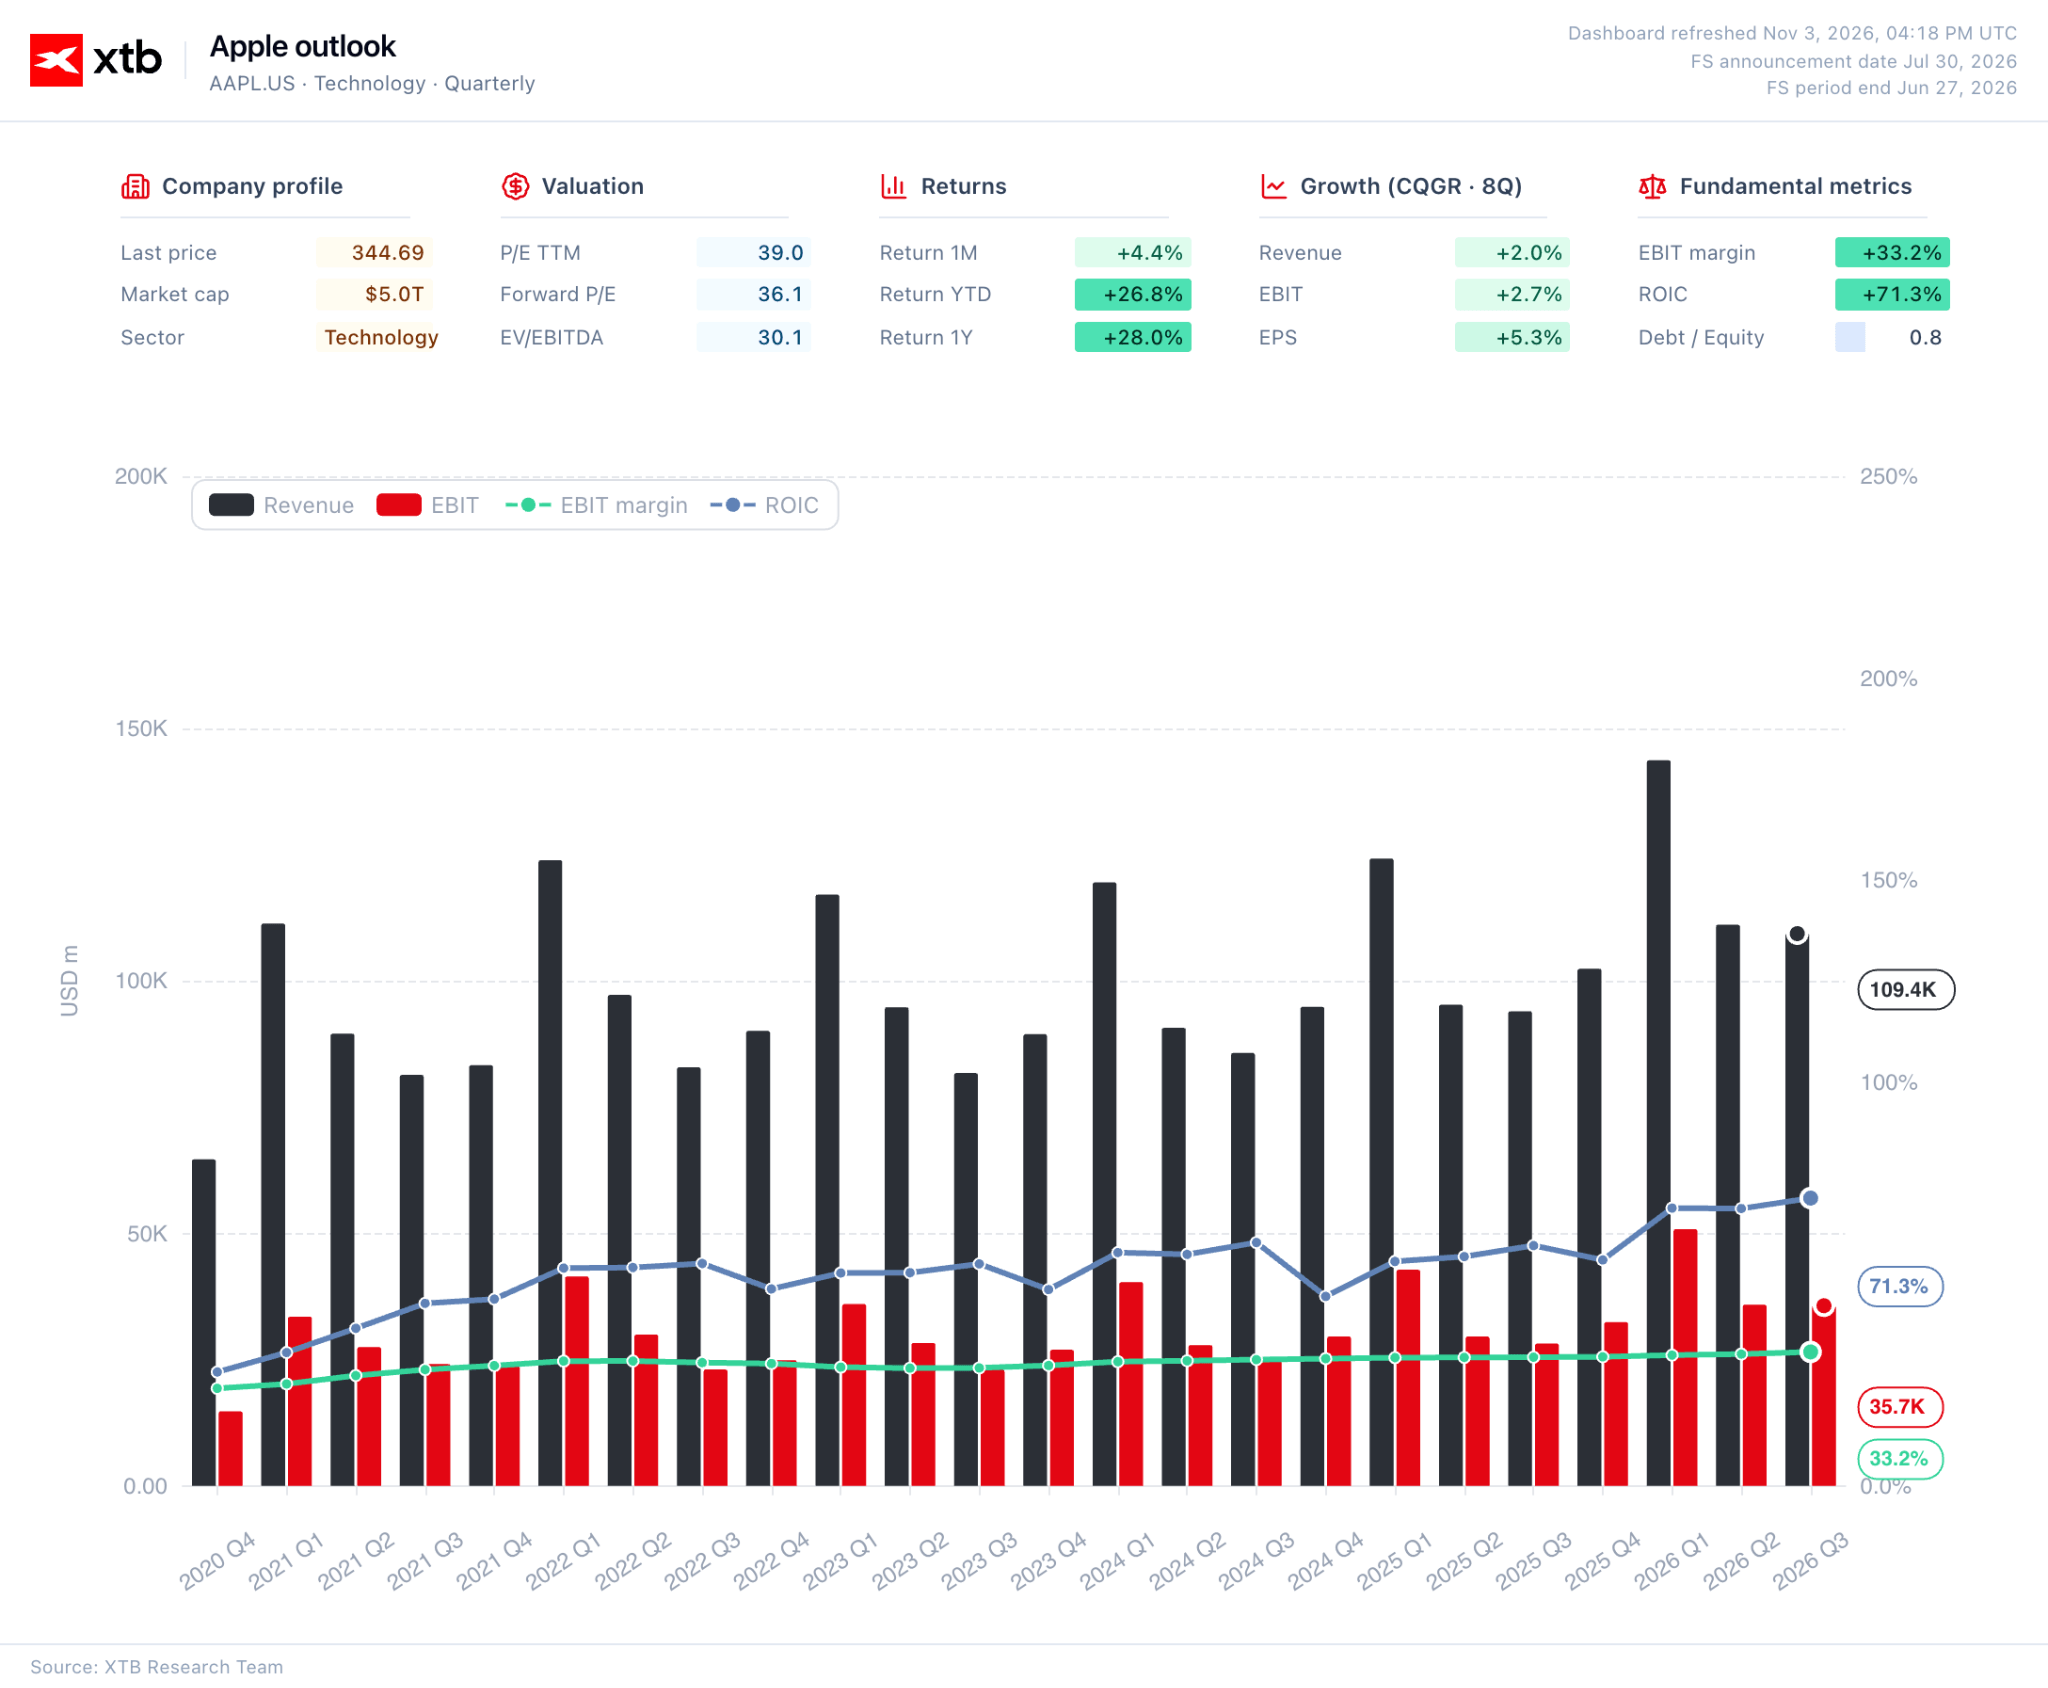
The popular SOXX semiconductor index declined by approximately 10% over the preceding three days. Today, we are witnessing a fairly dynamic rebound (+3.4%). The Nasdaq 100 is also performing reasonably well (+1%), despite being significantly weighed down by Apple (-2.9%), which disappointed somewhat with its third-quarter financial results (particularly regarding revenue from China).
Figure 3: Dashboard for Apple (2020 - 2026)
 Source: XTB Research, 03.11.2026
Palantir (-1.3%) is also trading lower after pointing to a potential slowdown in sales growth within its quarterly report.
Macroeconomic data
Ahead of the US session, preliminary October ISM PMI figures were released. The manufacturing index came in at 55.5, while the services index reached 54.9. Neither reading presented a major surprise, remaining consistent with the GDP growth pace indicated by the GDPNow model (approximately 3.7% annualized for Q4).
In other macroeconomic news, US job openings (JOLTS) rose to 7.52 million in September, above expectations of 7.10 million. The August figure was revised upwards from 7.08 million to 7.19 million. Total hires stood at 5.40 million, the quits rate at 2.1%, and layoffs at 1.0%. The data came in stronger than consensus forecasts.
Key corporate news
- Apple (AAPL.US): -2.9%, modest disappointment across key metrics in its Q3 report, particularly regarding revenue from China. Pressure on margins and a slowdown in the services segment.
- Palantir (PLTR.US): -1.3%, quarterly guidance suggests a potential deceleration in sales growth.
- Shopify (SHOP.US): -8.4%, third-quarter subscription revenue missed expectations for the first time in four years.
- Walt Disney (DIS.US): -0.2%, reports of thousands of impending redundancies as managers seek 20% cost savings.


Chart of the Day: Brent crude falls despite Trump's words about no desire to negotiate

Economic Calendar - Global series of industrial PMI indicators and tech giants' results


📊Morning Wrap: Oil falls after Qatar talks. China injects liquidity, while the US prepares for elections.


💥Daily Summary: Tech Sector Crash on Wall Street and Historic Attack on Binance
This content has been created by XTB S.A. This service is provided by XTB S.A., with its registered office in Warsaw, at Prosta 67, 00-838 Warsaw, Poland, entered in the register of entrepreneurs of the National Court Register (Krajowy Rejestr Sądowy) conducted by District Court for the Capital City of Warsaw, XII Commercial Division of the National Court Register under KRS number 0000217580, REGON number 015803782 and Tax Identification Number (NIP) 527-24-43-955, with the fully paid up share capital in the amount of PLN 5.869.181,75. XTB S.A. conducts brokerage activities on the basis of the license granted by Polish Securities and Exchange Commission on 8th November 2005 No. DDM-M-4021-57-1/2005 and is supervised by Polish Supervision Authority.