


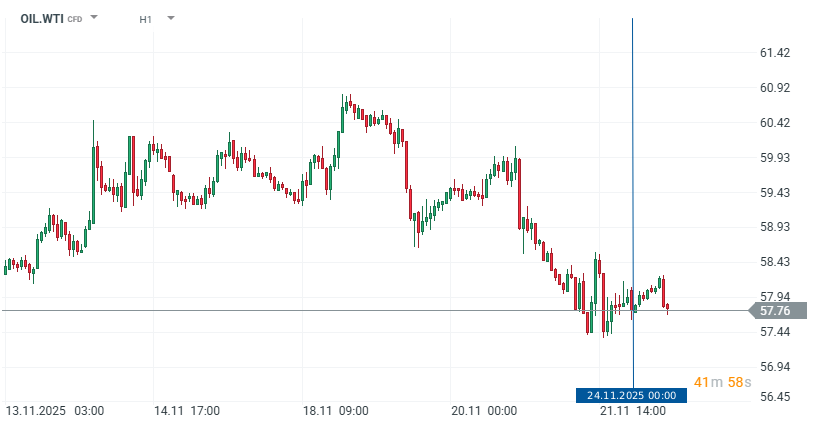
Oil prices started the week with a slight selloff, adding to last week’s 3% decline. The oil market is now focused on the potential Russia–Ukraine peace agreement. At the moment, WTI crude is down 0.25% at 57.80 USD per barrel.
Trump is pushing for the adoption of a modified version of the peace proposal, which was the main catalyst behind Friday’s selloff in oil. The market increasingly views a possible agreement as a path toward easing or lifting sanctions, which could unlock Russian oil and increase global supply. Despite the short-term tightening resulting from U.S. sanctions — which currently leave nearly 48 million barrels of Russian crude stranded at sea — the broader narrative remains that an agreement could quickly bring these volumes back.
The prospect of Russian barrels returning comes against a fragile macro backdrop. Uncertainty around U.S. monetary policy continues to weigh on risk appetite, although comments from New York Fed President John Williams have reignited expectations for a December rate cut. The market now prices the odds of a cut at 71%.
The key date for the market will be this Thursday, the final deadline in the peace negotiations. By that time, President Trump expects both sides to reach an agreement. A significant breakthrough could increase supply-side pressure.


3 markets to watch next week: GBPUSD, US500, OIL (06.11.2026)

OIL loses after reaching $100 📉Is Iran reviewing a change to its nuclear program?

🚩 EURUSD loses 0.6%


US Open: Nasdaq rebounds after the largest decline since 19-month 🔼 Lam Research surges 12%