


Today’s macroeconomic calendar is particularly important for European currencies and bonds, as markets await decisions from several central banks as well as fresh data from the world’s largest economies. At 9:30 a.m., the SNB and Riksbank will announce their interest-rate decisions, with markets expecting rates to remain unchanged at 0.00% and 1.75%, respectively. Shortly afterward, at 10:00 a.m., investors’ attention will turn to Germany, where the Ifo indices for expectations, current conditions and overall business climate will be released. The consensus points to a slight improvement in sentiment, which could provide an important test of the German economy’s resilience after a period of high energy costs and tighter financial conditions across the eurozone.
In the second half of the day, the focus will shift to U.S. data, especially weekly jobless claims and new home sales. The market expects initial claims to rise slightly to 200k, while new home sales are forecast to increase by 1.3% m/m after the previous 10.5% decline. An additional, and potentially more important, source of volatility than the macro data themselves could come from speeches by Fed officials, particularly against the backdrop of rising bond yields and increasingly hawkish expectations for the future path of interest rates.
Economic calendar
- 04:00 AM GMT, China/USA – Xi Jinping begins his state visit to the U.S.; all-day event, no consensus.
- 06:45 AM GMT, France – Overall Business Climate: expected 98 pts; previous 98 pts.
- 06:45 AM GMT, France – Manufacturing Business Climate: expected 102 pts; previous 103 pts.
- 06:45 AM GMT, France – Consumer Confidence: expected 85 pts; previous 88 pts.
- 07:30 AM GMT, Switzerland – SNB interest-rate decision: expected 0.00%; previous 0.00%.
- 07:30 AM GMT, Sweden – Riksbank interest-rate decision: expected 1.75%; previous 1.75%.
- 08 AM GMT, Germany – Ifo Expectations: expected 89.3 pts; previous 89.1 pts.
- Current Conditions: expected 89.0 pts; previous 88.5 pts.
- Business Climate: expected 89.0 pts; previous 88.8 pts.
- 08 AM GMT, Switzerland – SNB press conference.
- 08 AM GMT, Norway – Norges Bank interest-rate decision: expected 4.50%; previous 4.25%.
- 10 AM GMT, United Kingdom – CBI Distributive Trades: no consensus; previous -48 pts.
- 12:30 PM GMT, Canada – Retail Sales m/m: expected -0.8%; previous +0.6%.
- 12:30 PM GMT, Canada – Core Retail Sales m/m: expected -0.5%; previous +0.5%.
- 12:30 PM GMT, USA – Initial Jobless Claims: expected 200k; previous 198k.
- 12:30 PM GMT, USA – Current Account Balance: expected -$257.4bn; previous -$226.8bn.
- 12:30, PM GMT, USA – Continuing Jobless Claims: expected 1.74mn; previous 1.730mn.
- 2 PM GMT USA – New Home Sales: expected 0.6155mn; previous 0.607mn.
- 2 PM GMT, USA – New Home Sales m/m: expected +1.3%; previous -10.5%.
- 2:30 PM GMT, USA – EIA Natural Gas Storage Change: expected +51 bcf; previous +44 bcf.
- 3 PM GMT, USA – Kansas City Fed Manufacturing Index: no consensus; previous 17 pts.
- 3 PM GMT, USA – Kansas City Fed Composite Index: expected 8.5 pts; previous 10 pts.
Central bankers’ speeches
- 9:30 AM GMT, United Kingdom – BoE’s Dhingra speaks.
- 12:30 PM GMT, USA – Fed’s Barkin speaks.
- 12:50 PM GMT, USA – Fed’s Hammack speaks.
- 1:30 PM GMT, United Kingdom – BoE’s Breeden speaks.
- 2 PM GMT, United Kingdom – BoE’s Lombardelli speaks.
- 2:10 PM GMT, USA – Fed’s Paulson speaks.
EURUSD (D1 interval)
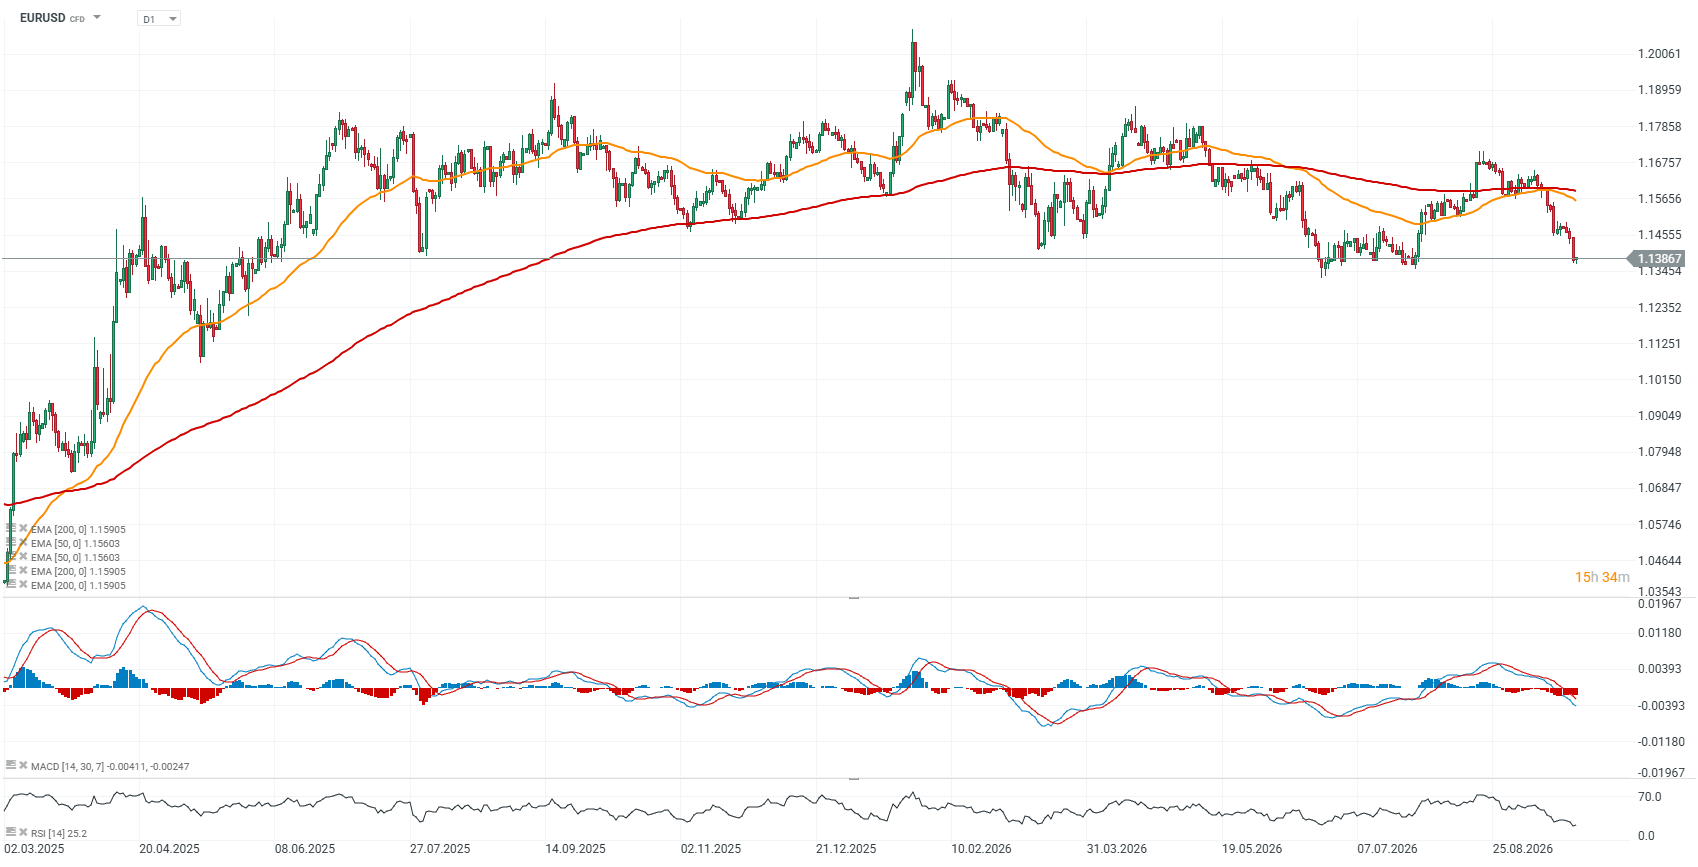 Source: xStation5



Daily Summary: US dollar reaches new highs, Wall Street, gold and bitcoin fall (23.09.2026)

US Open: Nasdaq drops from the all-time high (23.09.2026)
US PMIs skyrocket to a 5-year high
OECD lifts projections for global economy amid AI boom