


Optimism prevails in Europe this morning. The FTSE 100 is at a 3-month high (+1%), the CAC 40 is up 0.87%, the IBEX is up 0.86%, the Euro Stoxx 50 is up 0.3%, and the STOXX 600 is up 0.43%. The DAX is flat at the opening of the trading session in Europe.
Daily Schedule (CET)
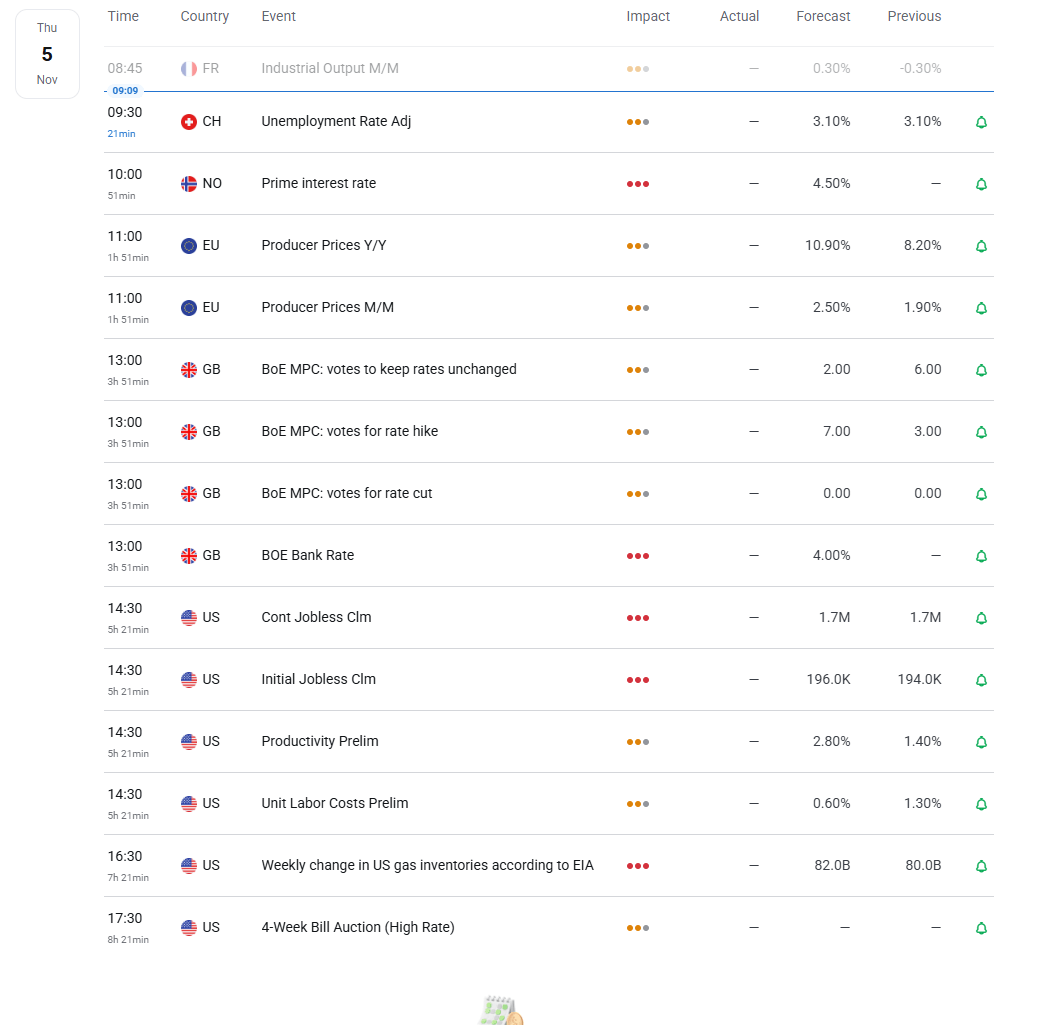
- 09:30 CH: Unemployment rate at 3.1%, unchanged.
- 10:00 a.m.: interest rate, forecast 4.50%.
- 11:00 EU: producer prices year-over-year (y/y), forecast at 10.9% compared with 8.2% previously, and month-over-month (m/m) at 2.5% compared with 1.9%. This is a clear sign that rising energy costs are being passed on to industry.
- 1:00 p.m. GB: BoE decision. The market expects the first rate hike of this cycle—a 25-basis-point increase to 4.00%. Voting forecasts show 7 votes in favor of a hike and 2 in favor of keeping rates unchanged, compared to 3 and 6 at the previous meeting. The tone of the press conference and the path of future rate hikes will be key.
- 2:30 p.m. US: Initial jobless claims 196,000 (previous: 194,000), continuing claims 1.7 million. Productivity in the third quarter (preliminary) 2.8% vs. 1.4%, unit labor costs 0.6% vs. 1.3%.
- 4:30 p.m. US: EIA natural gas inventories; forecast: 82 billion, compared with 80 billion previously.
- 5:30 p.m. US: auction of 4-week Treasury bills.
Company Results
Przed sesją raportują ConocoPhillips (COP.US) i Sony (SONY.US), a po sesji Monster Beverage (MNST.US).
Sony delivered a positive surprise. Operating profit in the second quarter rose 45% to 622.3 billion yen (approx. $3.95 billion), exceeding estimates, and the company raised its full-year forecast by 9%. The movie “Spider-Man: A New Beginning” and the gaming segment contributed to this performance. PS5 sales were a weak spot, totaling 2.6 million units compared to 4 million a year earlier. The company is also facing challenges with rising memory chip prices due to the AI boom. Shares gained about 7% ahead of the earnings release, so some of the optimism may already be priced in. The November 19 release of GTA VI remains a major catalyst.
Central Banks and the Big Picture
The minutes from the BoJ’s September meeting show that the board (voting 7–2 in favor of a rate hike to 1.25%) supports further tightening, and one member does not rule out accelerating the pace of tightening. The main inflation risk is the approximately 50% increase in oil prices since July. SNB President Martin Schlegel acknowledged that October’s inflation rate in Switzerland (1.5%) came as a surprise, which reinforces expectations of a rate hike in December.


What Drives the Market❓Top Morning News ⏰ (November 5, 2026)


🛢️Oil suffers sharpest fall since April (-9%)
BREAKING: US oil inventories fall less than expected, but prices drop due to elections and hopes for a US-Iran deal

BREAKING: ISM for services grows at the slowest pace in three months, cost pressure persists