


- On Monday, investors' attention is focused on data from the services sector, which remains a key driver of economic growth globally.
- Behind us is a quiet Asian session, where data on consumer confidence in Japan was published (35.4 pts vs. forecast 35.3 pts) along with price indicators from Australia and New Zealand.
- Pressure on the single European currency persists in the markets – EURUSD is declining toward 1.1170.
- In the background, geopolitical tensions resonate, including reports of Russian attacks on port infrastructure in the Odesa region and threats from Iran that led to the evacuation of American B-1 bombers from bases in the UK.
- Main high-volatility impulses will arrive in the afternoon with the publication of the US ISM Services index (4:00 PM), which will shed light on the pace of policy tightening or easing by the Federal Reserve.
- In China, it is a bank holiday, limiting overall liquidity in Asian markets.
Key Releases from the Asian Session
- Australia: Melbourne Institute Inflation Gauge for September rose by 0.3% MoM (previously: 0.5% MoM), signaling a slight deceleration in consumer price pressure.
- New Zealand: ANZ Commodity Price Index rebounded by 0.6% MoM compared to a -0.4% MoM decline in the previous month, supporting the local trade balance outlook.
- Japan: Consumer Confidence Index came in at 35.4 pts, beating market expectations (consensus: 35.3 pts), though slightly below the previous month's reading (35.5 pts).
Macroeconomic Calendar (CET)
- All day China - Bank Holiday
- 09:15 Spain - Services PMI. Consensus: 57.1. Previous: 57.8.
- 09:45 Germany - Speech by Bundesbank President Joachim Nagel
- 09:45 Italy - Services PMI. Consensus: 54.6. Previous: 55.2.
- 09:50 France - Final Services PMI. Consensus: 51.4. Previous: 51.4.
- 09:55 Germany - Final Services PMI. Consensus: 52.9. Previous: 52.9.
- 10:00 Eurozone - Final Services PMI. Consensus: 53.0. Previous: 53.0.
- 10:30 Eurozone - Sentix Investor Confidence Index. Consensus: 4.5. Previous: 5.1.
- 10:30 United Kingdom - Final Services PMI. Consensus: 51.7. Previous: 51.7.
- 11:00 Eurozone - Producer Price Index (PPI) MoM. Consensus: 1.9%. Previous: 1.6%.
- 15:45 USA - Final Services PMI. Consensus: 58.7. Previous: 58.7.
- 16:00 USA - ISM Services Index. Consensus: 55.1. Previous: 55.4.
- 23:00 New Zealand - NZIER Quarterly Survey of Business Opinion. Previous: 8.
Markets to Watch
- EURUSD — the currency pair is under clear supply pressure (declining below 1.1200), and the direction of further movement will be determined by the morning series of PMI readings from the Eurozone and ISM data from the US economy.
- Crude Oil (WTI/Brent) — the commodity market shows heightened sensitivity to escalating geopolitical tensions around Black Sea ports and rising military tensions in the Middle East.
- US and German Government Bonds (Bunds/Treasuries) — debt markets will react to the speech by the Bundesbank president and afternoon US service sector activity data in the context of the interest rate trajectory.
Technical Analysis: Brent
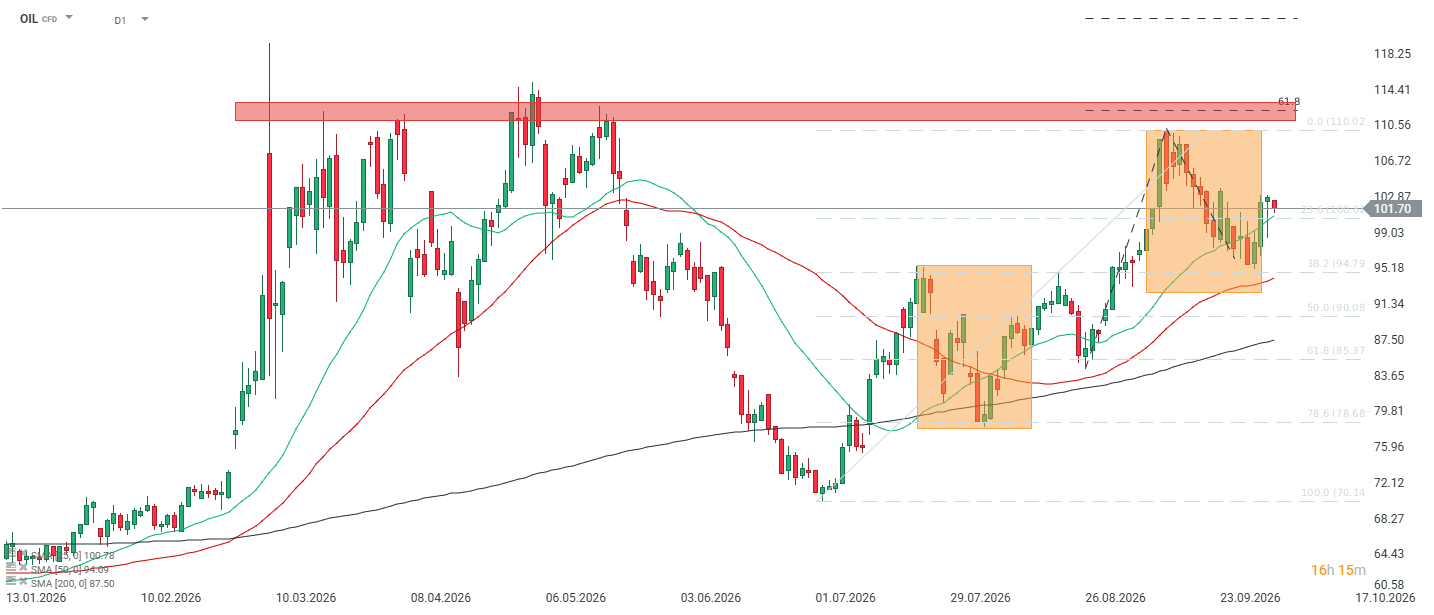
Brent crude is currently trading around $101.70, in a clear correction after an unsuccessful attempt to break strong resistance in the 110–114 zone, where the market bounced twice, first in May, then in September. Despite this sell-off, the broader trend remains bullish: the price is still holding above the 50- and 200-session moving averages, which technically maintains the bullish structure over a longer horizon. Short-term, however, the key level is the Fibonacci retracement at 102.87. The price is already below it, weakening buying momentum and opening the way toward the next support around 94.8, which coincides with the 50-session moving average. Only defending this area would provide a solid foundation for a new attempt to attack resistance at 110–114; breaking below it would risk deepening the correction toward 90.


Morning Briefing: Dollar gains, oil falls. EURUSD at multi-month lows


Daily Summary: US100 Hits New Highs on Weak NFP 🚨

Oil down nearly 5% following the announcement that European diesel reserves will be released💡


BREAKING: US NFP data surprises to the downside; USD dips🔥