


After digesting a heavy batch of data from Asian heavyweights—including Japan's GDP rebound and China’s record trade surplus—alongside fresh Eurozone trade figures, Tuesday’s macro calendar is now virtually empty. This silence is sharpening the market's focus on the fast-moving developments in the Iran war.
We are seeing a temporary breather in the oil market and a bump in risk currencies like the AUD, but the current optimism is fragile. While Donald Trump’s suggestions that the war could be "over soon" provided a welcome boost to sentiment today, words alone may not be enough to sustain a long-term rally if Iran continues its military defiance.
The only significant data point remaining is the crude oil inventory report. Given the recent surge in volatility—with Brent crude currently trading near $89.50 following a sharp plunge from $120—investors are highly sensitized to any data that might impact supply.
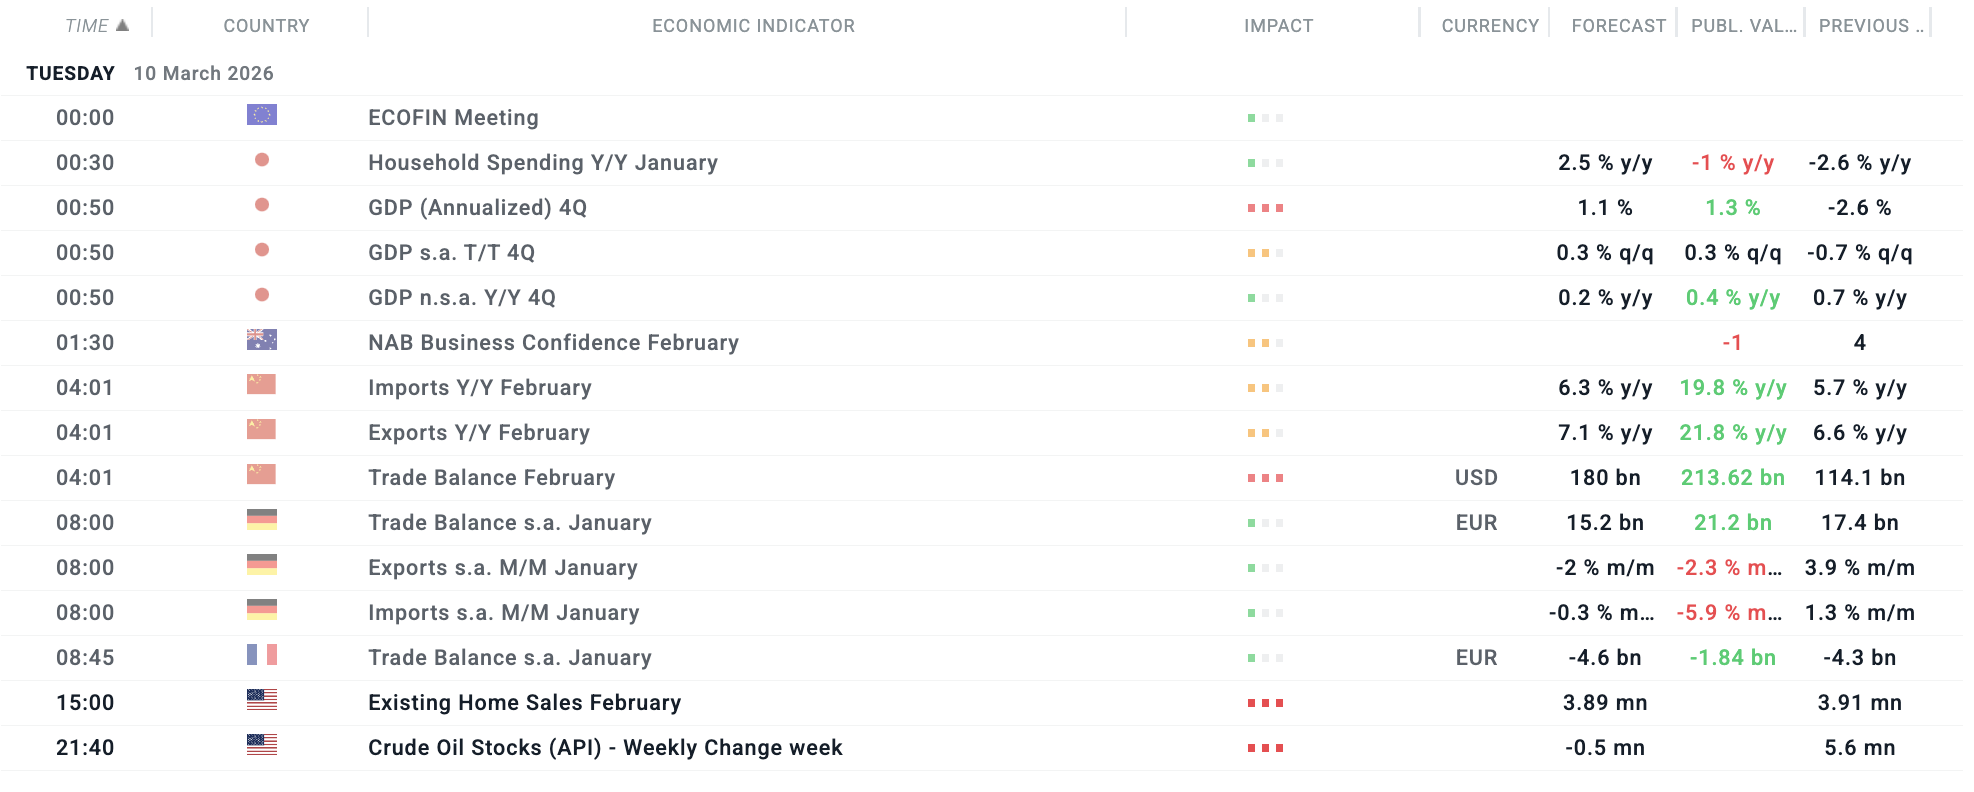
All times CET. Filtered by: US, UK, France, Germany, Eurozone, Japan, Australia, New Zealand, China, Canada. Source: xStation5


Daily Summary: Oil at five-month highs, indices under pressure (23.10.2026)


BREAKING: France slows down, Germany holds on. Euro falls below 1.12



Daily Summary: Valuations Under Pressure, Capital Moves Away From Technology

Market Wrap: "Decent" results are not enough – tech stocks fall further; oil highest since May (22.10.2026)