


Inflation is dominating the calendar as the week comes to a close. This morning we saw the final readings from France; we’re now awaiting the report from Spain, followed by preliminary eurozone GDP before noon and the U.S. PPI in the afternoon. This is the last major reading ahead of the Fed’s December meeting, at which the market is pricing in about an 80% chance of a rate hike. Earnings season is practically over, and there are no major reports scheduled for Friday. However, investors will still be digesting Thursday’s results from Cisco and Applied Materials, which will show whether concerns about a decline in AI infrastructure investment are supported by the data.
Daily Schedule (CET)
- 08:45 FR: final inflation figures. The HICP came in at 3.7% y/y, compared with a forecast of 3.8% and a previous reading of 3.4%, and 0.4% m/m, in line with expectations. The reading is slightly lower than forecasts but continues to accelerate.
- 09:00 ES: final inflation figures. CPI at 4.9% y/y and 0.6% m/m, HICP at 4.9% y/y and 0.5% m/m, plus core inflation. Spain has one of the highest inflation rates in the eurozone, and early elections will be held there on November 29.
- 11:00 EU: preliminary GDP figures for the third quarter. The forecast is 0.4% q/q and 1.3% y/y. Employment data (0.1% q/q, 0.4% y/y) and the trade balance will be released at the same time. Strong growth amid high inflation would bolster the hawks’ case within the ECB.
- 2:30 p.m. US: PPI (Producer Price Index). The forecast is 0.4% m/m and 6.6% y/y, with the core PPI at 0.3% m/m and 5.0% y/y. Following Tuesday’s CPI release, this is another test for Fed expectations. A higher reading would reinforce the scenario of a December rate hike, while a lower one could give bonds and the oversold Nasdaq a breather.
- 2:30 p.m. CA: Wholesale sales (month-over-month), forecast: 0.5%.
- 4:30 p.m. US: EIA natural gas inventories; forecast: 67 billion cubic feet.
- 7:00 p.m. US: 20-year bond auction. Following weaker demand for debt this week, this will be another signal for the interest rate market.
In the background, there is still the diplomatic situation surrounding Iran and the unresolved issue of the Strait of Hormuz, which are keeping oil prices volatile, as well as the scandal surrounding Nvidia ahead of its earnings report on November 17 and Huang’s congressional hearing on November 18.
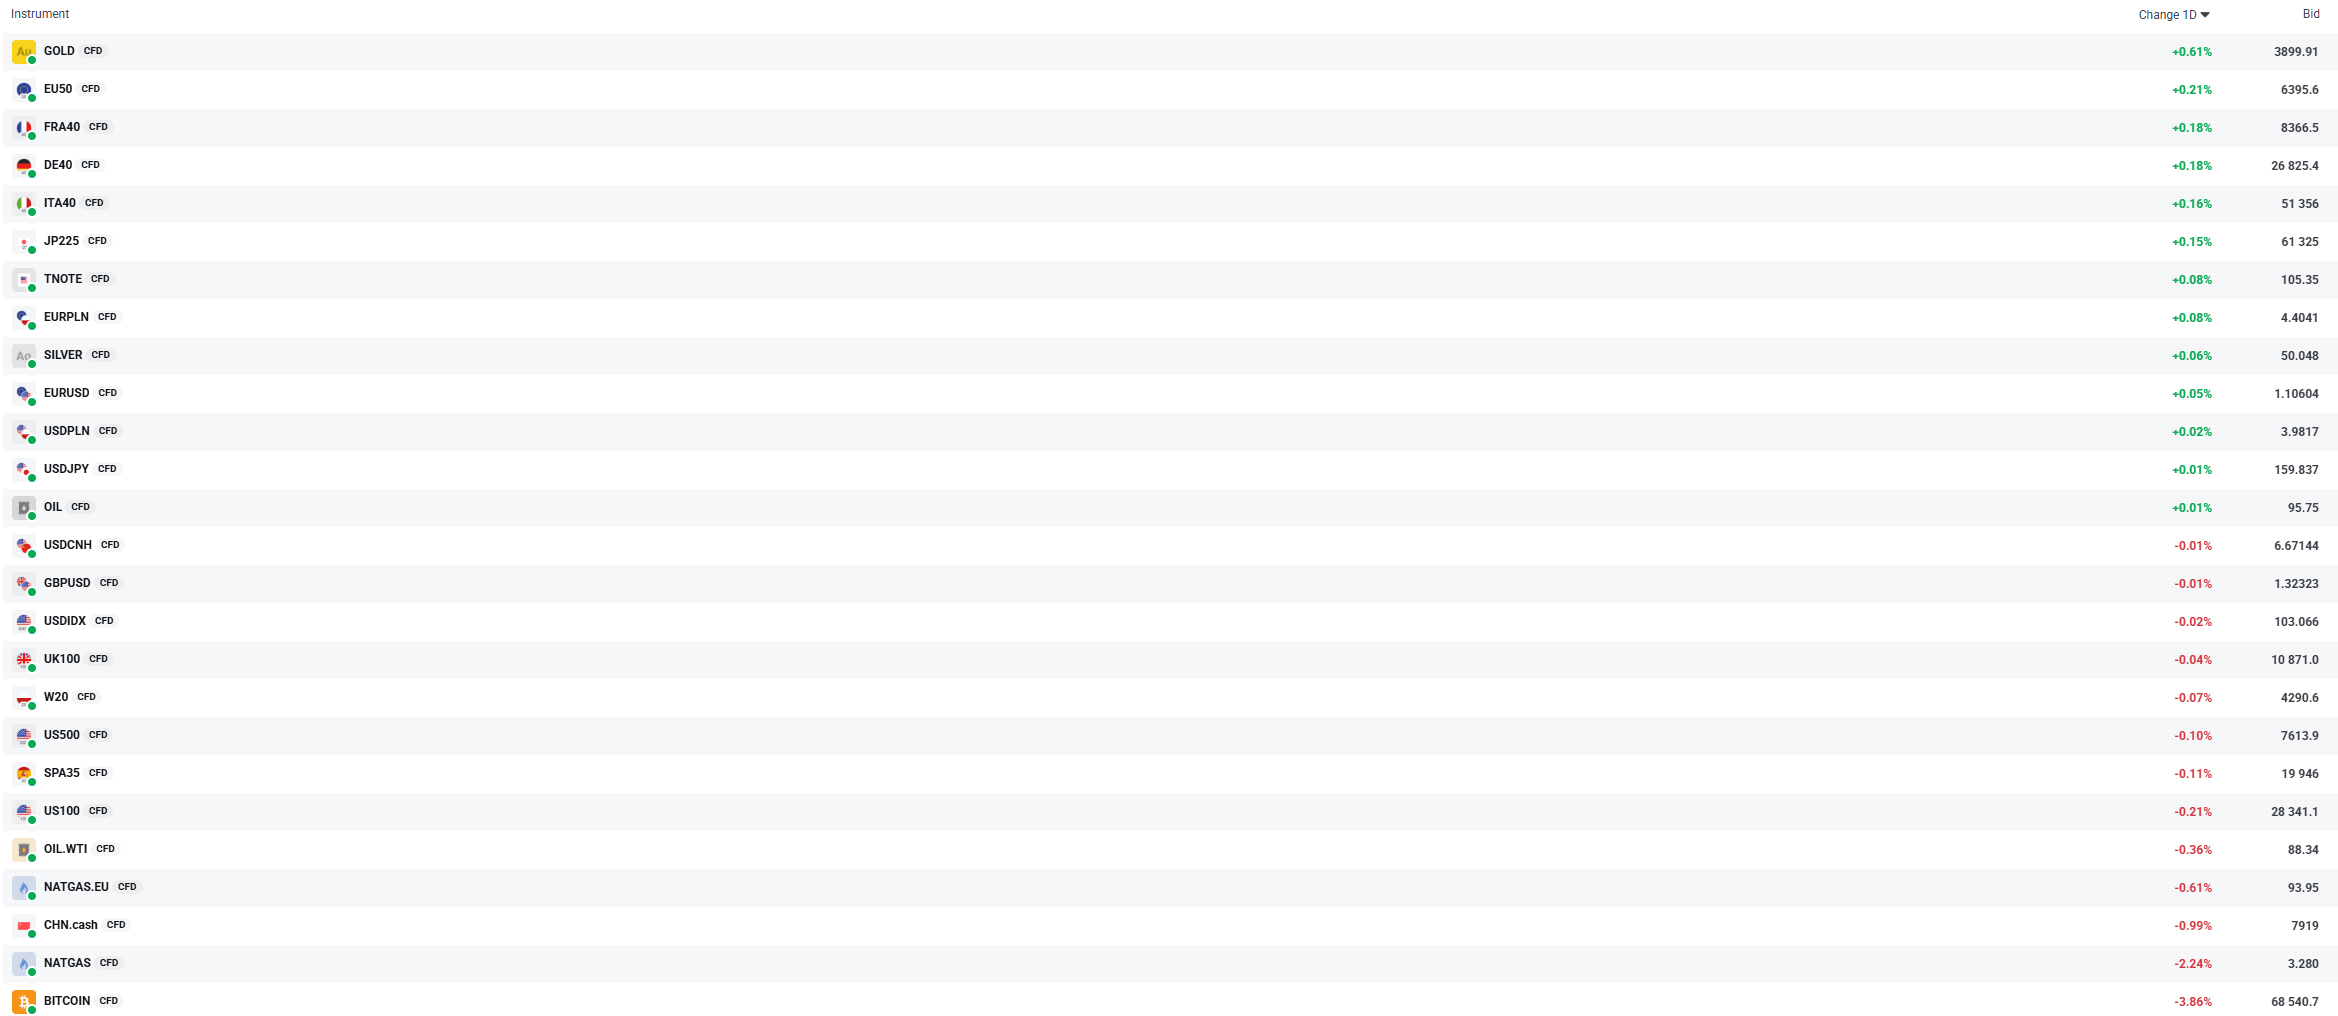
The table above shows volatility in selected, popular instruments. Gold is leading the way this morning, benefiting from a slight correction in the USD. On the downside, Bitcoin stands out with a loss of about 4%. Source: XTB



Morning Wrap - Will the markets recover from the scandal involving Nvidia's ousted CEO❓

Daily Summary: Oil Rebounds, EURUSD Falls Sharply 🗽 Wall Street Stabilizes After Nvidia Sell-Off

📉 Nvidia shares fall nearly 10% after Jensen Huang resigns
🚨US100 on the verge of a breakout