


Today’s economic calendar will be focused on US data—job openings (JOLTS), which will provide a more precise view of labor market dynamics in March, and, most importantly, the ISM Services report, where the market expects a slight month-over-month decline alongside a still very elevated prices component.
Economic Calendar
5:30 AM GMT – RBA Cash Rate & Statement – interest rate: 4.35% (forecast: 4.35%, previous: 4.10%). The decision was in line with expectations; markets are now analyzing the statement for signals on further tightening and the inflation outlook.
7:30 AM GMT – Switzerland CPI YoY – forecast: 0.6% y/y, previous: 0.3%. Inflation is expected to accelerate, though it remains low compared to global peers.
7:30 AM GMT – Switzerland CPI MoM – forecast: 0.3% m/m, previous: 0.2%. Indicates a modest rebound in short-term price pressures.
7:30 AM GMT – Switzerland Core CPI YoY – forecast: 0.5% y/y, previous: 0.4%. Core inflation remains moderate, limiting pressure on the SNB.
7:45 AM GMT – France Budget Balance – previous: -€32.12B. No forecast available; important for assessing fiscal stability in the euro area.
1:30 PM GMT - US Trade Balance – forecast: -$69.5B, previous: -$57.3B. A wider deficit could weigh on the USD.
1:30 PM GMT – Canada Trade Balance – forecast: -C$2.5B, previous: -C$5.74B. Expected improvement may support the Canadian dollar.
1:55 PM GMT – US Redbook YoY – previous: 7.7%. A gauge of real-time consumer activity in the US.
2:45 PM GMT – US S&P Services PMI Final – forecast: 51.3, previous: 51.3. Indicates stabilization in the services sector.
2:45 PM GMT – US S&P Composite PMI Final – forecast: 52.1, previous: 52.0. Slight improvement in overall economic activity.
3 PM GMT – US JOLTS Job Openings – forecast: 6.85M, previous: 6.882M. Reflects stable labor demand; a key indicator for the Fed.
3 PM GMT – US ISM Services PMI – forecast: 53.7, previous: 54.0. A modest decline expected, but the sector remains in expansion territory.
3 PM GMT – US New Home Sales – forecast: 0.652M, previous: 0.587M. Expected rebound in housing demand.
3 PM GMT – US New Home Sales MoM – forecast: 3.0%, previous: -17.6%. Strong recovery following a sharp prior decline.
3 PM GMT – US ISM Services Prices Paid – previous: 70.7. Elevated levels signal persistent inflationary pressure.
3 PM GMT – US ISM Services Employment – previous: 45.2. Below 50, indicating contraction in services employment.
3 PM GMT – US ISM Services New Orders – previous: 60.6. Strong demand component supporting the services sector.
Central Bank Speakers
6:30 AM GMT – RBA Press Conference (ongoing)
9 AM GMT – ECB’s Panetta
3 PM GMT – Fed’s Bowman
4:40 PM GMT – ECB’s Lane
5:30 PM GMT – Fed’s Barr
Earnings Releases
11:45 AM GMT – Pfizer Q1 2026
12 PM GMT – PayPal Q1 2026
9:15 PM GMT - AMD Q1 2026
9:50 PM GMT - Super Micro Fiscal Q3 2026
EURUSD Chart (D1)
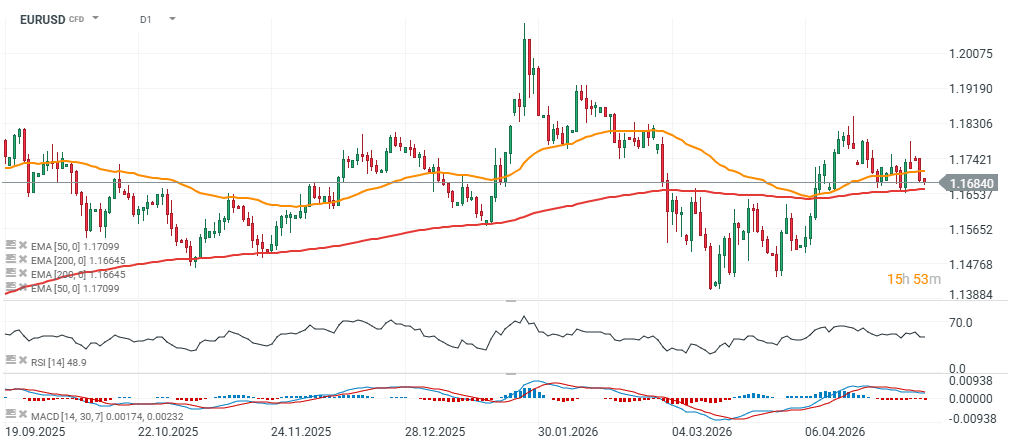
Source: xStation5

Daily summary 📈 Precious metals and stock indices rebound as Treasury yields fall

Oil gains as U.S. crude inventories fall

U.S. indices attempt to rebound after recent losses


Hot inflation data from the US🔥📈 PPI and retail sales are rising!