


Gold is up more than 1% today despite weaker sentiment across risk assets, while bulls are hoping that the precious metal has already absorbed most of the losses triggered by rising US Treasury yields. Potential catalysts for a stronger rebound could include an improvement in the situation surrounding Iran and weaker expectations for further Fed rate hikes. Unfortunately, neither currently appears likely, meaning that the stabilization around USD 4,100–4,150 has so far been largely technical in nature. At the same time, US Treasury policy could provide an additional source of support before year-end.
-
Gold has remained under pressure since the Fed’s 25 bp rate hike in September, although the scale of the decline has been relatively modest compared with the very sharp rise in both nominal and real interest rates in the US. The US 10-year Treasury yield climbed toward 5.3%, while the 10-year TIPS yield, often used as a proxy for real interest rates, moved to just below 3%.
-
Gold’s relatively muted response to these developments may suggest that the historically negative correlation between gold and interest rates has weakened. In August and early September, investors continued to increase their exposure to gold despite rising bond yields. Retail investors added to gold ETF positions, while institutional investors increased long positions in the futures market.
-
Central banks remain an important source of demand for gold. The People’s Bank of China was once again among the largest buyers of bullion in 2026, although the number of central banks increasing their gold reserves has declined. The latest World Gold Council survey showed that a record 45% of central banks expect to increase their gold reserves over the coming year, which could translate into stronger official-sector demand during larger price corrections. If part of the current inflation pressure in the US proves temporary, this could also give the Fed more room to limit the scale of further monetary tightening if the situation in the Middle East stabilizes.
Central banks accelerate gold purchases again. September strongest in almost two years?
Central bank demand remains one of the most important structural pillars of the gold market: according to preliminary World Gold Council data based on reports from central banks and the IMF, monetary authorities purchased around 63 tonnes of gold in September. This was the highest monthly total since November 2024 and a clear signal that, despite historically high nominal bullion prices, the official sector continues to increase its exposure to gold.
The activity of the People’s Bank of China remains particularly important. The PBoC continued to increase its gold reserves in recent months and, according to World Gold Council data, now holds around 2,410 tonnes of bullion. Gold accounts for approximately 9% of China’s total reserves. From a market perspective, this is not only a matter of asset diversification, but also part of a gradual effort to reduce dependence on the US dollar as the dominant reserve currency.
Some market participants believe this trend could strengthen further over the coming years. For many emerging-market institutions, the natural alternative to the dollar may not necessarily be the euro or the yen, but gold. Another factor is the increasingly frequent use of the dollar as an instrument of economic policy and sanctions, which may give some countries a stronger incentive to diversify their reserve assets.
At the same time, the picture of central bank gold demand is not entirely one-sided. Demand remains very strong, but some countries have also been forced to sell gold this year in order to raise liquidity following the outbreak of the US-Israeli war with Iran. This does not, however, change the broader trend: in an environment of elevated geopolitical uncertainty and growing debate over the stability of fiat currencies, gold continues to play the role of a strategic reserve asset.
Investors expect new record highs in gold within one to two years
Despite the significant correction from the January peak, some fund managers believe gold could set new all-time highs within a relatively short period. Some forecasts point to a new record within 12–18 months, while more conservative estimates suggest a horizon of up to two years.
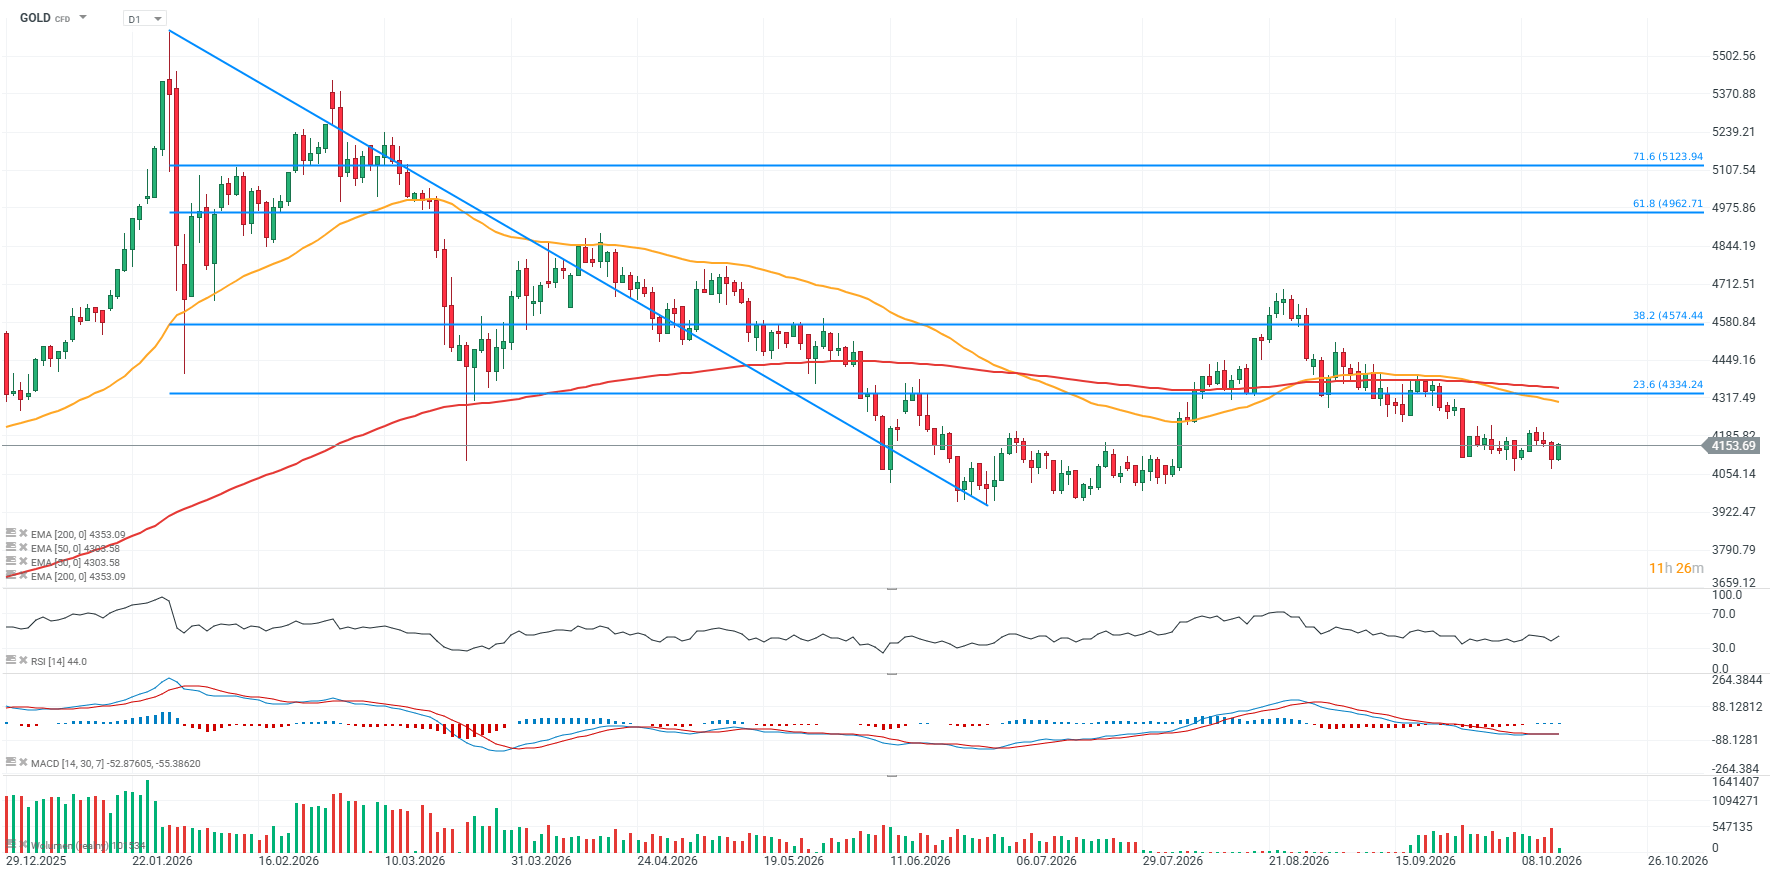
The market remains highly volatile. In January, gold rose above USD 5,500 per ounce, setting an all-time high after a very strong rally. Since then, prices have corrected significantly, although they remain at levels that are still exceptionally high by historical standards. On Wednesday, gold fell by around 2% to below USD 4,100 per ounce as investors increased expectations for another Federal Reserve rate hike.
In the short term, Fed policy and the level of real yields remain among the main risks for bullion prices. Higher interest rates increase the opportunity cost of holding a non-yielding asset, meaning further rate hikes could limit the pace of any recovery. On the other hand, the longer-term drivers of gold demand extend well beyond US monetary policy alone.
Support for prices also comes from the broader macroeconomic environment: growing concerns about the condition of public finances, declining confidence in fiat currencies and the increasing need among central banks to preserve the real value of their reserves. Some market participants believe that the USD 4,000 area may be close to the level from which another major upward leg could begin, although this should not be treated as a confirmed market bottom.
Weaker confidence in the dollar and rising debt support long-term demand for gold
One of the most important arguments behind the long-term bullish case for gold is the deteriorating state of public finances across major economies, particularly in the United States. Rising government debt is increasing concerns that, during the next economic downturn, central banks may once again turn to very loose monetary policy and a renewed expansion of the money supply. Unlike fiat currencies, the supply of gold cannot be rapidly increased by a central bank decision, which remains one of the key long-term investment arguments in favour of the precious metal.
There are also growing concerns in the market about the possibility of a more serious financial event. Some family offices are reportedly increasing their exposure to gold while reducing the share of government bonds in their portfolios, treating bullion as a diversification tool in an increasingly unstable macroeconomic environment. The geopolitical role of the dollar also remains important. The more frequently the US currency is used as an instrument of political or sanctions pressure, the stronger the incentive may become for some countries to reduce their dependence on it. In such a scenario, gold could benefit not only from traditional safe-haven demand, but also from a gradual shift in the structure of global reserves.
Central banks are increasingly facing the question of how to preserve the real value of reserves in an environment of high debt, fiscal uncertainty and weaker confidence in fiat money. This creates strong fundamental support for the gold market. If geopolitical tensions, financial instability and concerns over the future direction of fiscal and monetary policy persist, structural pressure to increase gold allocations in portfolios may remain significant even during periodic and potentially deep price corrections.
GOLD chart (D1 interval)
 Source: XTB


Sell-off in the semiconductor market 📉🖥️


Economic Calendar: European stocks open lower⬇️; will the PPI confirm the CPI’s inflationary trend❓

🚨Morning Wrap: A weaker dollar, strong gold, and a tech sector in free fall—what’s driving the market❓

Daily Summary: Rising inflation weighs on markets, semiconductors suffer most (14.10.2026)