


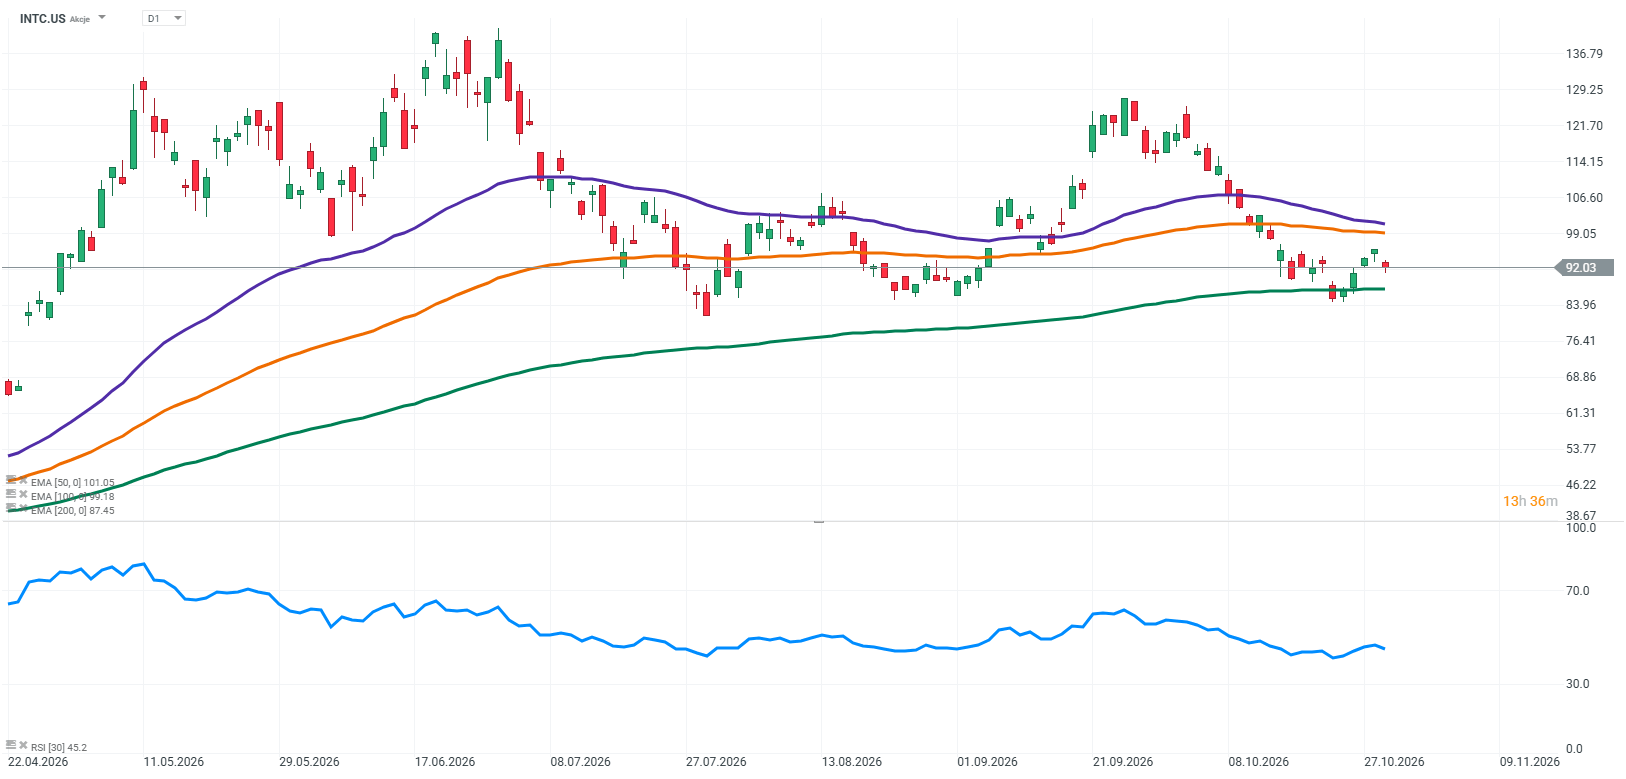
Intel reported results that comfortably beat Wall Street expectations. Revenue increased 21% year over year to $16.5 billion, while adjusted earnings per share came in at $0.52, compared with consensus estimates of approximately $0.40. Despite these strong numbers, the market reaction was brutal. Intel shares fell around 20% in after-hours trading following the release. Investors clearly concluded that one strong quarter is not enough to restore confidence in Intel’s turnaround, particularly when the outlook for the coming months leaves so much to be desired.
The biggest disappointment was the company’s guidance for the fourth quarter. Intel expects revenue of $15–16 billion, compared with analyst expectations of approximately $17 billion. The earnings outlook was even worse. The company forecast adjusted EPS of $0.25, well below the market consensus of around $0.43. On top of that, adjusted gross margin is expected to decline from 44.1% to approximately 38%. This is a clear indication that improving quarterly results does not mean Intel has resolved its underlying operational problems. The company continues to struggle to achieve the level of profitability needed to compete with the leading players in the semiconductor industry.
Intel – Key Financial Results for Q3 2026
-
Revenue: $16.51 billion, up 21% year over year (compared with $13.7 billion a year earlier).
-
Net income: $3.3 billion, down 18% year over year.
-
Adjusted earnings per share (non-GAAP EPS): $0.52, compared with $0.23 a year earlier. Consensus was approximately $0.40.
-
GAAP gross margin: 43.0%, compared with 38.2% a year earlier.
-
Operating margin: 19.6%, compared with 11.2% a year earlier.
-
Cash flow from operations: $5.1 billion.
Segment performance:
-
Data Center and AI: $7.3 billion in revenue, up 78% year over year.
-
Client Computing Group (PC): $8.1 billion in revenue, down 5% year over year.
-
Intel Foundry: $6.7 billion in revenue, up 58% year over year.
The revenue breakdown is particularly revealing. The Data Center and AI segment increased sales by 78% year over year to $7.3 billion. This should be one of the strongest arguments in favor of Intel’s turnaround. Yet even here, there is a significant limitation. Despite strong demand, Intel cannot supply customers with enough Xeon server processors. The company has orders, customers and a growing market, but lacks the production capacity to fully capitalize on the opportunity. In an industry where the ability to rapidly scale supply is one of the most important competitive advantages, this remains a serious weakness.
Meanwhile, Intel’s core business, namely processors for personal computers, continues to struggle. Revenue in the Client Computing Group declined 5% to $8.1 billion. Rising memory prices and limited component availability are making matters worse, while management does not expect any meaningful improvement before the second half of 2027. This means Intel cannot count on a quick recovery in its largest segment to help stabilize results while it undertakes an expensive transformation of the rest of its business.
Production is another area of concern. Disruptions at Intel’s Kiryat Gat facility in Israel are expected to reduce revenue by approximately $600 million across the next two quarters. This issue alone does not determine the company’s future, but it fits into a much broader picture. Intel has spent years trying to rebuild its manufacturing capabilities, yet it continues to face constraints that prevent it from fulfilling orders and increasing sales. This is particularly important given its ambitions in the foundry business. Having advanced manufacturing technology is not enough if the company cannot produce at scale, on schedule and at competitive costs.
It is also important to distinguish growth in Intel Foundry revenue from actual success in its manufacturing strategy. The segment increased revenue by 58% year over year to $6.7 billion, but higher revenue does not necessarily mean Intel has built a competitive foundry business. Profitability, capacity utilization, attracting external customers and technological competitiveness with TSMC remain the key challenges. Until Intel demonstrates tangible progress in these areas, further announcements about Intel Foundry’s expansion will have limited value for investors. The market needs evidence that this business can eventually generate profits rather than simply consume billions of dollars in capital.
Financing the entire transformation is another major concern. Intel raised $23 billion through equity issuance this year, while capital expenditure is expected to increase significantly again in 2027. Rebuilding its technological and manufacturing position requires enormous amounts of capital, and the results so far offer little certainty that these investments will generate an adequate return. For shareholders, this means not only continued pressure on cash flow, but also the risk of further dilution. Investors may be right about Intel’s long-term potential and still have no guarantee that existing shareholders will benefit proportionately.
The entire Intel turnaround story is beginning to look far less convincing than the third-quarter revenue growth alone would suggest. The company is benefiting from the AI infrastructure boom, but cannot fully meet demand. It is expanding its foundry business, but has yet to prove that it can become competitive and profitable. Its financial results are improving, yet the next quarter is expected to bring a significant deterioration in margins and earnings. Add a weak PC market and the need to keep funding an extraordinarily expensive transformation, and the picture becomes considerably less attractive.
This is precisely why the sell-off following the earnings release matters so much. Investors are no longer valuing Intel solely on the promise of a return to its former position. They increasingly want evidence that such a scenario is realistic in the first place. Simply participating in the AI boom does not automatically make Intel a beneficiary of it, just as higher foundry revenue does not automatically mean its technological leadership is being restored. The company still has an enormous amount of work ahead, and its competitors are certainly not going to wait for Intel to complete its transformation.
Intel has shown that it can deliver a strong quarter. What it has not shown is that it can sustain this improvement, rebuild margins and regain competitiveness in semiconductor manufacturing. That is the fundamental distinction. At this stage, Intel’s turnaround remains an expensive undertaking whose success has yet to be validated by financial results. And after the latest earnings report, it is difficult to argue that the company is any closer to resolving its problems than investors had hoped just a few months ago.
Source: XTB Reserach


Amazon: Record-breaking operating margin outshined by capex growth


Daily Summary: Bloody Thursday on Wall Street: Nasdaq Leads the Sell-Off
Amazon Preview: After Microsoft and Alphabet, the Market Won’t Forgive a Disappointment

Intel Preview: Server CPU Boom Creates Opportunity for Improved Results