


Sentiment in global financial markets continues to be shaped by the post-election political landscape in the US, but investors' attention is increasingly focused on current macroeconomic readings. The European industrial sector delivered mixed signals: factory orders in Germany rose by 4.4% m/m in September, while industrial production in France recorded a decline of 0.5% m/m. Combined with the preliminary estimate of the HICP inflation rate at 4.0%, the economic environment of the eurozone remains challenging. It is worth remembering that the statutory objective of the European Central Bank is solely to maintain price stability. The ECB's persistent restrictive stance may further hinder the recovery of European industry in the short term.
The Bank of England raised its key interest rate by 25 bps to 4.00%. Monetary authorities signaled that today's move is unlikely to be the last hike unless the military conflict surrounding Iran is resolved. At the same time, the bank raised the UK's GDP growth forecast for 2026 to 1.6% and increased inflation expectations, projecting the rate to peak at 4.9% in Q2 2027.
Furthermore, Norges Bank kept its main interest rate unchanged at 4.50%, which was in line with market consensus. However, the hawkish tone of the statement indicates that policymakers allow for a resumption of rate hikes if necessary in the process of bringing inflation to target.
FX Market
The dollar remains under pressure...
- EURUSD: The single currency's quotations are correcting by a symbolic 0.06% towards 1.1220, influenced by mixed readings from the European economy and concerns about the health of the industrial sector.
- GBPUSD: The pound records a modest increase of 0.05% to 1.3475 following the announcement of an interest rate hike by the Bank of England.
- USDPLN: The dollar exchange rate rises by 0.24%, stabilizing in the 3.91 region.
Commodities Market
- Crude oil: Brent (+2.2%) and WTI (+1.9%) quotes are rising, attempting to stabilize after a sharp, over 14% sell-off on a weekly basis, as the market political premium associated with Donald Trump is reduced.
- Natural gas: European gas (NATGAS.EU) rebounds sharply (+6.15%) after steep weekly declines, while the US benchmark NATGAS loses 0.31%, consolidating
- Gold: continues to appreciate (+1.67%), supported by a weaker US currency and lower treasury yields.
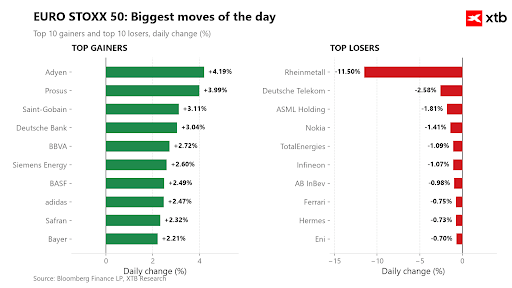
European Stocks
Top gainers:
- Prosus NV (PRX.NL): Shares of the technology holding company gain thanks to the continuation of the share buyback program and improved profitability in key e-commerce segments (up by nearly 4%).
- Compagnie de Saint-Gobain SA (SGO.FR): The company is rising thanks to effective margin defense through pricing discipline and favorable European thermal modernization trends (up by 3%).
- Adyen NV (ADYEN.NL): The share price is rebounding from an earlier wave of sell-offs, supported by double-digit revenue growth and more attractive valuation multiples (up by around 4%).
Top losers:
- Rheinmetall AG (RHM.DE): The sharp sell-off is the result of lowered forecasts for 2026 caused by the postponement of the Boxer vehicle contract and delays in ammunition acceptance (down by around 11%).
- TotalEnergies SE (TTE.FR): Selling pressure stems from general weakness in the oil and gas sector following declines in oil prices on world markets this week (down by slightly over 1%).
- ASML Holding NV (ASML.NL): The decline aligns with cooling sentiment in the semiconductor industry and market concerns over cuts in capital expenditures on chips (down by around 2%).


Norges Bank keeps rates unchanged, but leaves the door open to rate hikes. Is this really the end of the NOK strengthening, though?


Daily Summary: Blue Wave in Congress Triggers Market Euphoria, Oil Plunges

🛢️Oil suffers sharpest fall since April (-9%)
BREAKING: US oil inventories fall less than expected, but prices drop due to elections and hopes for a US-Iran deal