


📈 Equities
-
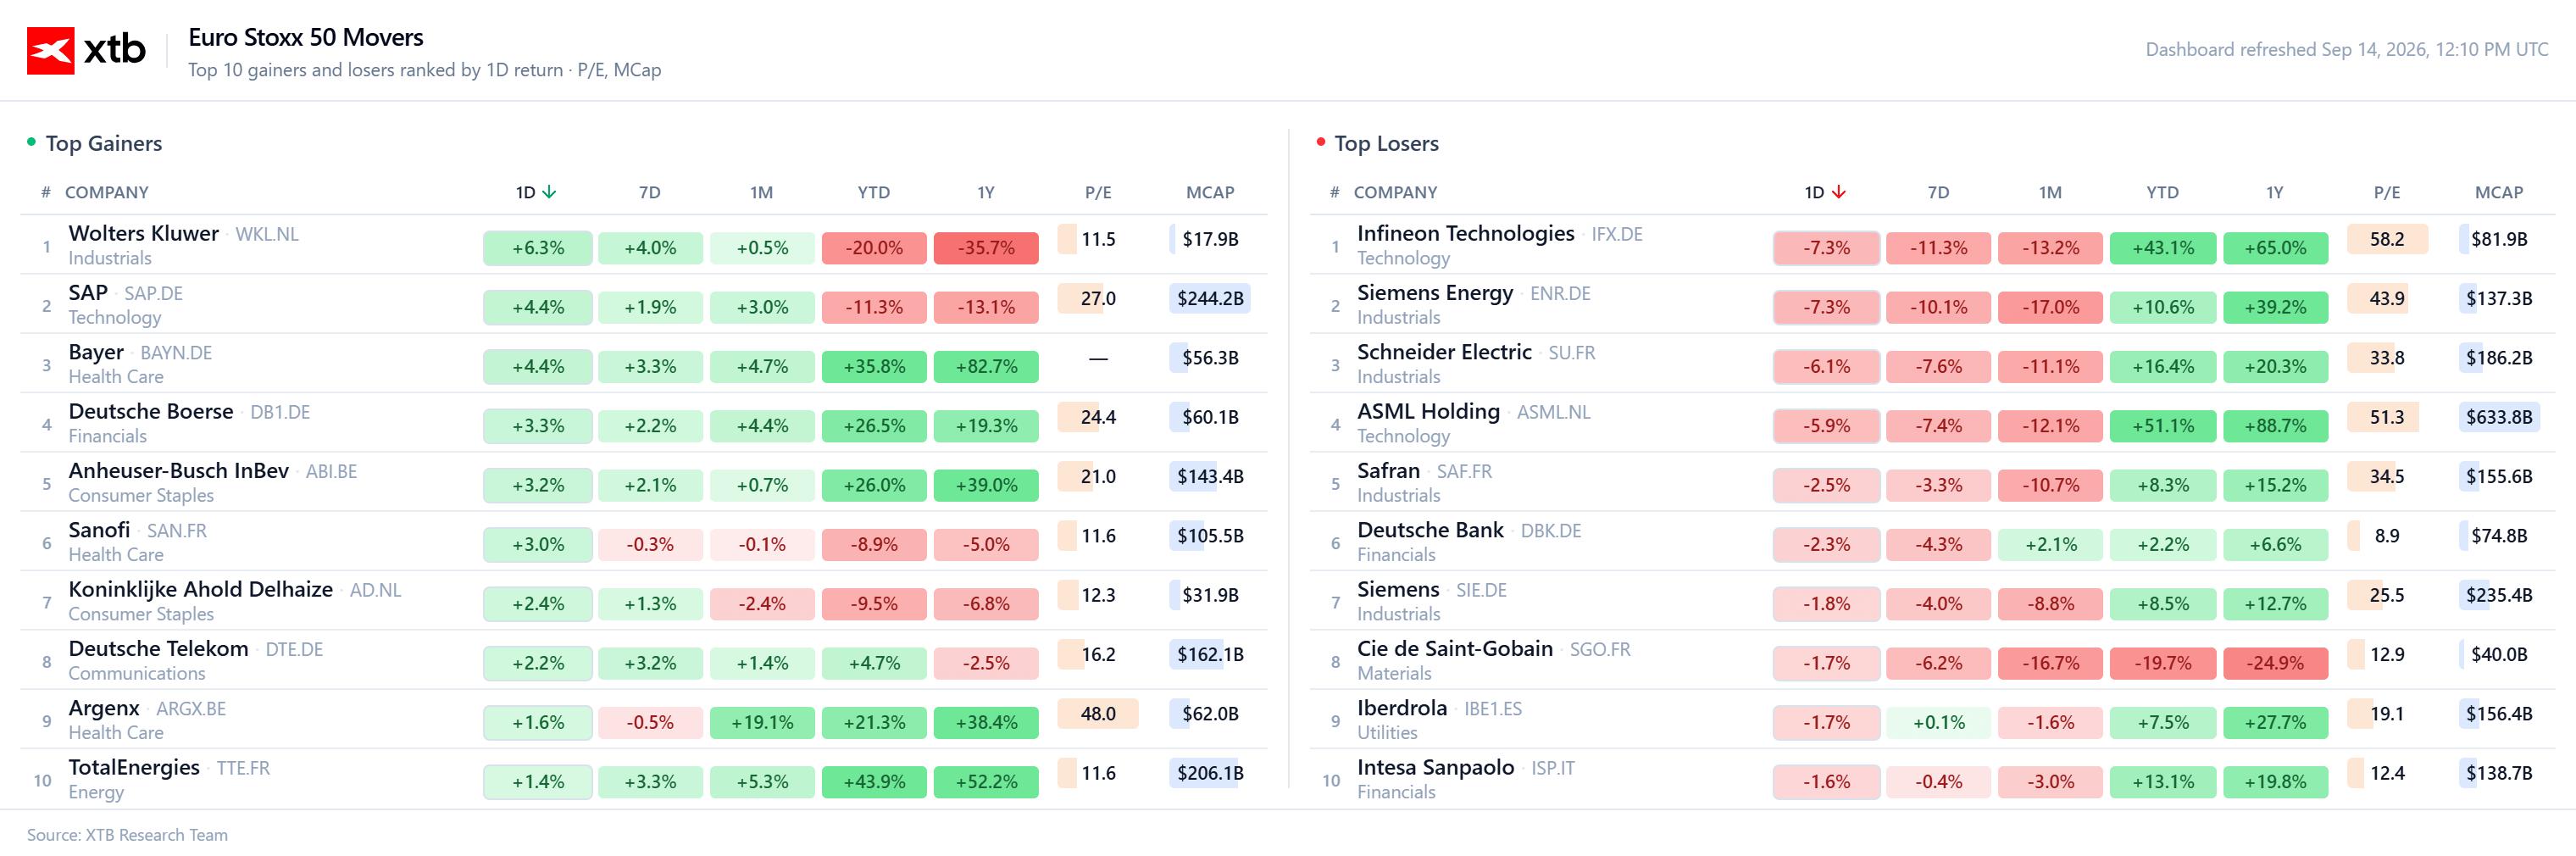
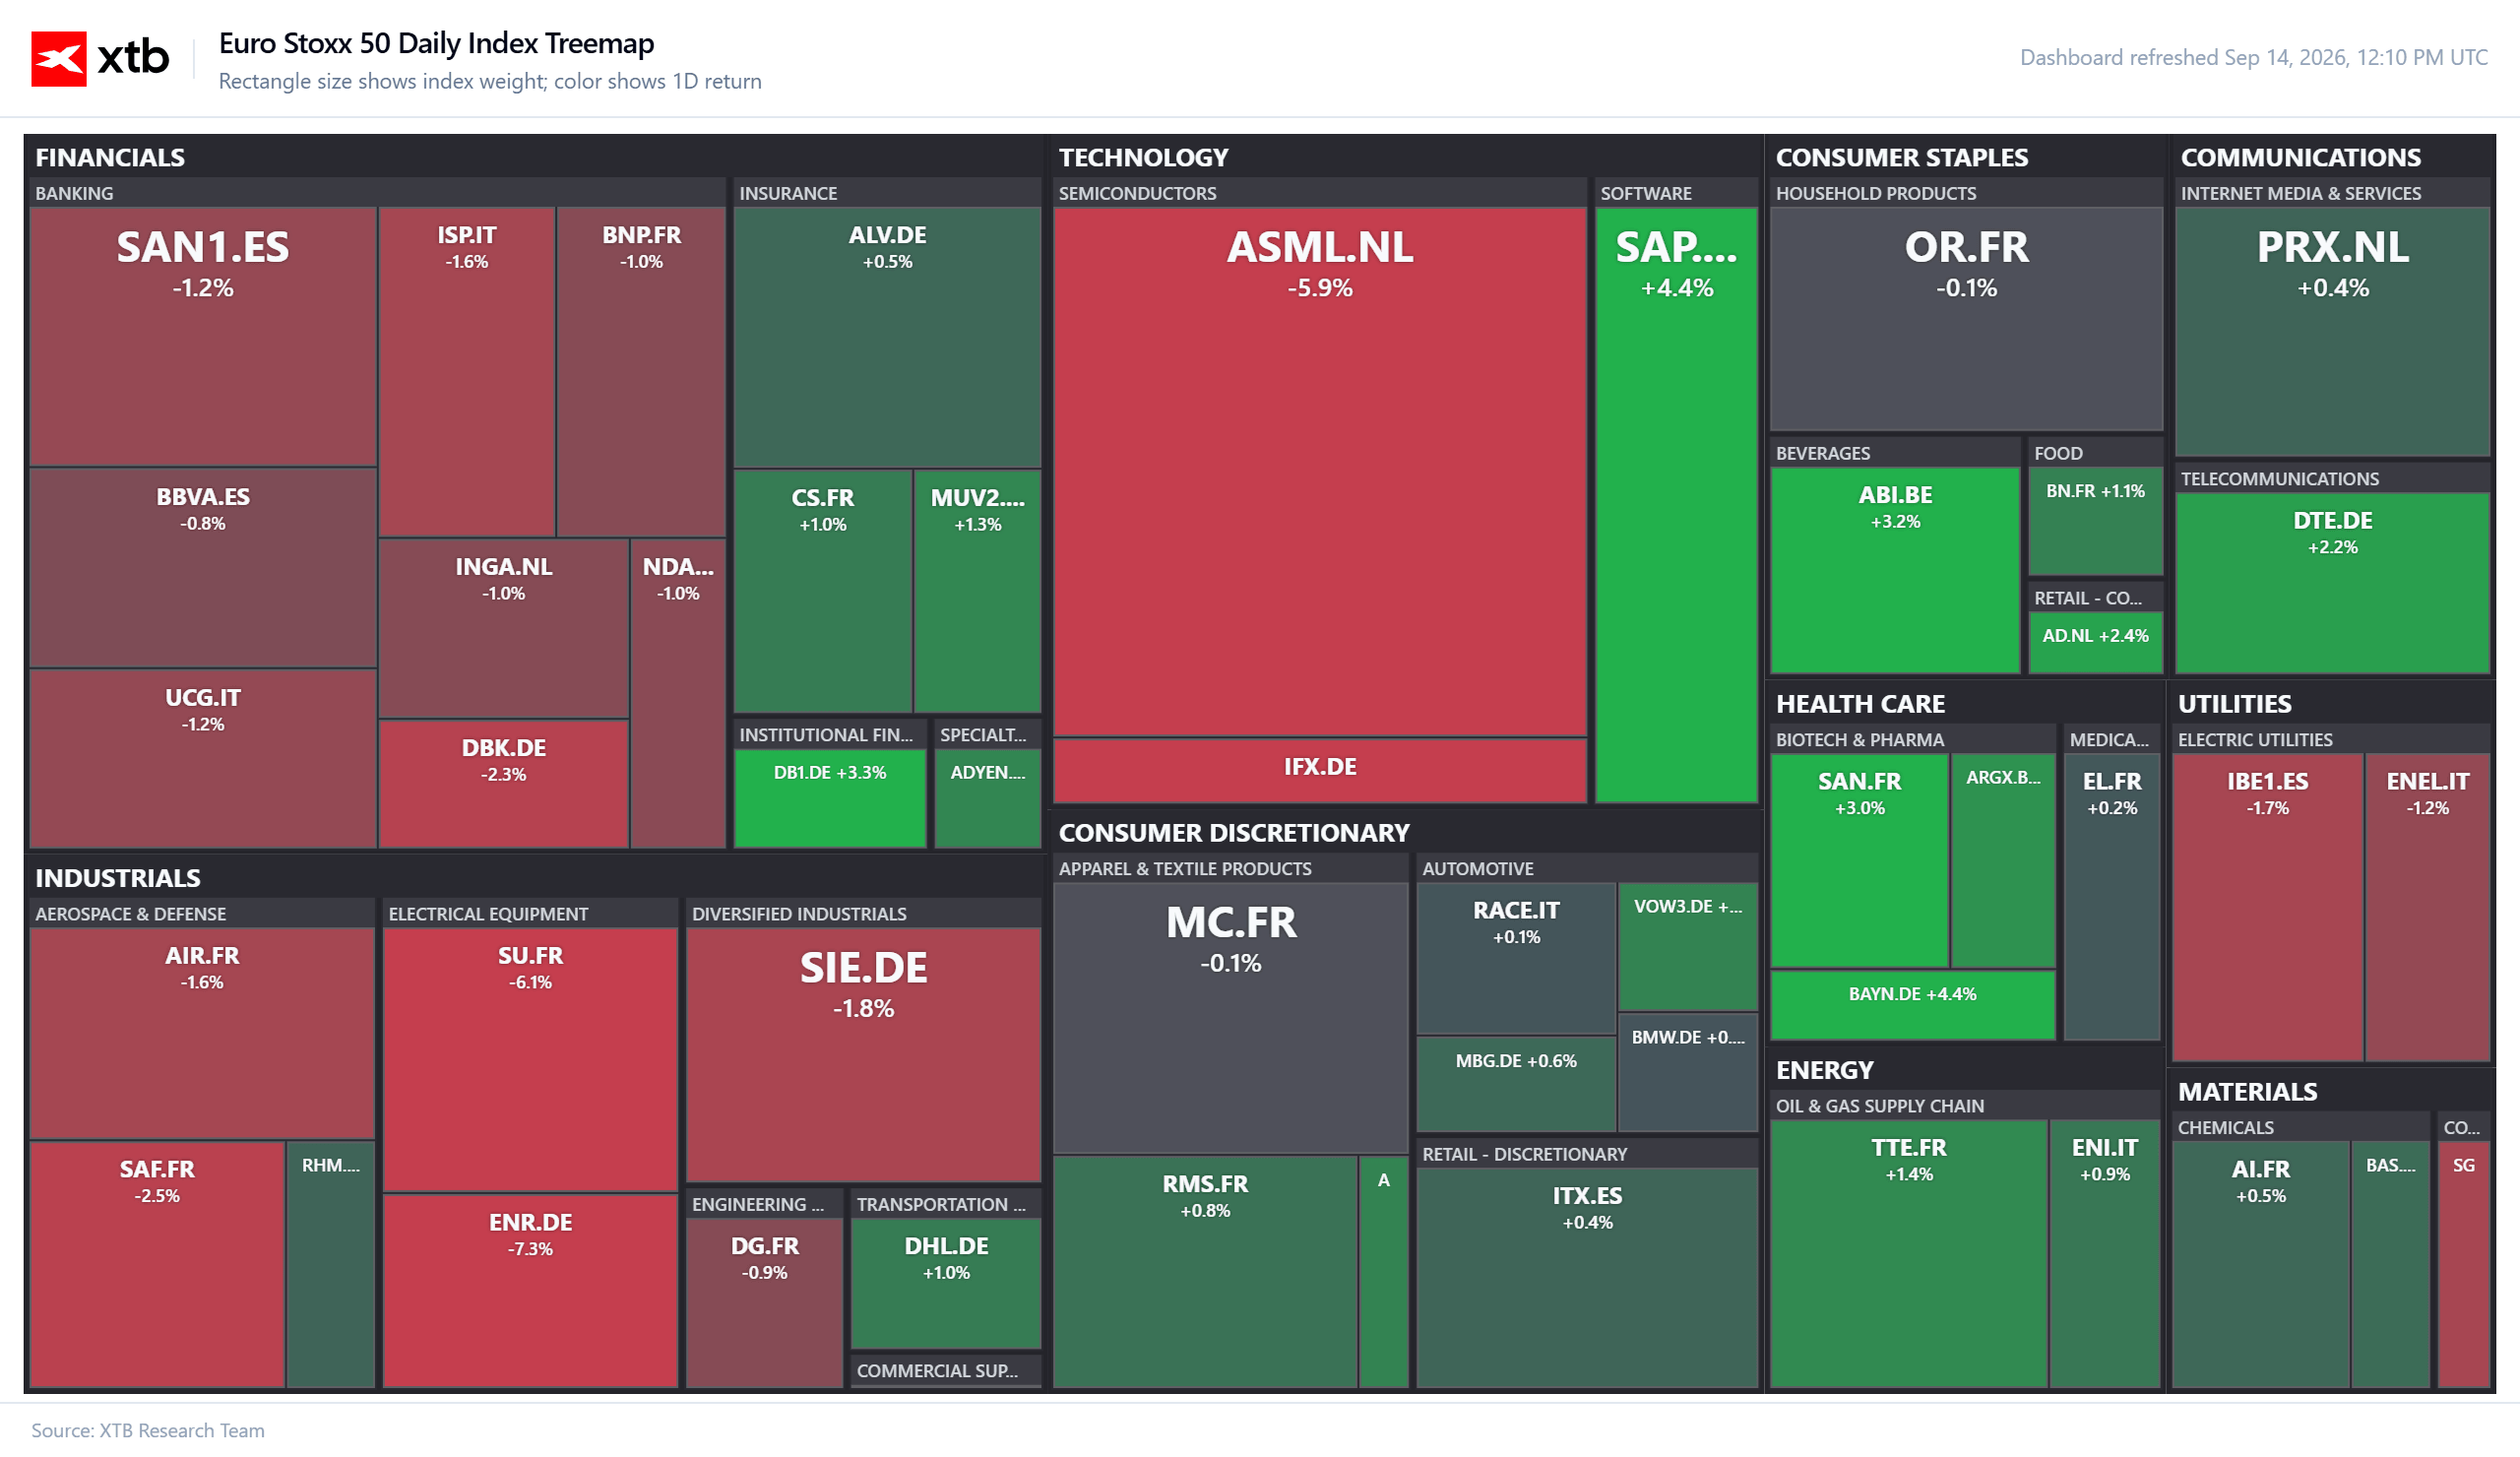
By 14:20, European indices remain clearly in the red, with nearly the entire continent trading lower: CAC 40 is down by about 0.7%, DAX by about 0.4%, and IBEX 35 by about 1%.
-
The only major green accent in Europe remains the British FTSE 100. Caution dominates the broader market, with investors closely watching the situation in the Middle East, oil prices, and upcoming central bank decisions.
-
One of the main sources of pressure on European indices today is the semiconductor sector — ASML and Infineon are losing about 6%, and some smaller companies in the European supply chain are seeing even steeper sell-offs amid a broader correction in AI-related stocks.
-
Driving the decline in the tech sector is growing uncertainty regarding the future pace of AI development and fears of slower growth in spending on data centers, servers, and advanced semiconductors. For ASML, this is particularly critical as the company is a key supplier of machinery used to manufacture the most advanced chips.
Source: xStation5
🛢️ Commodities
-
Oil is rising sharply again: Brent crude is trading above 107–108 USD per barrel, and WTI is also posting strong gains due to Middle East tensions, attacks on oil infrastructure, and delayed talks concerning the Persian Gulf region and the Strait of Hormuz.
-
The primary concern for markets is the risk of sustained high energy prices over a longer period, which amplifies inflationary pressure, drives up bond yields, and limits central banks' leeway to ease monetary policy.
-
Despite ongoing geopolitical tensions, gold is not benefiting today from its safe-haven status — the market is primarily focused on the impact of higher oil prices on inflation and Fed policy prospects, with a stronger dollar and higher bond yields further dampening gold's appeal.
🏦 Central Banks & Macroeconomics
-
Set against the backdrop of today's session is the Fed meeting taking place this week, marking one of the most critical events for global markets, where investors will focus on the interest rate decision, the Fed's statement, and guidance on future monetary policy moves.
-
Elevated oil prices further complicate the Federal Reserve's stance and increase the risk of inflation staying elevated, which could imply less room for rate cuts or a more hawkish Fed stance, acting as a negative factor for stock valuations (especially tech and growth equities).
🪙 Crypto Assets
-
The situation looks different in the crypto asset market, where positive sentiment persists: Bitcoin is currently rising by about 1.3% to the 77.8k USD range, while Ethereum is gaining about 1.2%, returning above 2.5k USD.
-
Cryptocurrencies are holding up relatively strong compared to European equities and precious metals, indicating that a portion of capital remains willing to take on risk despite heightened uncertainty across global markets.
📝 Session Summary
-
Today's session presents markets with a combination of two negative headwinds: a sharp sell-off in AI-related equities (hitting European tech particularly hard, especially ASML and Infineon) and another spike in oil prices (heightening fears over inflation, interest rates, and economic growth prospects).
-
With the pivotal Fed meeting in the background, investors remain distinctly cautious ahead of the rest of the week, while the crypto asset market stands out as one of the few bright spots thanks to today's gains in both Bitcoin and Ethereum.
Source: xStation5


Oil back above $100

Chart of the Day: AI to Slow Down; OpenAI IPO “Canceled” 🚨US100 Drops 1.7% at the Start of the Week💥


Economic Calendar: Inflation in Canada and Lagarde's speech in spotlight 🎯


Morning Wrap: A gloomy start to the week amid rising oil prices and turmoil surrounding OpenAI 🚨