


WTI crude oil continues to fall sharply, having already lost nearly 5% today (OIL.WTI -4.67%, trading at 88.55).
The sell-off was triggered by a post by Donald Trump on Truth Social, in which the US President announced that Europe had agreed to release a “huge amount” of its stockpiled diesel, and that the process was due to begin immediately.
These reports were confirmed by French President Emmanuel Macron: according to him, the G7 has decided to release reserves of both diesel and crude oil, with the entire process to be spread over four months. Earlier market reports pointed to a coordinated emergency release of around 100 million barrels within the G7 — the decision was taken in the wake of rising fuel prices ahead of the US elections in November.
Spreading the release of stocks over four months means a sustained, elevated supply of fuels over a longer period, which not only weighs on diesel but also quickly leads to a fall in crude oil prices. WTI broke through local support levels and fell to its lowest point in many sessions, well below the falling 20-day EMA (91.53), confirming the dominance of the supply side.
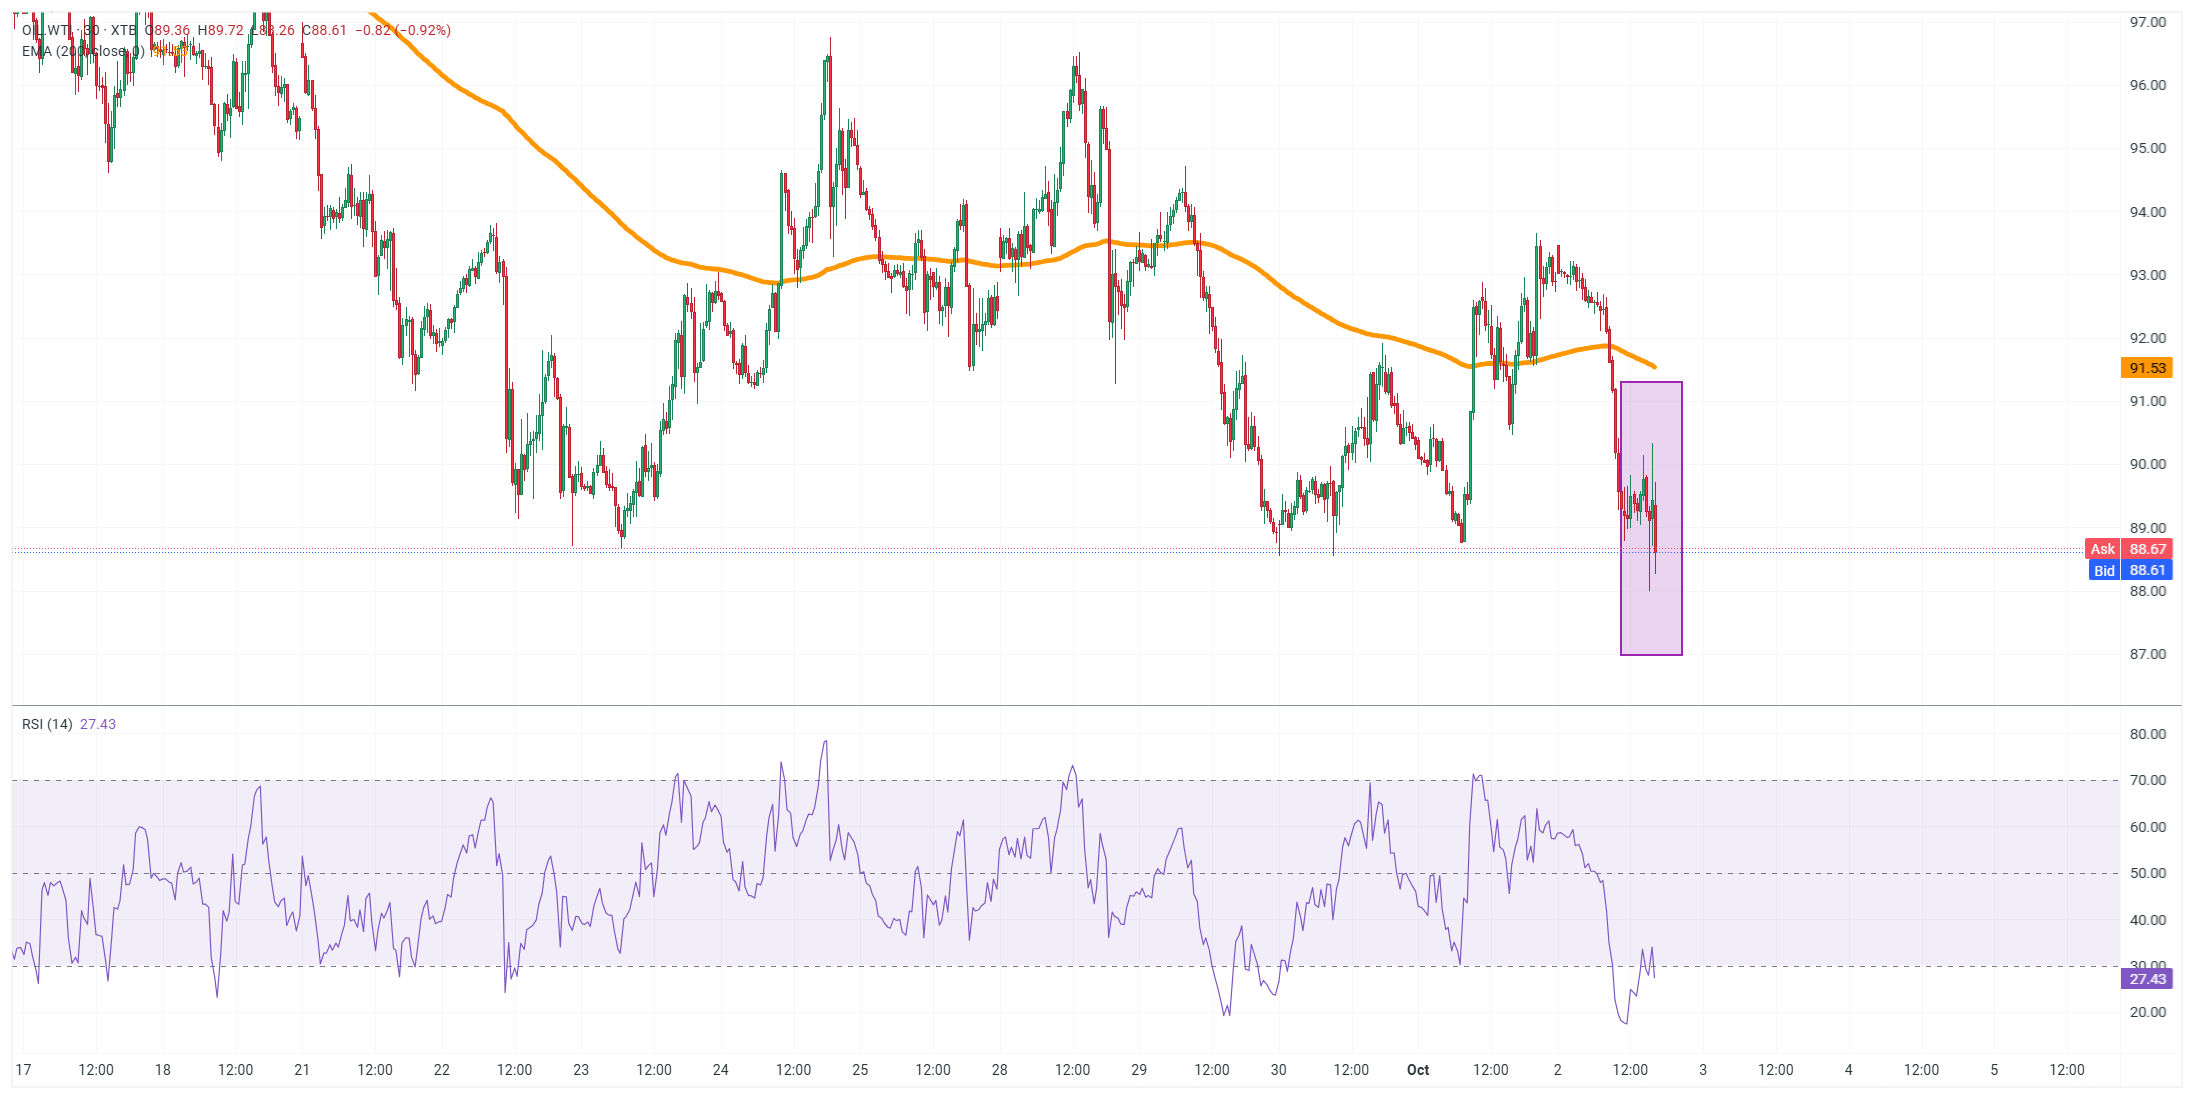
From a technical perspective, the picture remains weak — the price is trading below a falling moving average, and the RSI (14) has fallen to 27, which is close to oversold territory. This does not rule out a short-term rebound, but as long as prices remain below the 20-period EMA, the bears retain the upper hand. The reaction to the recently breached support levels will be crucial — a recovery to these levels would be the first sign that selling pressure is easing.


BREAKING: US NFP data surprises to the downside; USD dips🔥

🟡Gold takes a breath, because of oil, not NFP


Market Wrap: Tech stocks stabilize sentiment in Europe 📈 Adidas and Puma resilient despite Nike’s sell-off?

Chart of the Day: Sharp sell-off in China 📉 HK.cash posts its biggest decline since March (02.10.2026)