


The US midterm election results and the Democrats taking control of Congress are bringing major market reshuffles, with European bourses becoming the main beneficiaries of returning risk appetite. While on Wall Street optimism is dampened by concerns over the tech sector and potential cuts to AI spending, euphoria has gripped European stock exchanges. Southern European indices in Italy and Spain are gaining nearly 2,5-3%, and the broad Euro Stoxx 50 is rising almost 2% amid a clear drop in volatility. Growth in Europe is supported by capital flight into US Treasuries and a sharp sell-off of the dollar.
Beyond the reaction to events in Washington, investor attention is drawn to accelerating inflation in Europe and central bank actions. The estimated Eurozone HICP accelerated to around 4% year-on-year, reaching its highest level in three years, mainly due to a more than 20% spike in energy prices. This coincided with PMI indices falling to multi-month lows, putting the European Central Bank in an exceptionally difficult situation when making subsequent monetary decisions. Sweden's Riksbank has already decided to tighten policy, raising the rate by 25 bps to 2% and signaling further moves.
FX Market
The US dollar found itself under heavy selling pressure, recording its weakest session since September and losing across the broad market against all major currencies. Investors are discounting a scenario of harder-to-push fiscal spending by the White House, which weighed on the valuation of the American currency. As a result, the EURUSD rate returned near 1,12, and the British pound gained to around 1,35 GBPUSD. Antipodean currencies saw equally strong appreciation against the weakening dollar, with the New Zealand dollar (NZD) and the Australian dollar (AUD) each gaining around 0,7%. The sell-off of the American currency was also visible in the domestic market, where USDPLN noticeably pulled back to around 3,91.
Commodities Market
- Gold: the price shot up by nearly 3%, breaking the 4000 USD barrier under the influence of a cheaper dollar and declining bond yields.
- Silver: strong appreciation of precious and industrial metals, silver gained more than 4,5%
- Brent crude: dropped by less than 2% to around 102 USD per barrel due to the reduction of the geopolitical premium after the elections and reports of US-Iran diplomatic negotiations.
- WTI crude: slid by around 2%, falling to around 95 USD per barrel under the same factors easing supply risk.
- Natural gas in Europe: a sharp sell-off of over 6%, which pushed blue fuel prices below the threshold of 89 EUR/MWh.
European Equities
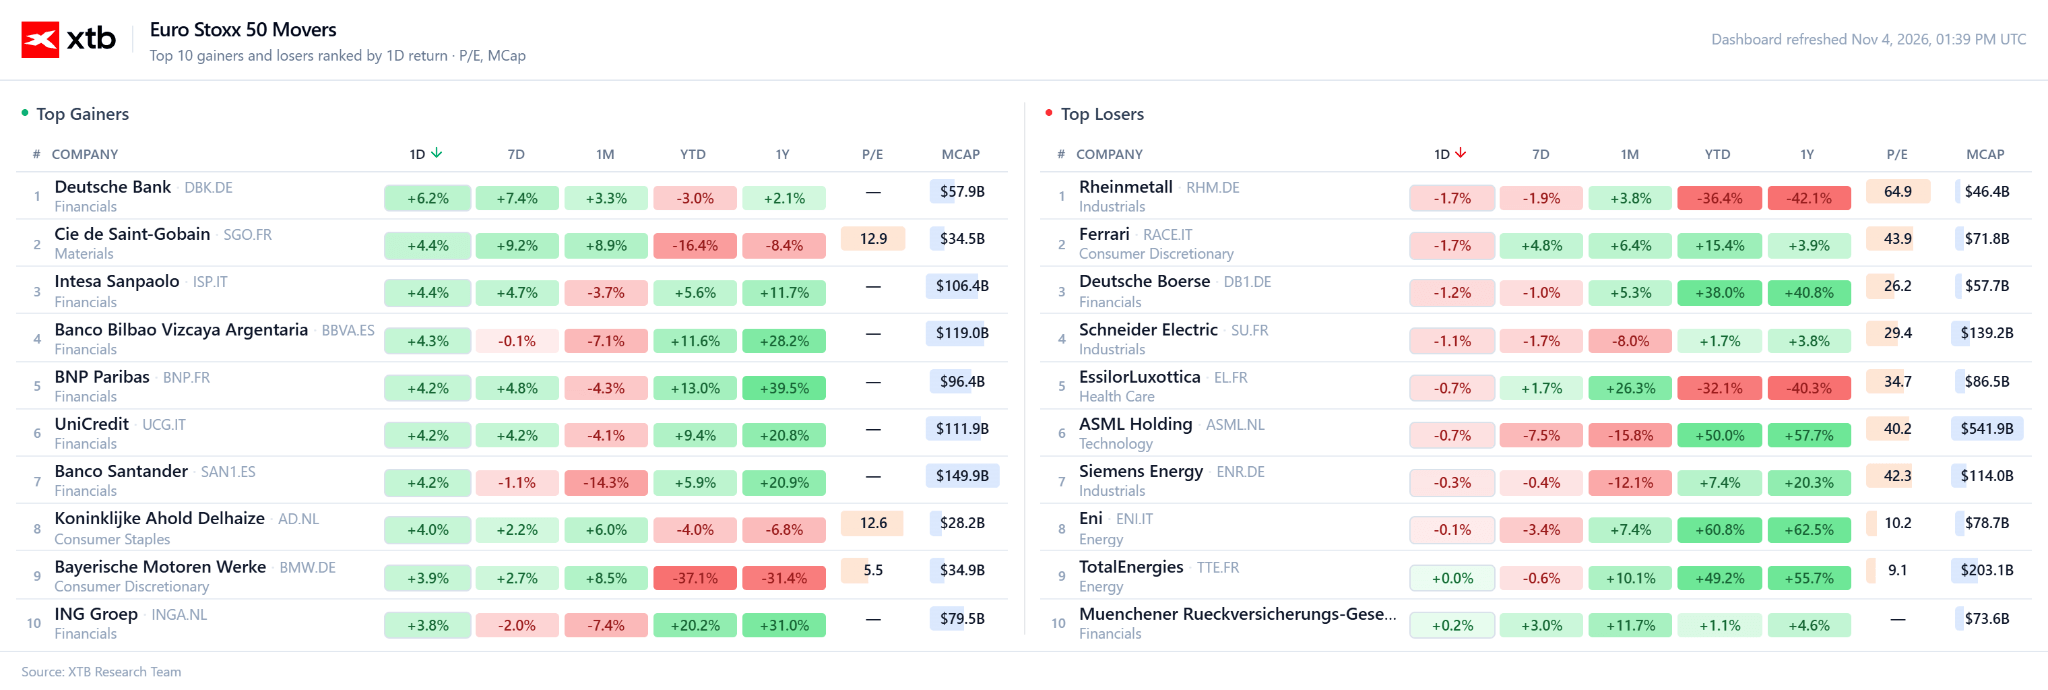
The financial sector dominated the European session, growing by nearly 4% and leading stock rallies thanks to the prospect of the ECB keeping interest rates higher and capital returning to cheap European lenders. Solid, over 2% gains were also recorded by utilities, consumer goods, and telecommunications. The only sector in the red was technology (a decline of less than 0,3%), impacted by caution surrounding AI spending.
- Ahold Delhaize (AD.NL): the market rewarded the company for solid quarterly results, an announced share buyback worth 1 billion EUR, and plans to acquire Tesco stores in the Czech Republic and Slovakia (gain of over 5,5%).
- Bayer (BAYN.DE): continuation of gains following solid Q3 results, further supported by an overall improvement in sector sentiment after Novo Nordisk raised its guidance (gain of over 3%).
- Siemens Energy (ENR.DE): correction after multi-month highs against the backdrop of post-election uncertainty surrounding US infrastructure spending (decline of less than 3%).
- Rheinmetall (RHM.DE): Democratic victory in Congress stokes concerns over tighter oversight of military spending and pressure to de-escalate armed conflicts (decline of around 2%).
- ASML Holding (ASML.NL): valuation pressure resulting from investor fears of slowing capex momentum for data centers and AI chips across the Atlantic (decline of over 1,5%).


BREAKING: US Labor Market Stronger Than Expected. ADP Report Surprises Ahead of Government Data

Spain Is Back on Its Feet 🚀 Trump's Nemesis Makes a Comeback After the Midterm Elections 📈


Novo Nordisk Earnings: Downtrend is slowing down


BREAKING: Democrats take both chambers of Congress🗽