


Stock Market 📈
-
European stock markets are rebounding, supported by falling expectations of a Fed rate hike following weaker US labor market data.
-
The German index is up by over 0.1%, the British FTSE 100 gains nearly 0.4%, and the Spanish IBEX 35 rises by more than 0.5%.
-
The French CAC 40 fell to a 6-month low due to political and budgetary uncertainty in the country.
Companies 🏢
-
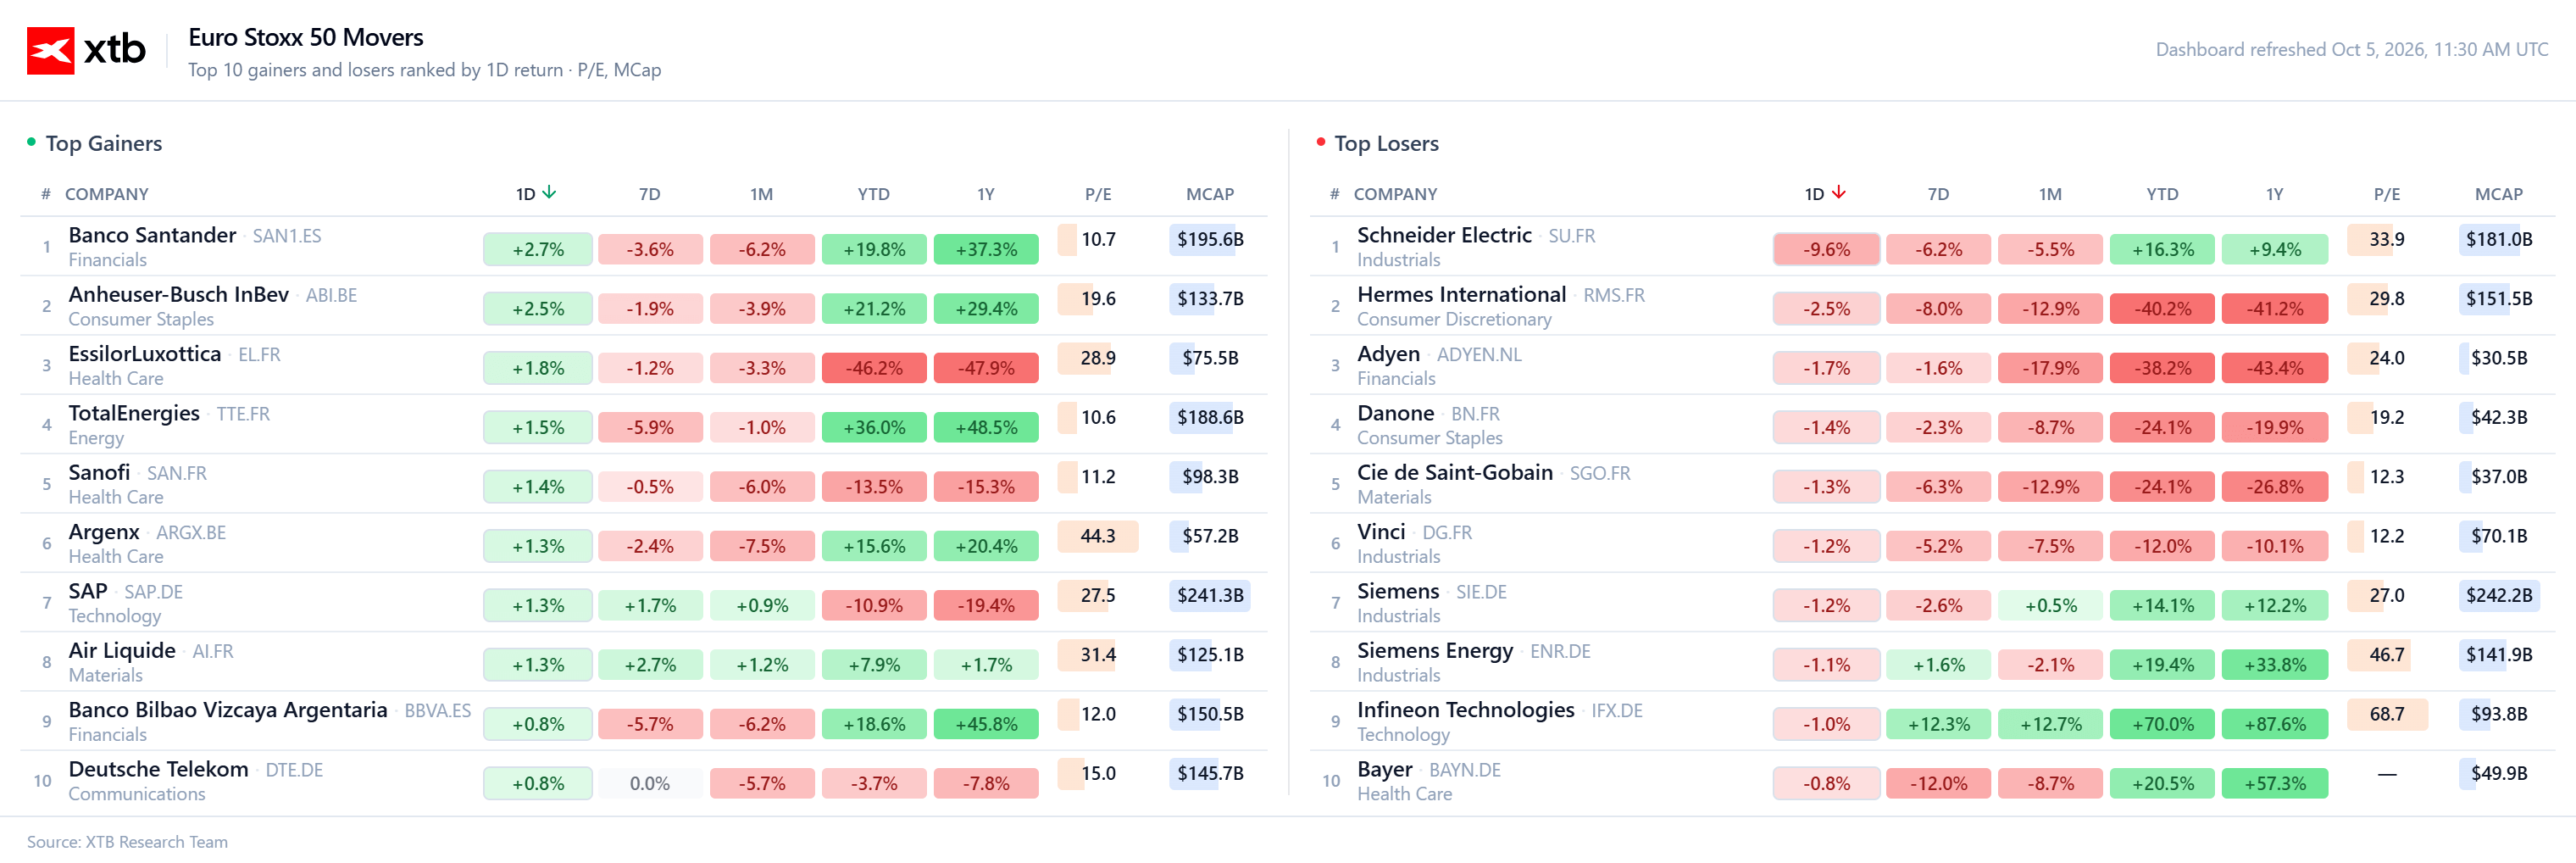
Schneider Electric is acquiring PTC for $22.6 billion, offering approximately a 40% premium over the pre-announcement share price, which is intended to accelerate growth in industrial software and artificial intelligence.
-
Schneider Electric shares were losing around 9% in the morning in reaction to the high transaction price and financing method—via the issuance of €5–6 billion in new shares (shareholder dilution) and taking on €16–17 billion in debt.
Macroeconomics and Politics 🌍
-
Eurozone PMI positively surprised, showing the fastest activity growth in over three years.
-
Higher inflation, driven mainly by energy prices, may nevertheless limit the ECB's room for further monetary easing.
-
France remains a major source of risk in Europe due to investor concerns that the government will struggle to pass its deficit reduction plan through a divided parliament ahead of next year's elections.
-
The yield on French 10-year bonds approached 5%.
-
Pedro Sánchez announced snap parliamentary elections in Spain for November 29 after failing to pass key housing reforms.
-
Polls in Spain give the advantage to the opposition People's Party (PP), likely supported by the far-right Vox, which could mark the first far-right participation in government since the return to democracy. The snap election is a risky attempt by Sánchez to regain support and keep Spain on a left-wing course.
Currencies 💵
-
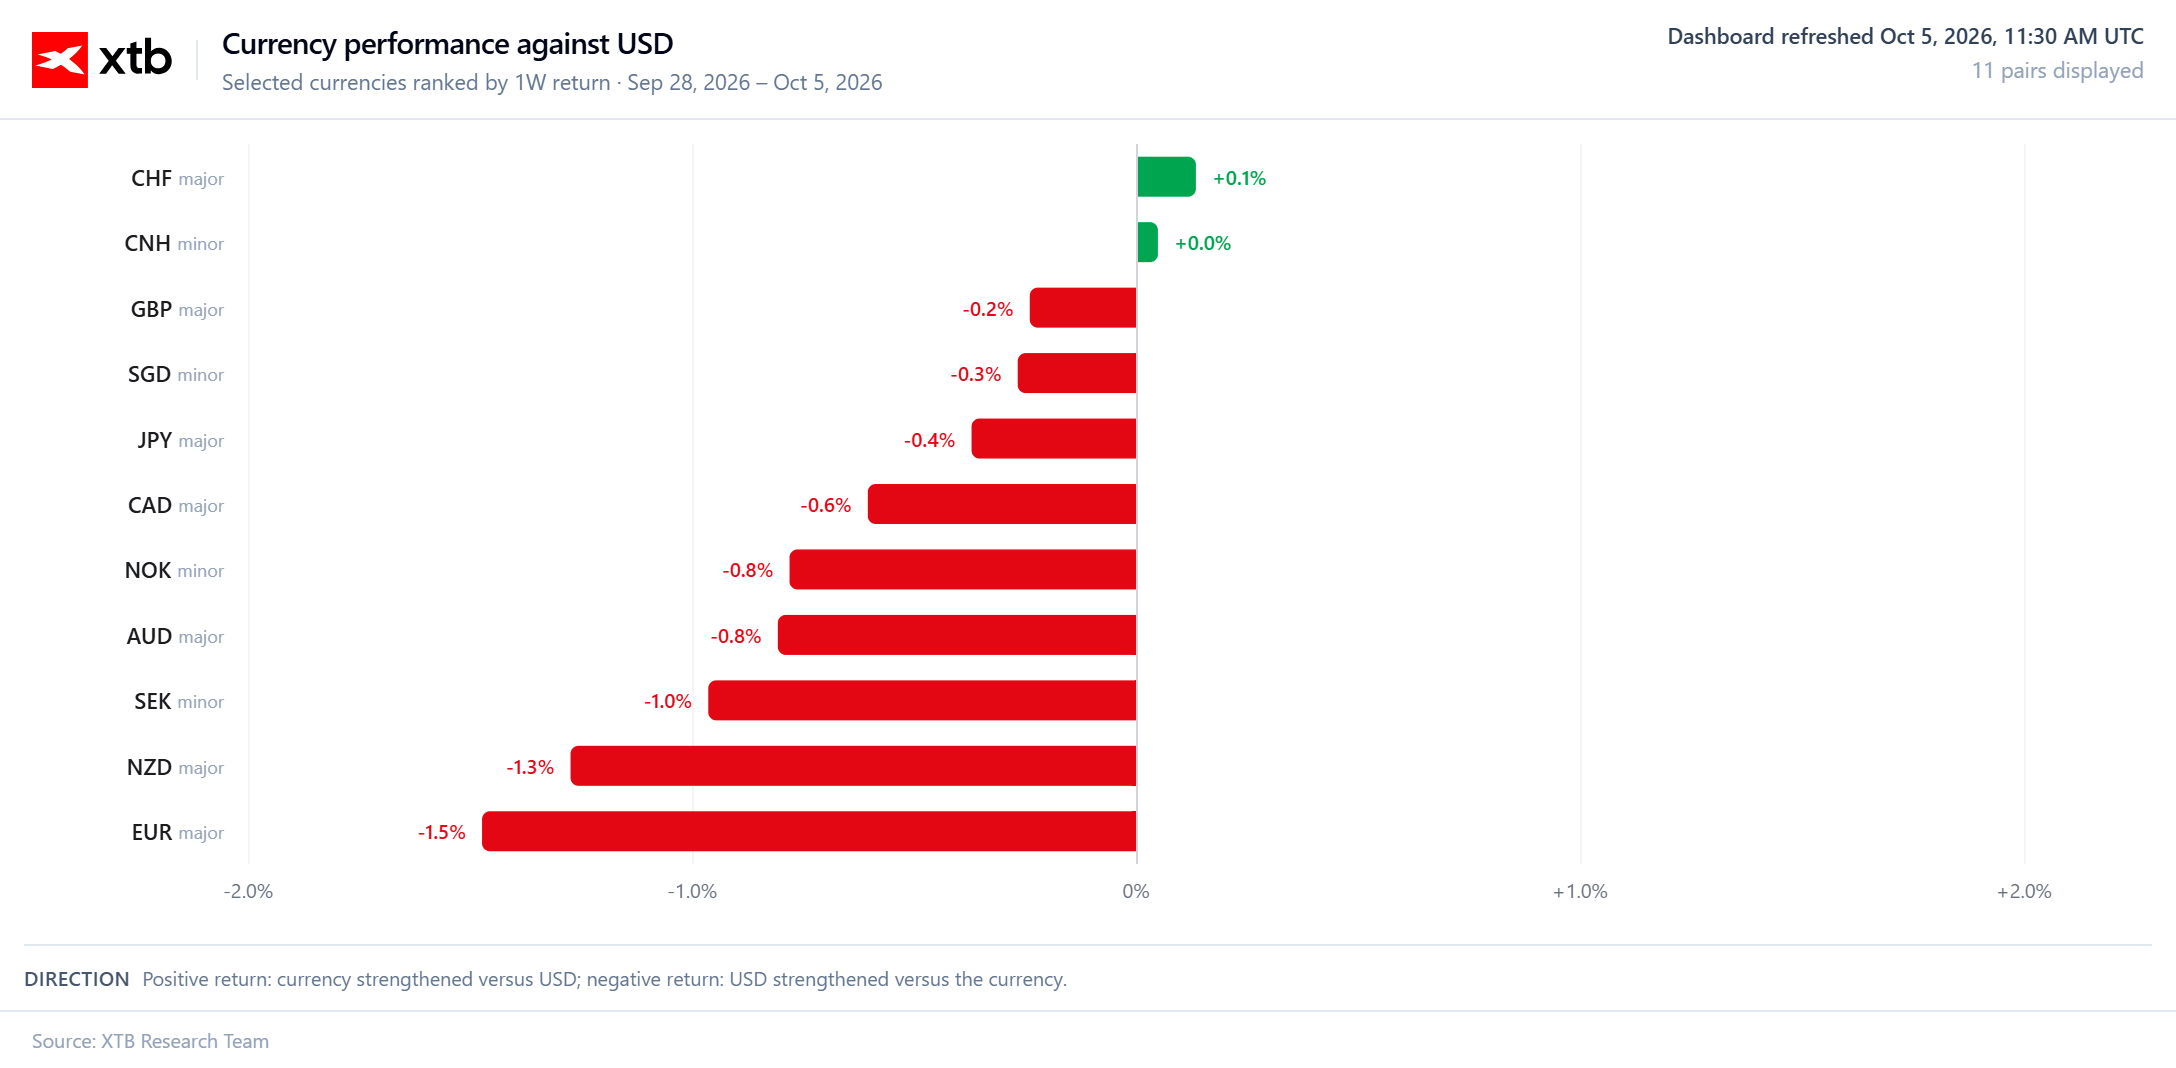
The euro hit a multi-month low, impacted among other factors by political and fiscal pressure in France.
Commodities and Energy 🛢️
-
Middle East oil exports returned to pre-war levels—at times reaching 19.5–22.5 million barrels per day in the last week of September, with a 7-day average of 18.5 million barrels per day.
-
The supply increase stems mainly from larger shipments from Saudi Arabia and the recovery of Iraqi exports through the Strait of Hormuz, helping ease market tensions, particularly in Asia.
-
LNG exports through the Strait of Hormuz in September rose to their highest level since February.
-
The situation in Hormuz remains tense—at least seven attacks on tankers were reported in the last week.
-
Positive sentiment prevails in the precious metals market: gold futures are gaining about 0.5%, holding near $4,150 per ounce, while silver rises by over 2.5%, approaching $62 per ounce.
Cryptoassets 🪙
-
Gains are also visible in the cryptocurrency market: Bitcoin is up about 0.2%, hovering around $86,000, while Ethereum gains 0.5%, breaking above $2,700.

Schneider Electric pays a high price for AI and software growth


💶Chart of the Day: EURUSD at Lowest Since May 2025 Amid French Fiscal Crisis

Economic Calendar - Key Services PMIs for Europe and the US, and Central Bankers' Decisions
Morning Briefing: Dollar gains, oil falls. EURUSD at multi-month lows