


Bears are gaining the upper hand across equity markets, with the sell-off on Wall Street setting the tone for the session. Dow Jones futures (US30) are down about 1%, while the S&P 500 (US500) is sliding around 0.5%. Tech stocks have become the main epicenter of the sell-off following warnings from Apple. The tech giant flagged shrinking margins driven by rising memory component costs and supply bottlenecks for new devices, immediately dragging down the broader semiconductor sector. Sentiment in Europe remains mixed, but the flight from risk on US election day weighed heavily on emerging markets, with Warsaw’s WIG20 dropping roughly 1.3%, noticeably underperforming major Western European bourses.
Midterms, Central Banks, and Escalation in the Gulf
Financial markets are navigating heightened volatility ahead of the outcome of the US midterm congressional elections, pushing the VIX volatility index up by over 1.5%. Although market consensus leans toward Democrats taking control, investors are mindful of the historical undercounting of Republican support in polls, keeping trading cautious ahead of official results.
At the same time, investors are digesting signals from central banks. The Reserve Bank of Australia (RBA) hiked interest rates to 4.85%, but the dovish tone of the accompanying statement was perceived by the market as a "dovish hike," signaling the end of the tightening cycle. In Europe, SNB Chairman Martin Schlegel pointed to moderate Swiss GDP growth and a slight uptick in inflationary pressures, while the ECB's Moulin warned against inflation spilling beyond the energy sector.
Commodities in Brief
- Crude oil jumps: Brent (OIL) and WTI (OIL.WTI) crude are rallying over 2% in response to US strikes near the Strait of Hormuz and the looming risk of supply disruptions.
- Precious metals correction: Gold is down about 1%, retreating toward $3,900/oz, while silver drops nearly 3.5%, extending a sharp sell-off after breaching key technical trendlines.
- Industrial metals under pressure: Copper (down nearly 3%) and aluminum (sliding around 2%) face heavy selling pressure amid global economic growth concerns and mixed sentiment in China.
- Natural gas gains: European gas (NATGAS.EU) is up roughly 3% following the initial capacity auctions in Germany and ongoing supply constraints.
Currencies: China Intervenes and AUD Weakens
Major currency pairs are locked in tight consolidation; EUR/USD and GBP/USD are awaiting catalysts from US ballot boxes, though analysts continue to see upside potential for the dollar over a three-month horizon. The Polish zloty remains relatively stable, with USD/PLN hovering near 3.955.
In Asian markets, the People's Bank of China raised foreign exchange reserve requirements for commercial banks to curb the rapid appreciation of the yuan. Meanwhile, the Australian dollar (AUD) remains under notable selling pressure, as weakness following the RBA's dovish hike is compounded by today's slide in copper and aluminum prices, dealing a double blow to the commodity-linked currency.
European Equities
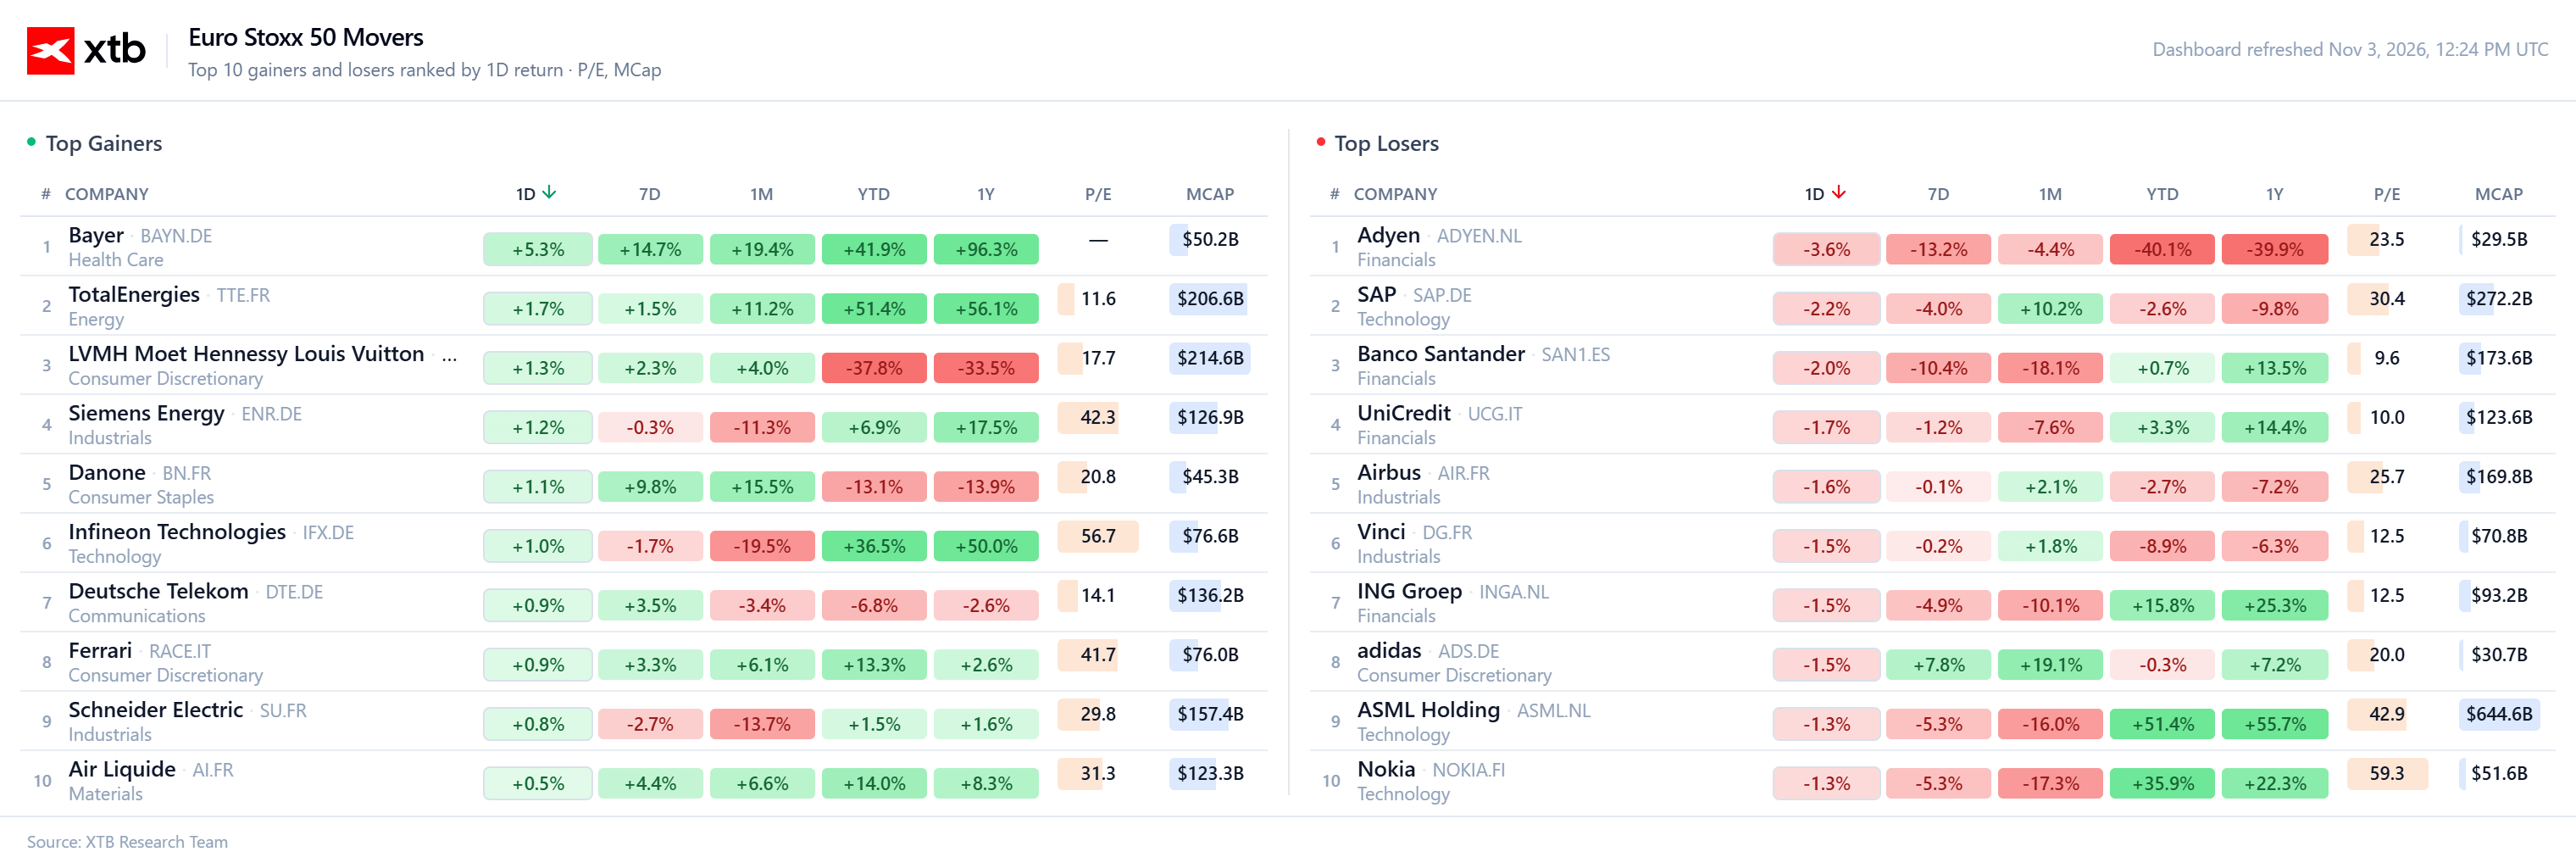
- Bayer (BAYN.DE) (up nearly 5%): Delivered an upbeat Q3 report. Group adjusted EBITDA climbed 6.9% YoY to €1.62B, handily topping market estimates. The rebound was spearheaded by the Pharmaceuticals division, where full-year EBITDA margin guidance was lifted to 25–27% (from 23–25%), enabling management to also raise full-year group EBITDA guidance to €9.8–10.3B.
- TotalEnergies (TTE.FR) (gaining over 1.5%): Benefiting from the oil price rally following US strikes on Iranian infrastructure near the Strait of Hormuz, which directly lifted upstream sector valuations.
- Siemens Energy (SIE.DE) & Schneider Electric (SDR.UK) (gains between 1% and 2%): A strong session for capital goods and industrial equipment makers. The sector is supported by robust order intake for grid modernization and power transmission upgrades, proving resilient to turbulence hitting pure-play Big Tech.
- SAP (SAP.DE) (down over 2%): The German enterprise software heavyweight is sliding in step with a broader rotation out of tech. Selling is fueled by margin concerns across Wall Street tech giants (notably Apple) and Palantir’s cautious sales outlook, signaling cooling enterprise software demand.
- Adyen (ADYEN.NL) (sliding over 3%): The Dutch fintech is seeing steeper losses amid an ongoing pullback from growth names and fintech stocks against a backdrop of slowing consumer spending.
- Ferrari (RACE.IT) (down nearly 3%): Reaction to Q3 earnings. While net profit beat expectations, investors viewed the raised full-year guidance as overly conservative—merely matching existing consensus estimates.

AMD Preview: Can the Company Reignite AI Optimism?

Pfizer Reports Earnings 📈 Shares Near Multi-Year Highs

Gold loses almost 1% 📉


Chart of the Day: Nasdaq 100 Slips Into Correction 📉 AI Rally Loses Steam - What’s Next for US100? (03.11.2026)