


- Markets were partly reassured by Kevin Warsh’s message, as the Fed Chair stressed the central bank’s determination to bring inflation under control. Investors interpreted this as a sign that policymakers want to regain control over price pressures, even at the cost of keeping monetary policy restrictive.
- The bond market is seeing a modest recovery. The U.S. 2-year Treasury yield fell by 2 bps to 4.71% after reaching its highest level since 2024 in the previous session, while 10-year and 30-year yields are also down by around 2 bps.
- Investor attention is now shifting to the Bank of England and the Bank of Japan. The BoE is due to announce its decision today and is expected to leave rates unchanged, while the BoJ is expected to raise rates by 25 bps on Friday.
- Today’s key macro releases include final Eurozone CPI data at 9 AM GMT, U.S. jobless claims at 12:30 PM GMT, and secondary U.S. housing-market data.
- European indices are pointing to a higher open, while broader Asian equity markets are up around 0.3%, recovering part of their earlier losses following the Fed decision.
- Gold is rebounding after three consecutive losing sessions and has returned to around $4,290 per ounce, supported by a modest pullback in bond yields.
- Oil remains under pressure as signs gradually emerge that supply risks in the Middle East may be easing, while Saudi Aramco has pledged to restore around 50% of the East-West pipeline’s transmission capacity within a few days. Brent is trading near $105 per barrel after falling as much as 5% on Wednesday.
- Saudi Arabia is seeking to restore around half of the East-West pipeline’s capacity following earlier drone attacks, easing some concerns over further supply disruptions.
- Donald Trump said the war with Iran would end “very soon,” further supporting expectations for a decline in the geopolitical risk premium embedded in oil prices. He also said U.S. interest rates should fall to 1% and that the Fed should move quickly.
- The U.S. President warned against Canada joining the European Union and threatened to completely halt trade with Europe if such a scenario were to materialize.
- Exxon Mobil is reportedly close to signing a preliminary agreement that could allow the company to return to Venezuela, according to sources cited by the WSJ. Exxon and state-owned PDVSA are said to be nearing a memorandum covering oil fields with estimated reserves of around 50 billion barrels.
- The Trump administration is considering organizing a high-level meeting focused on artificial intelligence on the sidelines of Chinese President Xi Jinping’s visit next week.
US500 and OIL charts (D1 timeframe)
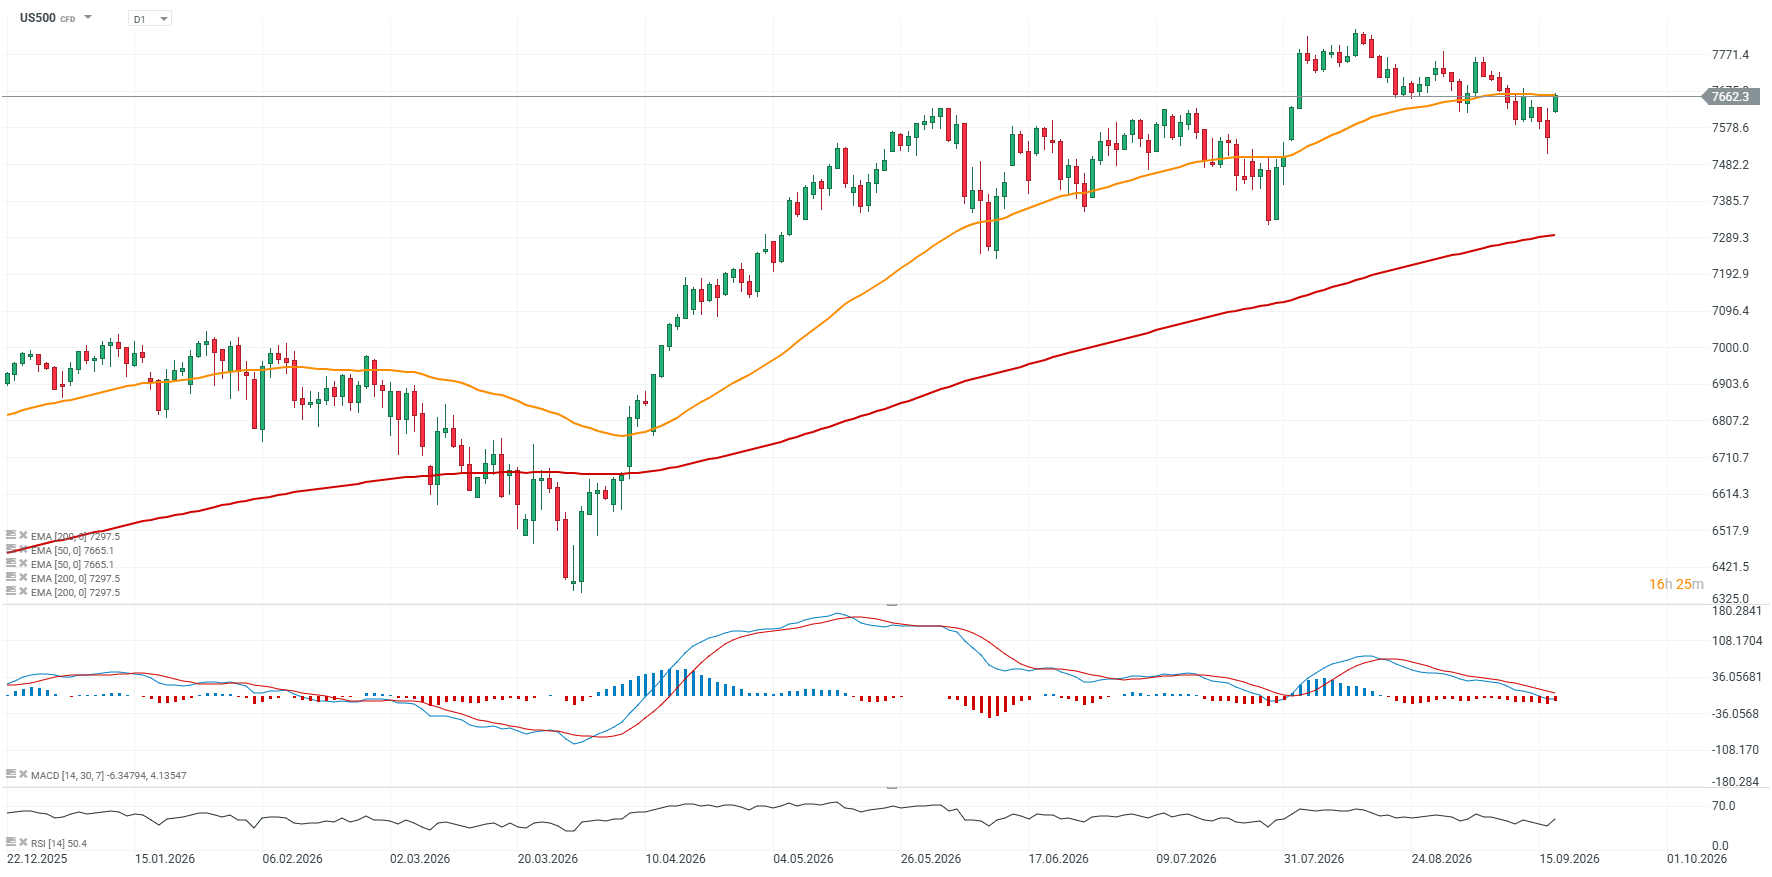
Source: XTB
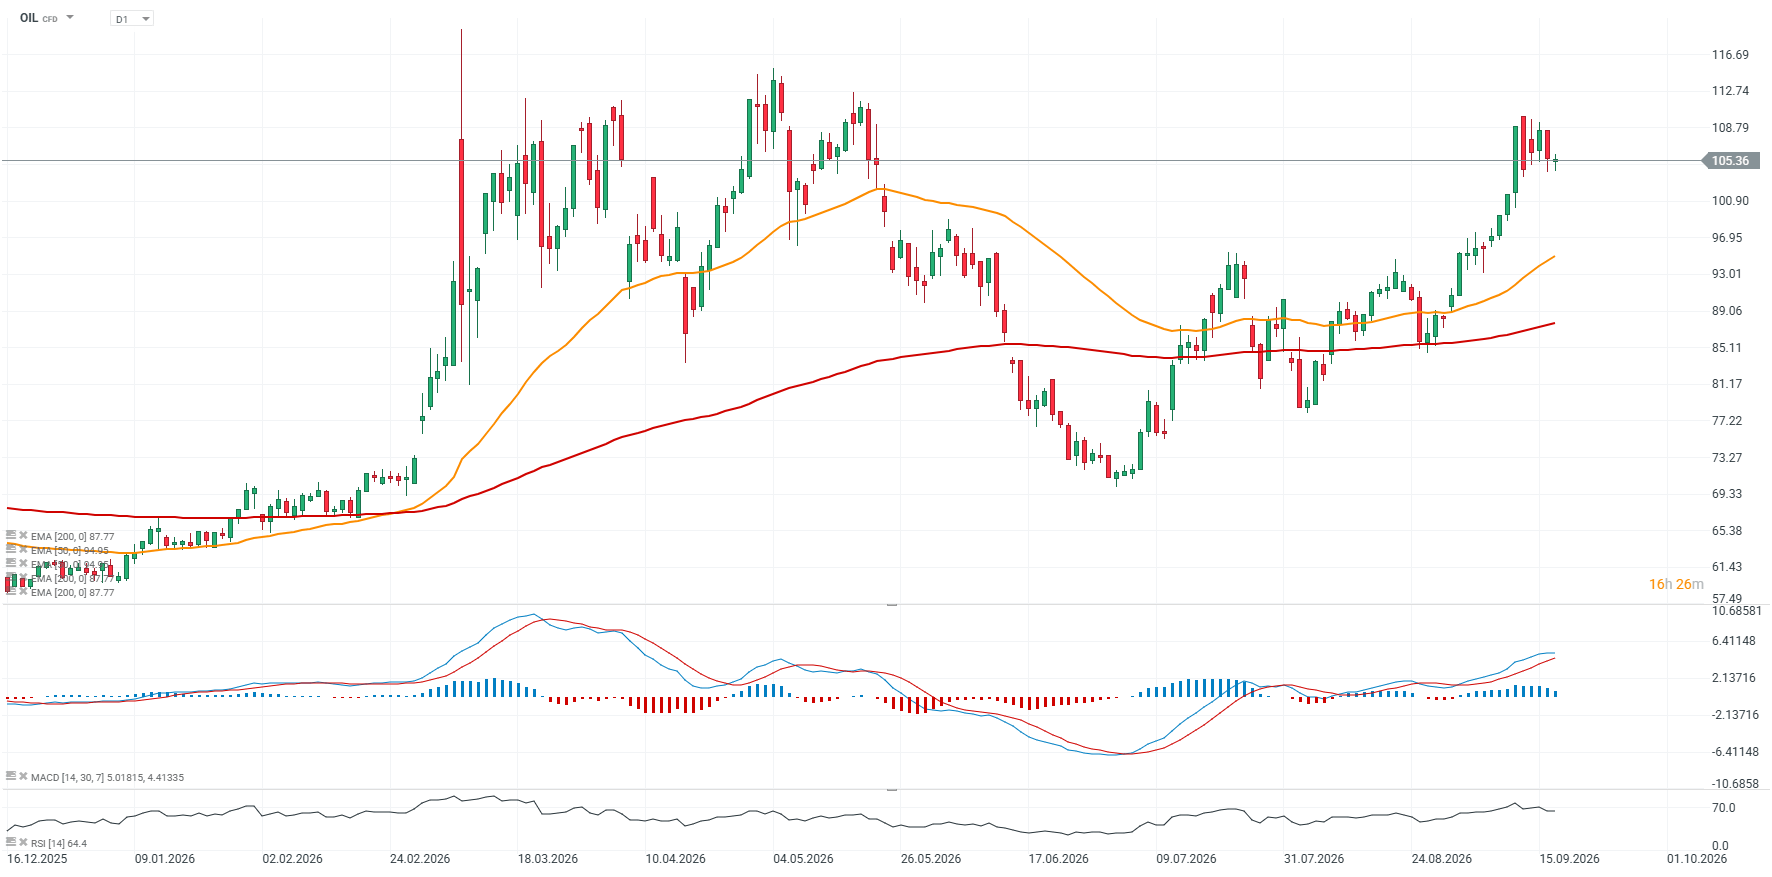
Source: XTB



📊Daily Summary - Hawkish Fed raises rates and signals more. Dollar gains while gold falls


Hawkish move from the Fed! Warsh takes no prisoners in the fight against inflation. US500 at its lowest since August 3, and gold already below $4,300.

⬇️EURUSD below 1.15 following hawkish Fed
BREAKING: Fed’s Hawkish Hike Triggers Market Reversal: USD Soars as Gold and US500 Retreat