


Tensions in the Strait of Hormuz are escalating rapidly—the Singapore-registered container ship GFS Pride sank after being struck by an unidentified projectile, and a second vessel (the GFS Giselle) sustained hull damage. Singapore’s maritime authorities called the attacks “unjustified and in violation of international law.” Iran is escalating its rhetoric—IRGC commander Ali Ozmaei reportedly stated that Tehran is “counting down the moments” until it can sink U.S. warships.
The U.S. maintains that it controls the strait — CENTCOM responded that “U.S. forces and regional partners clearly control the Strait of Hormuz.” Additionally, the IRGC reportedly ordered the evacuation of military bases amid growing fears of a U.S. attack, suggesting that the escalation could accelerate. Meanwhile, Houthi attacks on Saudi Aramco facilities continue in the background, driving up the risk premium in the oil market.
On the Russia–Ukraine front, a dispute has arisen over Starlink—Ukraine accused SpaceX of imposing speed limits on active terminals without warning, which disrupted drone operations. Elon Musk responded that the Starshield systems are owned by the U.S. government and that any restrictions are “ultimately up to the president.” Some of the restrictions have already been partially lifted, but Kyiv is demanding that the limits be completely removed. Tensions are also mounting over the “energy ceasefire” announced by Trump, which Zelenskyy accuses Russia of violating.
The main economic development remains the hotter-than-expected U.S. CPI for September—core inflation rose to 2.6% y/y (forecast: 2.5%), while the headline index rose to 3.7% y/y, driven by a 5.2% jump in the energy index. This is a direct result of high fuel prices linked to the war with Iran—gasoline costs an average of $4.33 per gallon, compared to $3.08 a year ago. The data has fueled concerns that the Fed may tighten monetary policy later this year.
The reaction in the bond market, however, is counterintuitive—despite the hot CPI reading, bond yields initially spiked, only to quickly give up all those gains and continue falling. The yield on the 10-year U.S. Treasury note fell to about 5.10%, its lowest level in three weeks (more than 20 basis points below its post-CPI peak). The simplest interpretation: the AI-driven sell-off is pushing down growth expectations, and bonds are once again serving as a hedge against stocks. The market is pricing in about a 29% chance of a Fed rate hike in October (up from 22%), but sees about a 75% probability that rates will remain unchanged.
The Fed’s rhetoric remains hawkish, but it is in no rush — Mary Daly (SF Fed) said that further rate hikes are “more likely than not,” but she sees no need for action in October. Goolsbee called the CPI reading “disheartening,” and the Beige Book pointed to diesel-driven price pressures. Citi has already pushed back its expectations for a December rate hike. Today, market attention will focus on speeches by Fed officials in Bangkok, including Fed Chairman Kevin Warsh.
Wall Street posted its third consecutive day of losses—the S&P 500 fell 1.11% (to 7,718.94), the Nasdaq Composite dropped 1.88% (its worst day since July 23), and the SOX semiconductor index extended its decline for the sixth straight day. The Dow was relatively strong, losing only 0.09%. AI companies sensitive to financing costs—Oracle, CoreWeave, and Nvidia—were under the most pressure.
The market’s problem, however, may run deeper than inflation—beneath the surface of the index, market breadth is clearly collapsing. Only about 18% of S&P 500 companies are trading above their 50-session moving average, and about 27% are above their 200-session moving average, meaning that more than 80% of stocks are trading below their short-term trend. Additionally, the 52-week correlation between the equal-weighted and market-capitalization-weighted indices has fallen to about 0.67—the lowest on record (for nearly 15 years before the pandemic, it remained in the range of 0.95–0.99). This is a sign that the index is being propped up by mega-cap companies, masking the weakness of the rest of the market.
Asia saw a veritable bloodbath in the tech sector—South Korea’s KOSPI plummeted nearly 8%, and the KOSDAQ fell 8%, triggering a 20-minute trading halt. Japan’s Nikkei 225 fell by as much as over 5% during the session (to about 64,300 points), though the broader Topix index saw a milder decline (–2.5%). The sell-off was an echo of the declines on Wall Street, exacerbated by concerns about funding for AI investments.
The epicenter of the sell-off is the memory and chip equipment sector—SK Hynix and Kioxia plummeted by more than 11%, Samsung Electronics fell by about 9.3%, and Japan’s Advantest crashed by nearly 14%. SoftBank (the main investor in OpenAI) lost about 9.4%, and Tokyo Electron lost more than 7%. Sentiment is being weighed down by concerns about a memory oversupply starting as early as 2029, as well as a breakthrough by China’s CXMT in 4F² architecture, which signals intensifying competition—Musk added that China will be producing “LOTS of RAM in 2028.”
Credit stress surrounding AI is also mounting—the cost of credit default swaps for tech companies is hitting record highs. Oracle’s 5-year CDS spreads widened by 26 basis points to a record 288 basis points, SoftBank’s to 424 basis points, and CoreWeave’s shot up above 1,000 basis points—levels typically associated with distressed debt. This shows that the market is increasingly questioning not the demand for AI, but the cost of financing its expansion.
A weaker dollar is dominating the foreign exchange market—the dollar index is retreating after reaching an 18-month high, a result of falling yields. The euro strengthened by about 0.6% to 1.1225, while the yen gained ground—the USD/JPY fell by 0.4% to about 157.7. The yen is further supported by the BOJ’s hawkish rhetoric—Junko Koeda stated that the bank “should not be overly cautious” regarding rate hikes, estimating the neutral rate to be well above 1% compared to the current 1.25%.
The Australian dollar is an exception among currencies—the AUD weakened following disappointing labor market data. Employment fell by 39,300 jobs in September (forecast: +20,000), and the unemployment rate remained at a 5-year high of 4.7%. The market has scaled back the probability of an RBA rate hike in November to about 15% (from nearly 50% at the beginning of the month), pushing AUD/USD down to around 0.6956.
On the commodities market, oil prices are falling despite geopolitical tensions—Brent lost about 1.7% to around $104.2, while WTI fell to about $94 per barrel. The reason is a Reuters report that the Trump administration is considering easing sanctions on the “shadow fleet” to lower record-high freight rates and increase oil flows from the Gulf. High fuel prices pose a political risk ahead of the November special elections.
In its October report, the IEA warns that diesel market constraints could persist well into next year, and new attacks on Saudi Arabia threaten to derail the recovery of supply. Analysts point out that the lack of progress in U.S.-Iran negotiations “leaves little chance for the strait to fully reopen,” but Saudi oil is still reaching customers via alternative routes, and the release of IEA reserves is cushioning prices.
Gold is rebounding from its weekly low—the precious metal gained about 1% to approximately $4,146 per ounce, driven by a weaker dollar and falling yields, which reduce the cost of holding a non-interest-bearing asset. Support is also coming from a Bloomberg report suggesting that China may hold more U.S. debt than official data indicates (it is suspected that some of it is routed through Canada, whose holdings have risen to nearly $600 billion). Silver rose 0.7% to about $56, while platinum and palladium also gained ground.
Among individual companies, several stories stand out—Anthropic (the creator of Claude), ahead of its November IPO, reported Q3 revenue of $16.8 billion (up from $11.6 billion in Q2 and $4.7 billion in Q1), adjusted profitability, and positive cash flow. Investors expect the company to reach $110 billion in annual revenue by the end of the year. Barclays noted that an announcement of a merger between Tesla and SpaceX could come as early as December.
In other companies — Netflix announced it would lay off about 6% of its workforce (approximately 1,000 people), mainly from the product, technology, legal, and HR departments. OpenAI is facing lawsuits from eight U.S. states alleging that ChatGPT harms children and misleads parents. Rocket Lab postponed the debut of its Neutron rocket to 2027 (shares down 7% after the close), while CoreWeave fell more than 15% on concerns about excessive debt related to AI.
The cryptocurrency market is experiencing a sell-off in the wake of risk-off sentiment—Bitcoin briefly fell below $81,000, and positions worth approximately $485 million were liquidated. It is currently trading around $80,900 (–0.8%), succumbing to the general flight from risk triggered by concerns over interest rates and AI.
What to expect from today’s trading session—the key will be this afternoon’s U.S. data: September’s PPI, retail sales, and weekly jobless claims (at 2:30 p.m. our time), which could further tip the balance of expectations regarding the Fed. The market will also be watching speeches by Fed officials in Bangkok, including Fed Chairman Kevin Warsh, as well as TSMC’s earnings (expected to mark a sixth consecutive record quarter, with net income up 65% to approximately $23.4 billion; conference call at 8:00 a.m. our time). Regional banks—U.S. Bancorp, PNC, and Charles Schwab—are also reporting earnings this season. In the background, it will be worth watching whether the Asian tech sell-off spills over into the European open and whether a further decline in yields will ease pressure on the stock markets.
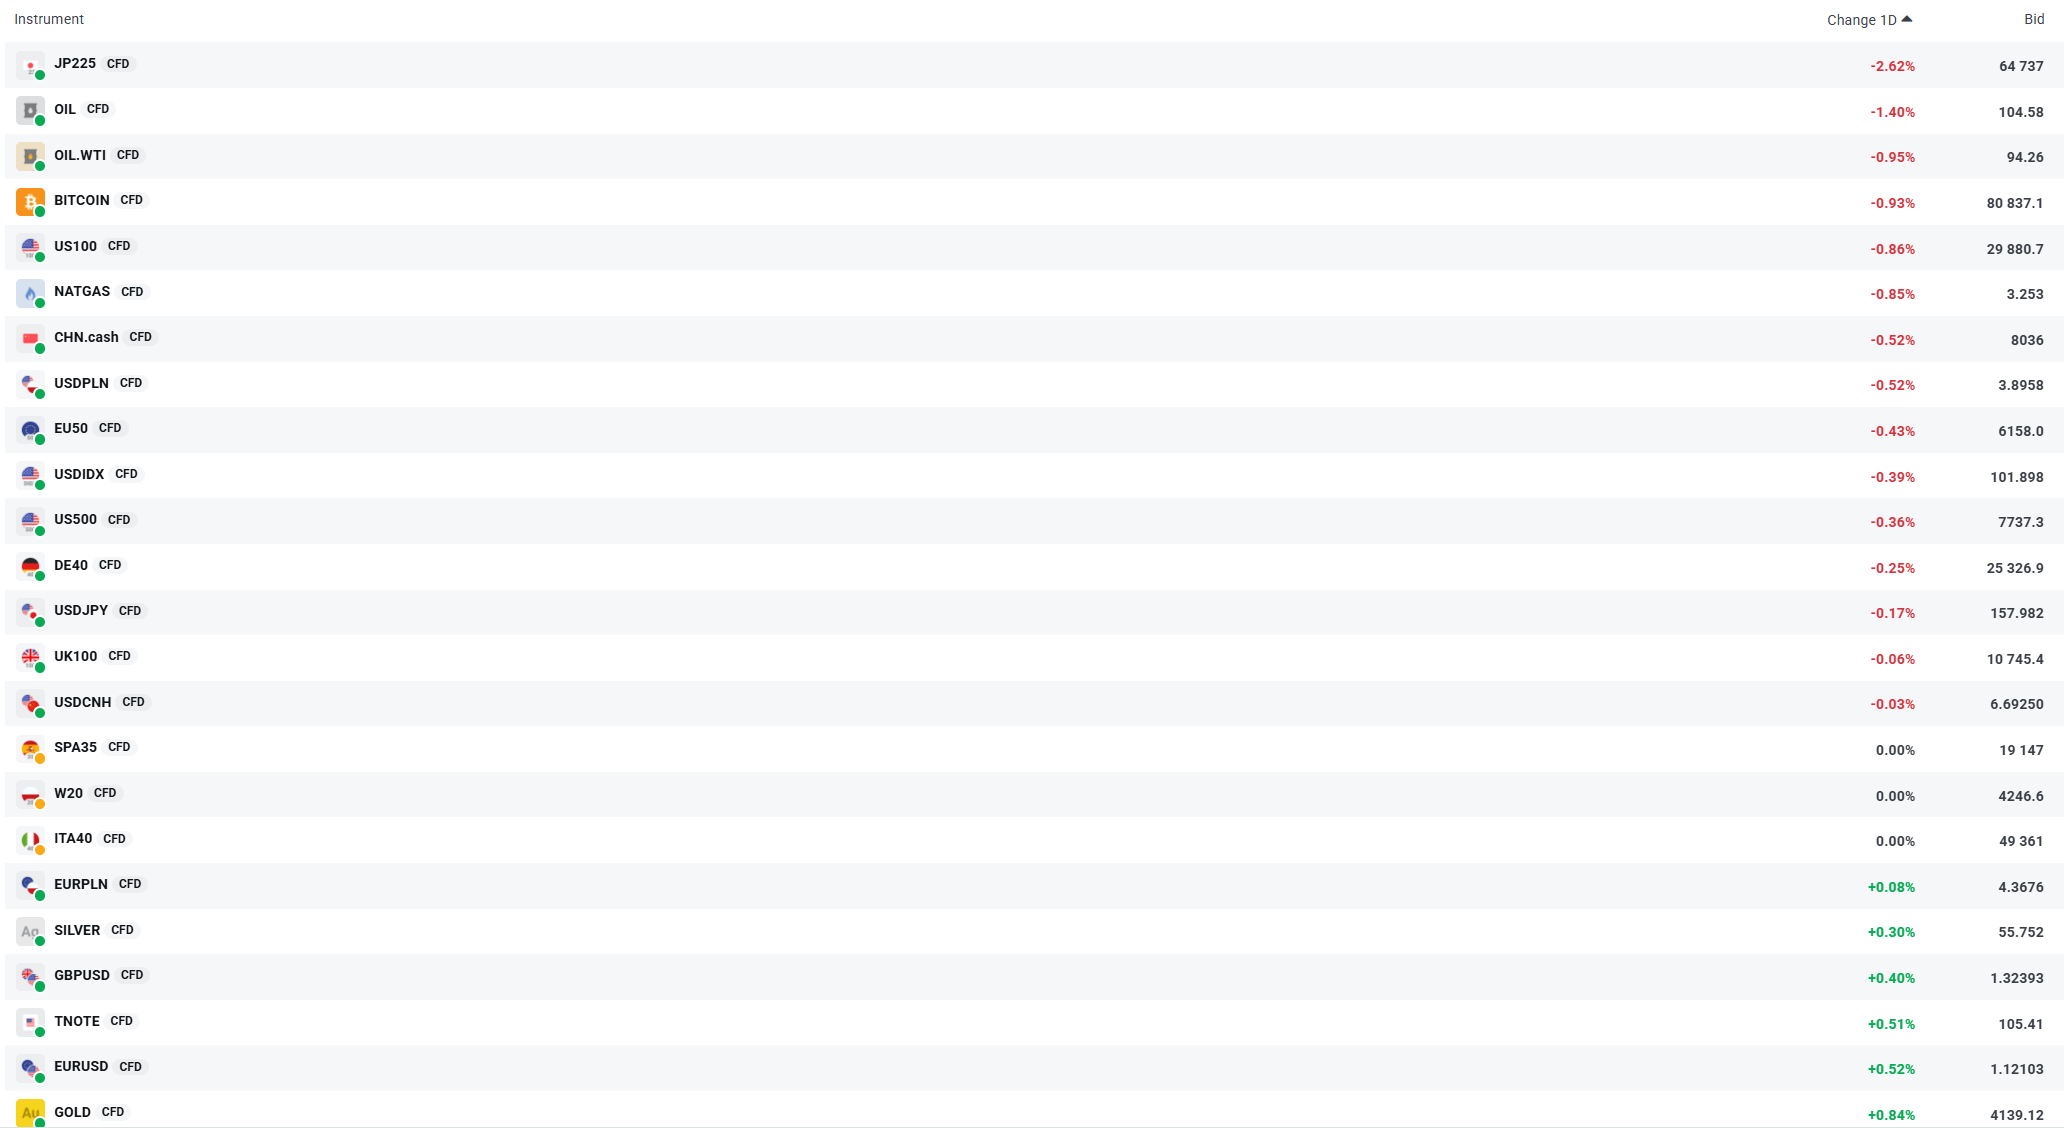
Key markets this morning. Futures on U.S. and Japanese indices are down sharply. The dollar is following suit. On the other hand, gold (GOLD) is gaining ground, with prices rising by more than 0.8%. Source: xStation



Daily Summary: Rising inflation weighs on markets, semiconductors suffer most (14.10.2026)


US Open: CPI reading weighs on American indices (14.10.2026)
US inflation concerns rise


POET: A “meme stock” in photonics, is there still hope?