


Global equities remain close to record highs, despite pressure from elevated commodity prices and very high bond yields. Yesterday’s gains on Wall Street were once again led by the technology sector: the Nasdaq 100 closed at a record high, while advances in Nvidia and Microsoft brought the S&P 500 to within less than 0.5% of its all-time peak.
- Sentiment in Asia also remains relatively positive, although the scale of the move is modest. The MSCI Asia-Pacific index gained around 0.1% and remains roughly 2% below its record high, while the MSCI All Country World Index is less than 1.5% below its August peak. Equity futures in Europe and the US point to an attempt to extend the gains.
- The bond market remains the main source of pressure on risk-asset valuations. The US 10-year Treasury yield rose to around 5.32%, a level not seen since 2002, while the 2-year yield approached 4.83%. Selling also spread to government bonds in Japan, Australia and New Zealand, highlighting the increasingly global nature of the pressure in fixed-income markets.
- Gold is edging lower, while oil is attempting to recover some of its recent losses. Gold slipped by around 0.4% to approximately $4,120 per ounce, while Brent crude rose by 0.6% to around $100.9 per barrel. Elevated oil prices remain an important inflationary factor, potentially reinforcing expectations for restrictive monetary policy and limiting the scope for a decline in bond yields.
- The euro remains under pressure and is trading close to 17-month lows. The single currency is being weighed down by a combination of rising borrowing costs and a deteriorating fiscal outlook in France, which is increasing the risk premium attached to European assets.
- France remains one of the main areas of focus in Europe. Marine Le Pen and her party are expected to present alternative budget proposals and a plan to reduce the deficit, which could have implications for the French bond market, the euro and broader sentiment toward euro-area assets.
- With the macroeconomic calendar relatively light, markets are likely to look for a new catalyst. In the near term, further moves in bond yields, oil prices and developments around France’s fiscal position may prove decisive in determining whether equity indices can remain close to record highs or whether elevated funding costs begin to weigh more heavily on valuations.
- Samsung Electronics is down nearly 2%, while SK Hynix is falling close to 3.5%, clearly underperforming the broader semiconductor sector. Investors remain cautious ahead of third-quarter earnings, with concerns focused on the strength of the Korean won, rising costs, a possible slowdown in AI-related chip demand, and delays to some data-center projects in the US.
- At the same time, earnings expectations remain high. Samsung is set to release preliminary results later this week, while SK Hynix is due to report later in October. Strong results from Micron have also supported sentiment toward the sector, suggesting that demand for memory chips and AI-related components remained robust at least through the end of September.
- Donald Trump commented yesterday on reports of a possible US military presence in Central and Eastern Europe, saying he would “look into” the issue of a base in Lithuania, while adding that a US base in Poland “could happen.” He also said that diesel-market problems were partly linked to attacks on Russian refineries and suggested that tensions involving the UK would be brought under control. Trump further indicated that Iran may have been responsible for the FlyDubai aircraft incident and warned that Tehran would face a very strong response if it had combat drones operating in the UK.
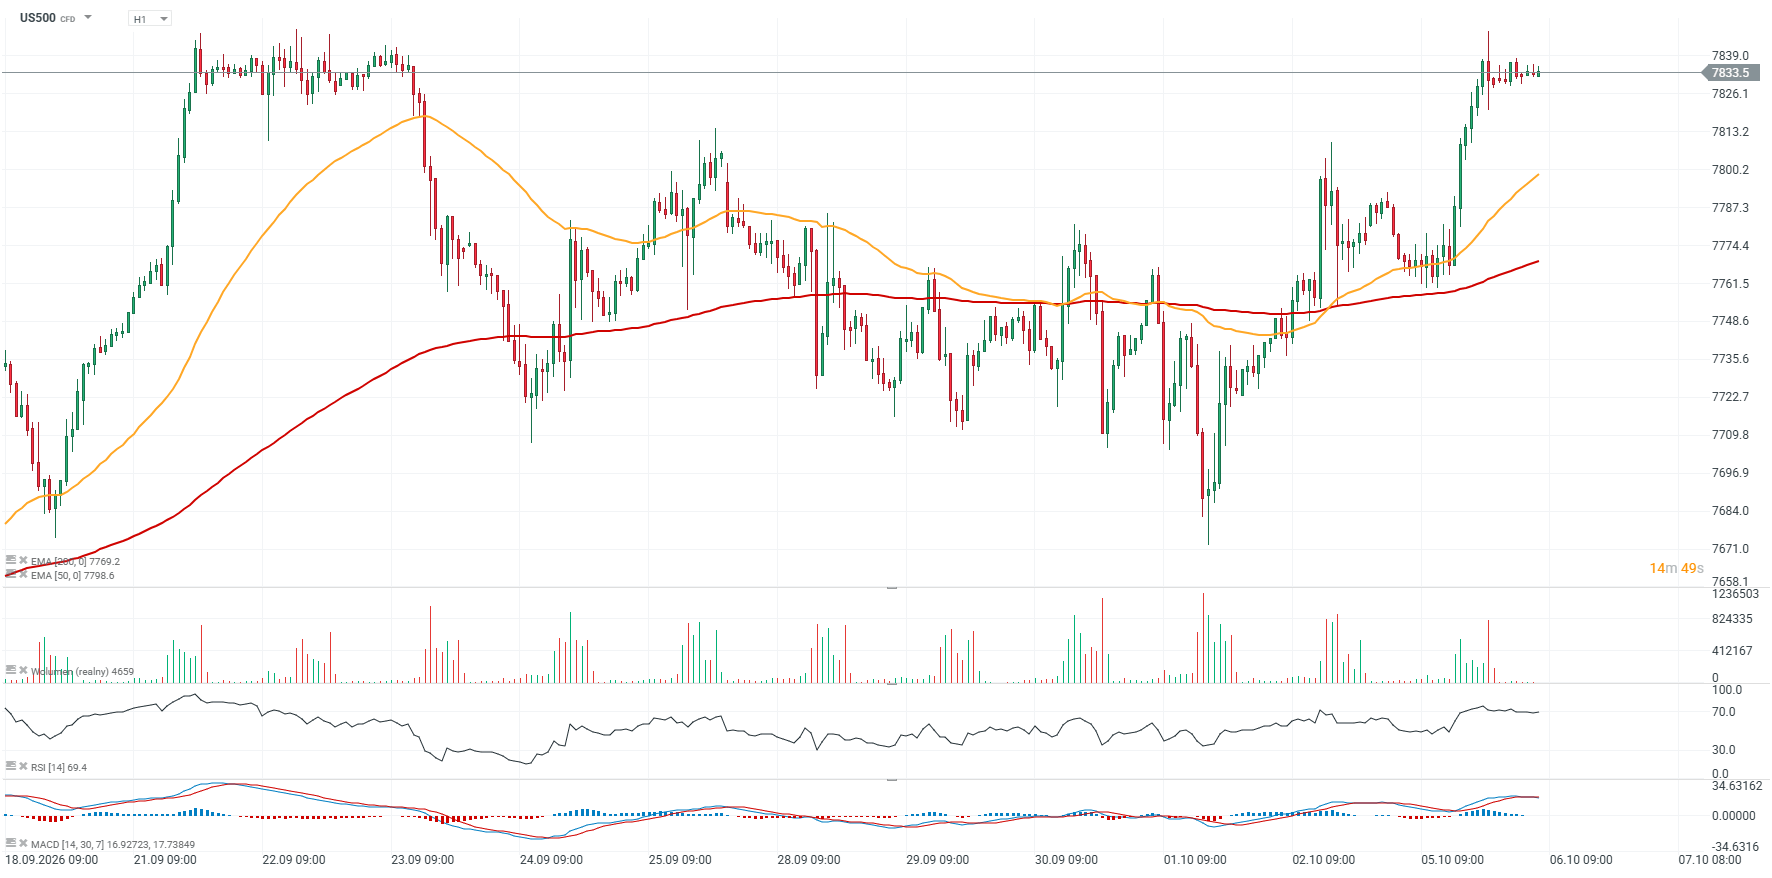
US500 (D1 interval)
The US500 contract matched yesterday the record high set on September 22, while bullish momentum remains intact with the RSI still relatively elevated and close to 70. The nearest support appears to be located around 7,800 points, where the 50-day EMA (orange line) converges with price reactions seen in the final week of September and early October. Key resistance levels are located around 7,850 and 8,000 points.
 Source: xStation5
Economic Calendar: Retail Sales and Fed Speakers in Focus (06.10.2026)

BREAKING 🚩 Sharp Drop in German Industrial Production
BREAKING: U.S. ISM PMI for services comes in below expectations🚨


Intel declines: Share in "Terra Fab" threaten?