


For the 6th time in the past 7 releases the weekly crude oil inventories have come in higher than the consensus forecast, however the adverse reaction in the oil markets has been fairly small. The breakdown of the data was as follows:
-
Weekly crude oil inventories: +5.7M vs +0.5M exp. API: +1.7M
-
Gasoline: -3.0M vs -2.3m exp. API: -4.7M
-
Distillates: -1.0M vs -2.4M exp. API: -1.6M
-
Production: 12.6M bpd - unchanged.
The headline beat both the expected as well as the API, although the gasoline and distillates components were more mixed. On the whole it does seem to be a negative release for crude prices but after an initial dip both Oil and Oil.WTI have recovered somewhat.
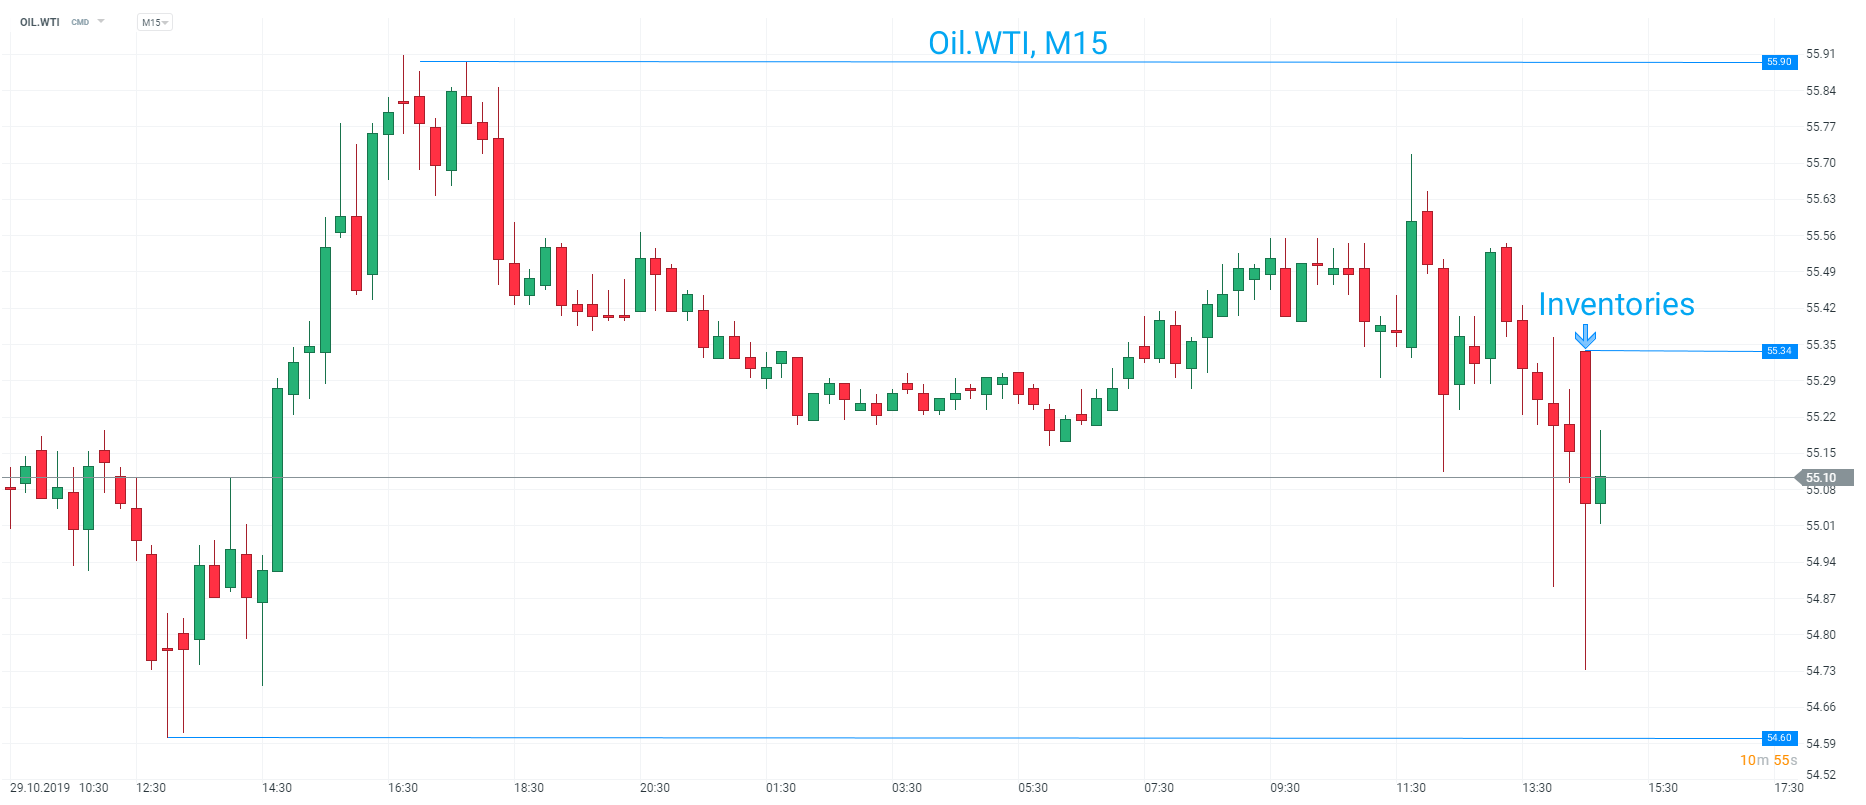
Oil.WTI fell sharply as the data dropped and declined by as much as 60 ticks. However, there has been a lack of follow through so far and the market is looking to regain its footing. Source: xStation
 The bigger picture for the market is also far from clear at the moment with price in between the 8 and 21 EMAs that are showing no clear trend. Near term support could be found around 54.60 while recent highs at 56.95 need to be broken for a sustained move higher. Source: xStation



📊Daily Summary: Tech sector drives Wall Street rebound, DAX leads in Europe

Chart of the day 🚩 Cocoa sell-off continues. Record ICE inventories and index rebalancing in focus (11.11.2026)


Daily summary: CPI reading hits markets, hawkish Fed and Wall Street selloff

Sharp retreat from gold. Higher US CPI opens the door to a 50 bps rate hike in the US