


From a fundamental point of view, DOE report released earlier today should be positive for oil prices. Inventories dropped by more than 3 million barrels, a week after a big almost-8 million barrel build. On the other hand, the overall level of inventories is in-line with 5-year average and inventories have increased by more than 40 million barrels year-to-date. On top of that, we are also observing a small increase in inventories of oil-derivative products. Decline in oil inventories has been partially driven by relatively low oil imports.
As one can see, DOE report looks to be positive for oil prices. However, we have also seen some hawkish moves from central banks - rate hikes from SNB, Norges Bank, Bank of England and CBRT. BoE surprised with a bigger-than-expected hike while Powell struck a somewhat more hawkish note during today's testimonies in US Congress than he did yesterday, hinting at two more rate hikes this year. In turn, we can observe strengthening of the US dollar which puts pressure on commodity prices. Not to mention that more hawkish central banks increase risk of recession.
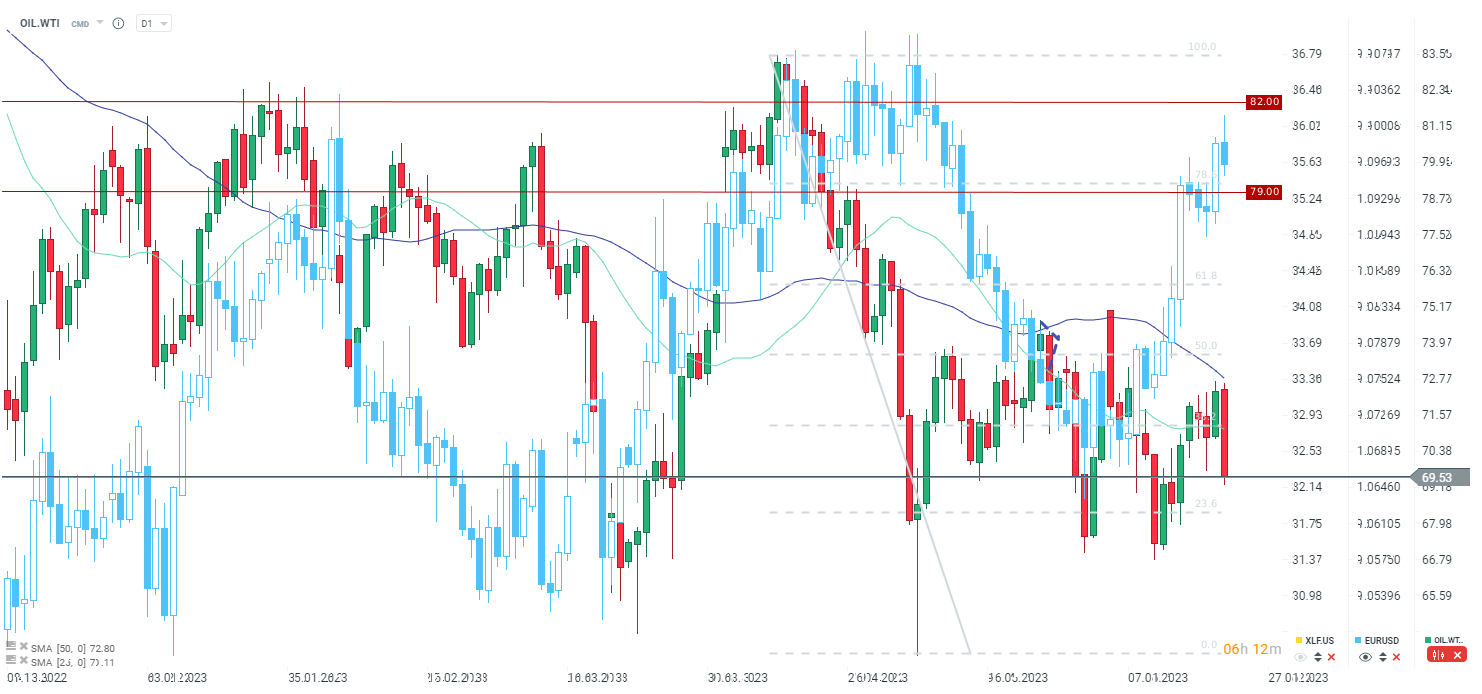 OIL.WTI is pulling back around 4% today in response to mixed DOE report and hawkish actions of central banks. Source: xStation5


Morning briefing: Trump-Xi in the shadow of geopolitical tensions (21.09.2026)

Cocoa falls as African harvests rise and ICE inventories approach a two-year high


Market warp: Rate Forecasts and Semiconductors in the Spotlight

📈 Gold gains 1% and erases post-Fed losses. Are metals returning to growth