


News about the resumption of peace negotiations between Iran and the US, along with the initially positive impression from Anthropic’s filing outline, is supporting an upward corrective move across the broader market. The leader is the technology index, with futures (US100) up about 0.7%. Small-cap and industrial indices are lagging, but still rising by 0.3% to 0.5%.
- On Monday, Anthropic filed for an initial public offering, seeking to list on Nasdaq under the symbol ANT. The IPO could raise $100 billion or more and value the company at $1.5 trillion to $2 trillion, according to a report. Anthropic reported revenue of $16.3 billion for the six months ended June 30, compared with $1.2 billion a year earlier. Net loss was $80.7 billion versus a $13 billion loss in the same period last year, according to the filing. About $72 billion of the latest loss reflected a non-cash accounting charge related to changes in the value of convertible notes and other financial instruments.
- AI infrastructure funding remains in focus. Meta plans to raise up to $95 billion through sales of common and preferred shares. The scale of the effort shows that the investment race is increasingly drawing on external capital, even among the most profitable platforms. According to Bloomberg, Meta’s capital expenditures are expected to reach about $140 billion, exceeding operating cash flow.
- Concerns are also visible in the credit market. The company’s five-year CDS spread has roughly doubled since August to 120 basis points.
- This week, earnings will include reports from Microsoft, Amazon, and Alphabet. These results will test both the momentum of demand for cloud services and the ability to monetize AI. So far, about 80% of S&P 500 companies reporting have beaten earnings expectations, but only 54% have exceeded revenue forecasts.
- A sharp selloff has hit US-listed companies linked to Brazil. Luiz Inacio Lula da Silva’s victory over market-favored Flavio Bolsonaro triggered a strong correction. The biggest losses are concentrated in financials: XP is down about 46%, Nu Holdings about 23%, and StoneCo about 35%. Pressure is also affecting mining groups and some consumer companies.
- In the oil market, declines dominate. Representatives of Saudi Arabia, Pakistan, and Turkey are set to meet with Iranian authorities as another attempt to ease tensions. At the same time, Donald Trump is signaling that a decision point is approaching between an agreement with Tehran and resuming attacks. Goldman Sachs warns that catching up on deferred refinery maintenance may limit supply and exports of refined products also in 2027. Oil prices are down about 1%, with Brent hovering around $110.
Company news:
- Meta (META.US): Shares recover early losses. The financing plan includes about $35 billion from selling common and preferred shares and up to $60 billion via a gradual sale of new Class C shares into the market. Nvidia, AMD, and Broadcom pledged to buy up to a combined $5 billion of common shares. Raising funds supports investment plans but also implies potential dilution for existing shareholders.
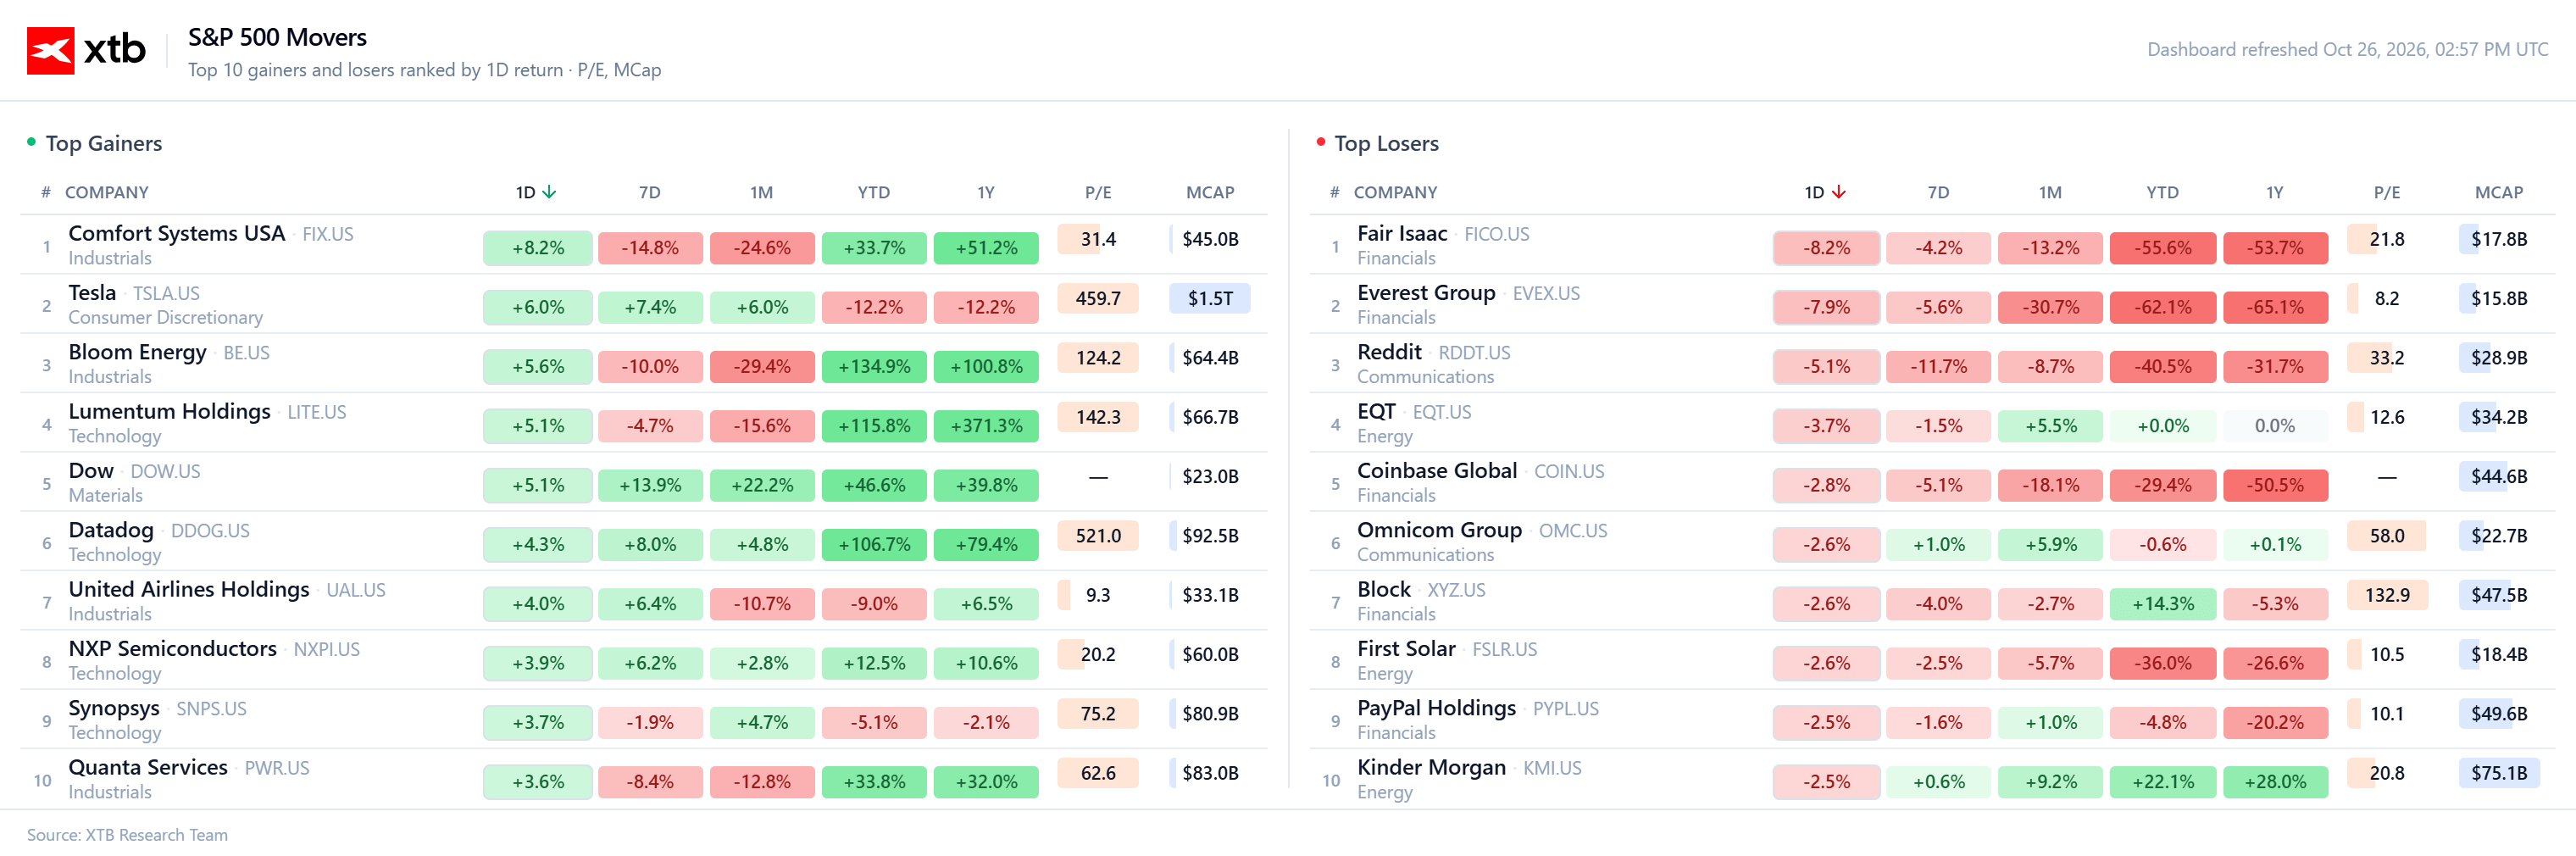
- Tesla (TSLA.US): Shares gain about 6% after a Barclays note. The bank points to potential opportunities tied to a transaction with SpaceX.
- CoreWeave (CRWV.US): Shares erase decline after Antropic publications and turn possitive by around 5%.
- Borr Drilling (BORR.US): Shares fall about 8% after the Prospector 5 rig sank off the coast of Gabon on Saturday, October 24.
- Surgery Partners (SGRY.US): Shares jump more than 45% on reports of advanced talks for Bon Secours Mercy Health to acquire a controlling stake. The deal would value the company at about $6 billion, including $3.5 billion of debt.
- Ross Stores (ROST.US): Shares gain about 3% after a positive note from UBS.
- MercadoLibre (MELI.US): Shares fall more than 10%. The e-commerce platform is under pressure from the broad selloff in Brazil-linked assets following the presidential election result.
US100 (D1) technical analysis
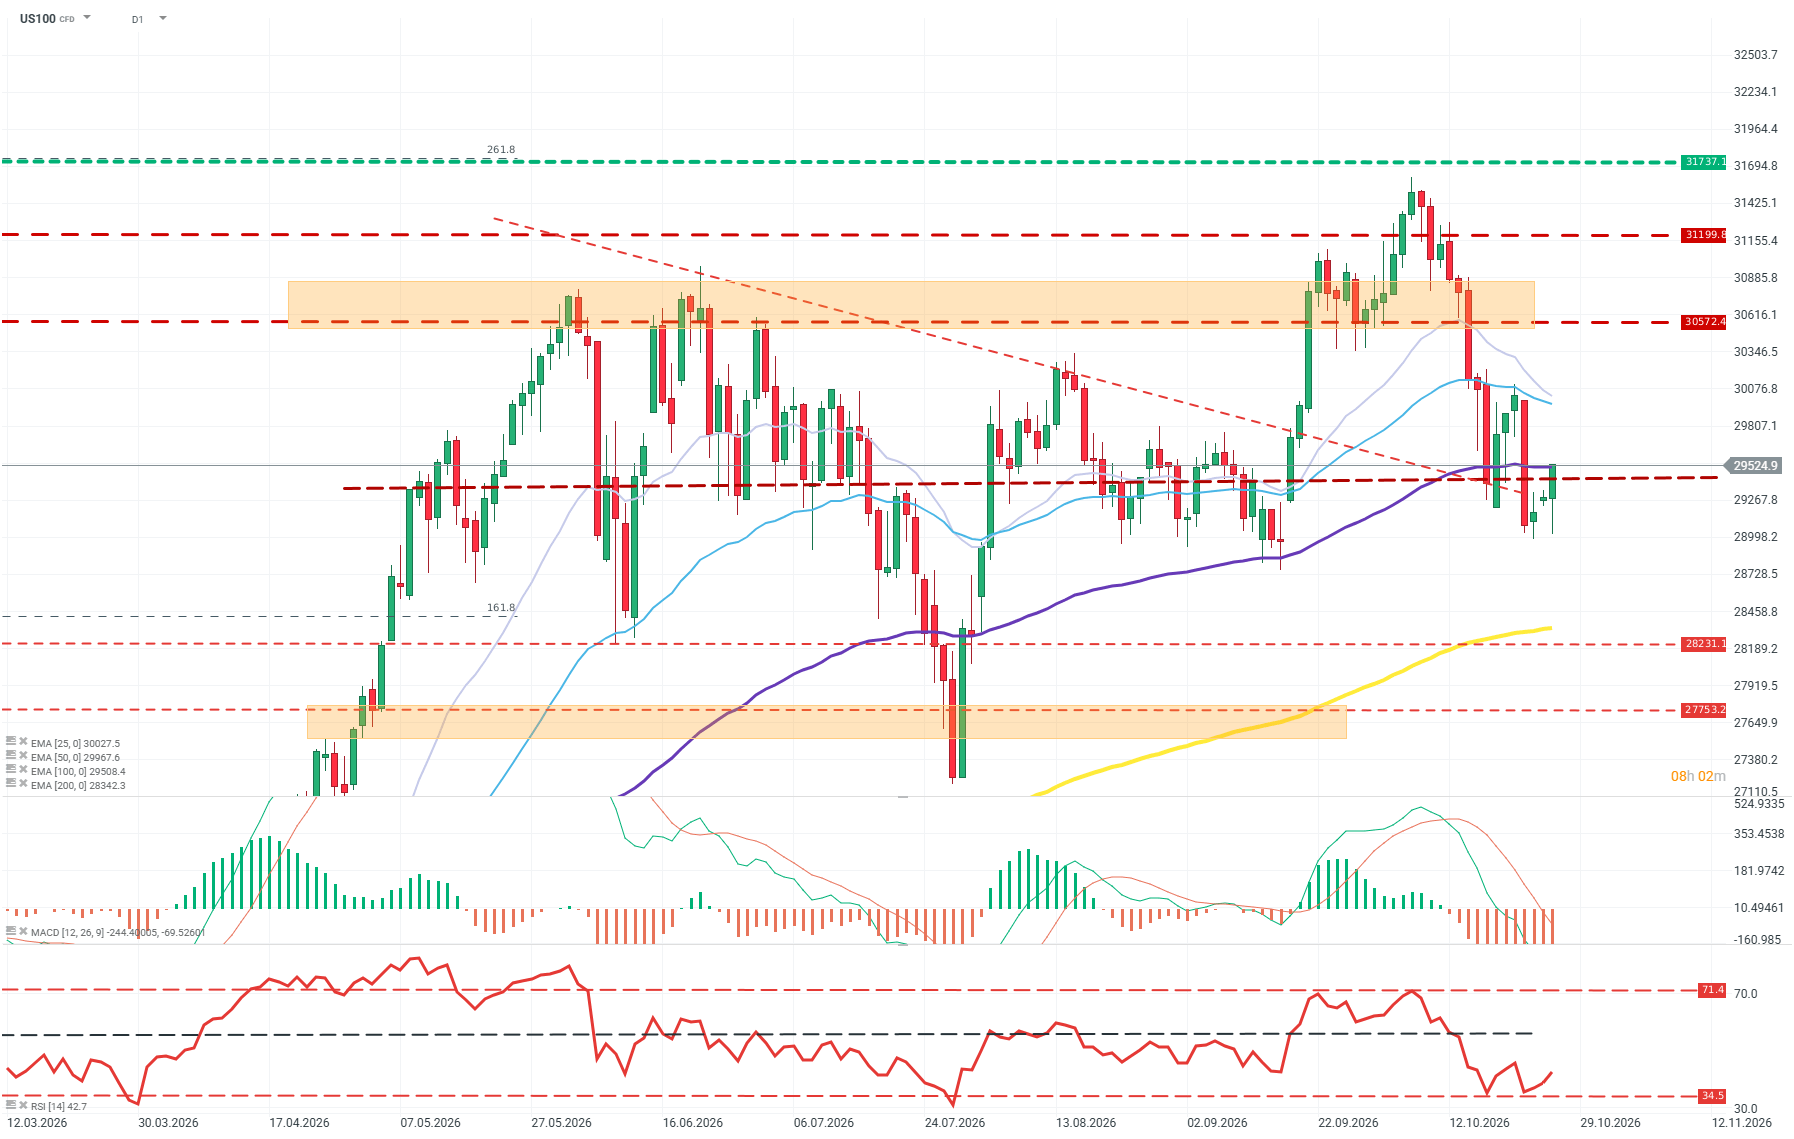
The price remains in a short-term correction, although the long-term uptrend has not yet been invalidated. Quotes are currently testing the EMA100 while remaining below the EMA25 and EMA50 (around 30,000 points), indicating the current supply advantage. RSI at 42.7 suggests a gradual slowdown in downward pressure, but MACD remains negative. The key support is the ~29,500 zone, a break of which could open the way lower. By contrast, reclaiming 30,000 would increase the chances of a move toward the 30,500 resistance area. Source: xStation5
Macroeconomic data:
- One of the main factors shaping sentiment this week will likely be the Federal Reserve’s latest interest rate decision on Wednesday.
- On Tuesday, investors will have a chance to analyze September durable goods orders, which Deutsche Bank analysts estimate will remain stable thanks to AI-related investment spending and large aircraft orders. The consumer confidence survey results are also expected to be released.


Anthropic files prospectus ahead of IPO with "ANT" ticker on Nasdaq. The launch date and price remain a mystery

US Open: Further declines on Wall Street, Brent above 111 USD, AI correction continues (14.10.2026)

Market Wrap: "Decent" results are not enough – tech stocks fall further; oil highest since May (22.10.2026)

Tesla was supposed to burn $5 billion, but posted a positive result. Will Tesla still be a car company in a year?